

One REIT, Inc. Financial Results Deep Dive Report for the Fiscal Period Ended August 2026 (26th Fiscal Period): Progress in Asset Replacement Strategy and Mid-to-Long-Term Growth Scenario
Sentiment Analysis
Overview and Highlights of the 26th Fiscal Period
One REIT, Inc. reported the following results for the fiscal period ended August 2026 (26th fiscal period): operating revenue of 5.647 billion yen (up 956 million yen from the previous period), operating income of 3.038 billion yen (up 684 million yen), ordinary income of 2.487 billion yen (up 564 million yen), and net income of 2.486 billion yen (up 564 million yen).
Distribution per unit (DPU) was 2,553 yen , which was 383 yen (+17.6%) higher than the forecast of 2,170 yen announced on April 14, 2026, and 167 yen (+7.0%) higher than the previous period's actual result of 2,386 yen. The primary factors for this upward variance include the recording of a 586 million yen gain on the sale of a 20% quasi-co-ownership interest in Nagoya Fushimi Square Building (the total gain on property sales was 698 million yen, including a 111 million yen gain on the sale of a 10% interest in ONEST Kyoto Karasuma Square) and higher-than-expected variable rent at DoubleTree by Hilton Naha Shuri Castle.
At the end of the period, the total asset LTV was 49.0% (up 0.5 percentage points from the end of the previous fiscal period), and NAV per unit was 98,000 yen (total capital contribution of about 74,000 yen, unrealized gain of about 24,000 yen).
Summary of Performance Trends and Future Forecasts
The slide below provides an overview of the results for the 26th fiscal period and the earnings forecasts for the 27th and 28th fiscal periods.
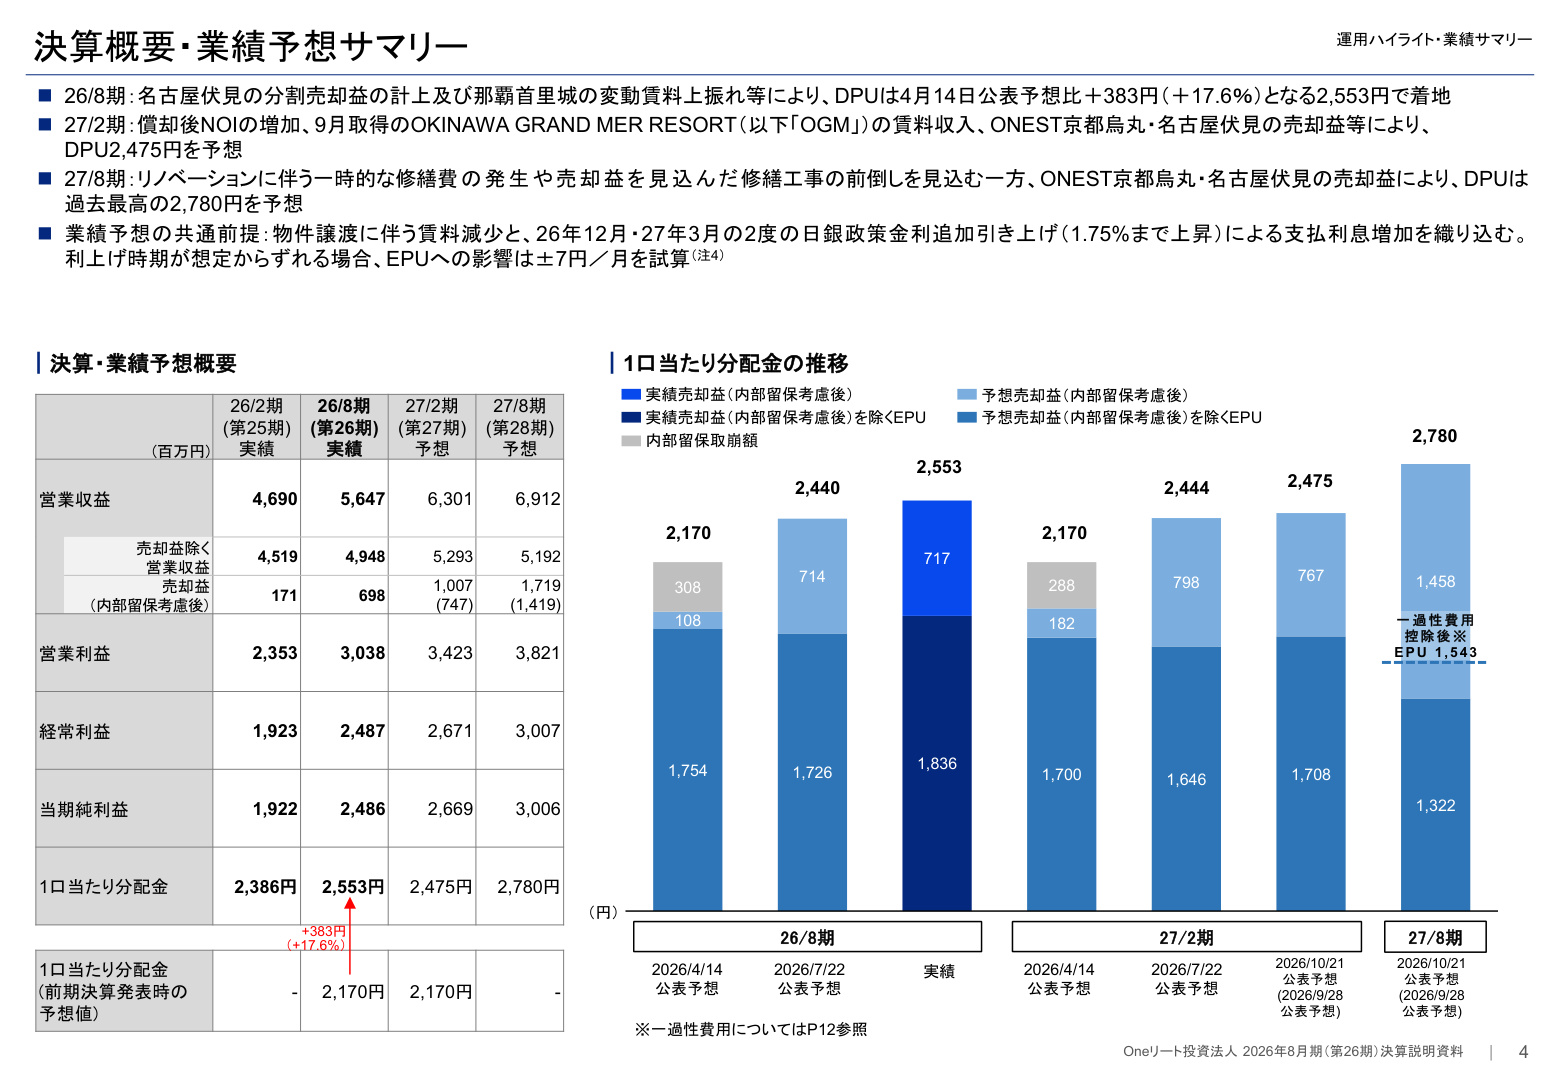
This slide details the actual figures for the current period, as well as the earnings forecasts and the breakdown of distributions for the next two periods.
Assumptions and Summary of Earnings Forecasts
- Forecast for the fiscal period ending February 2027 (27th fiscal period) : We anticipate operating revenue of 6.301 billion yen , operating income of 3.423 billion yen , net income of 2.669 billion yen , and DPU of 2,475 yen . This incorporates the increase in rental income from the acquisition of OKINAWA GRAND MER RESORT (hereinafter "OGM") and the recording of gains on the sale of ONEST Kyoto Karasuma Square (20% interest) and Nagoya Fushimi Square Building (29% interest) (totaling 1.007 billion yen, or 747 million yen after considering internal reserves).
- Forecast for the fiscal period ending August 2027 (28th fiscal period) : We anticipate operating revenue of 6.912 billion yen , operating income of 3.821 billion yen , net income of 3.006 billion yen , and DPU of 2,780 yen . While we expect to record gains on the sale of the remaining 51% interest in Nagoya Fushimi Square Building and the remaining 25% interest in ONEST Kyoto Karasuma Square (totaling 1.719 billion yen, or 1.419 billion yen after considering internal reserves), we also incorporate the occurrence of temporary repair expenses and depreciation associated with the rebranding of Naha Shuri Castle, as well as the front-loading of repair work.
- Interest Rate Assumptions : The earnings forecasts incorporate the increase in interest expenses resulting from two policy rate hikes by the Bank of Japan in December 2026 and March 2027 (rising to 1.75%). According to the calculations in the materials, if the timing of the rate hikes deviates from the assumptions, the impact on EPU (net income per unit) is estimated at ±7 yen per unit per month .
Mid-to-Long-Term Growth Scenario and "Aggressive Divestment"
One REIT, Inc. recognizes an environment where it takes time for rent increases in office buildings and the profit contribution (stabilization) of hotel measures to materialize, while rising interest rates and various costs act as downward factors for earnings. In response, against the backdrop of trends in the real estate trading market, we have presented a policy to promote "aggressive divestment" on a scale of 20 billion yen and reinvestment.
Key Points of the Mid-to-Long-Term Growth Scenario
- Implementation of "Aggressive Divestment" : We have selected divestment candidates on a scale of about 20 billion yen from the perspective of future profitability, downside risk to cash flow, and maximization of gains on sales, and we are continuing discussions with multiple companies aiming for divestment at or above appraisal value.
- Support Period Until Hotel Stabilization : We have positioned the next three years (from the fiscal period ending February 2027 to the fiscal period ending August 2029), until the earnings improvement of hotels fully materializes, as a period to support DPU through gains on sales from asset replacement.
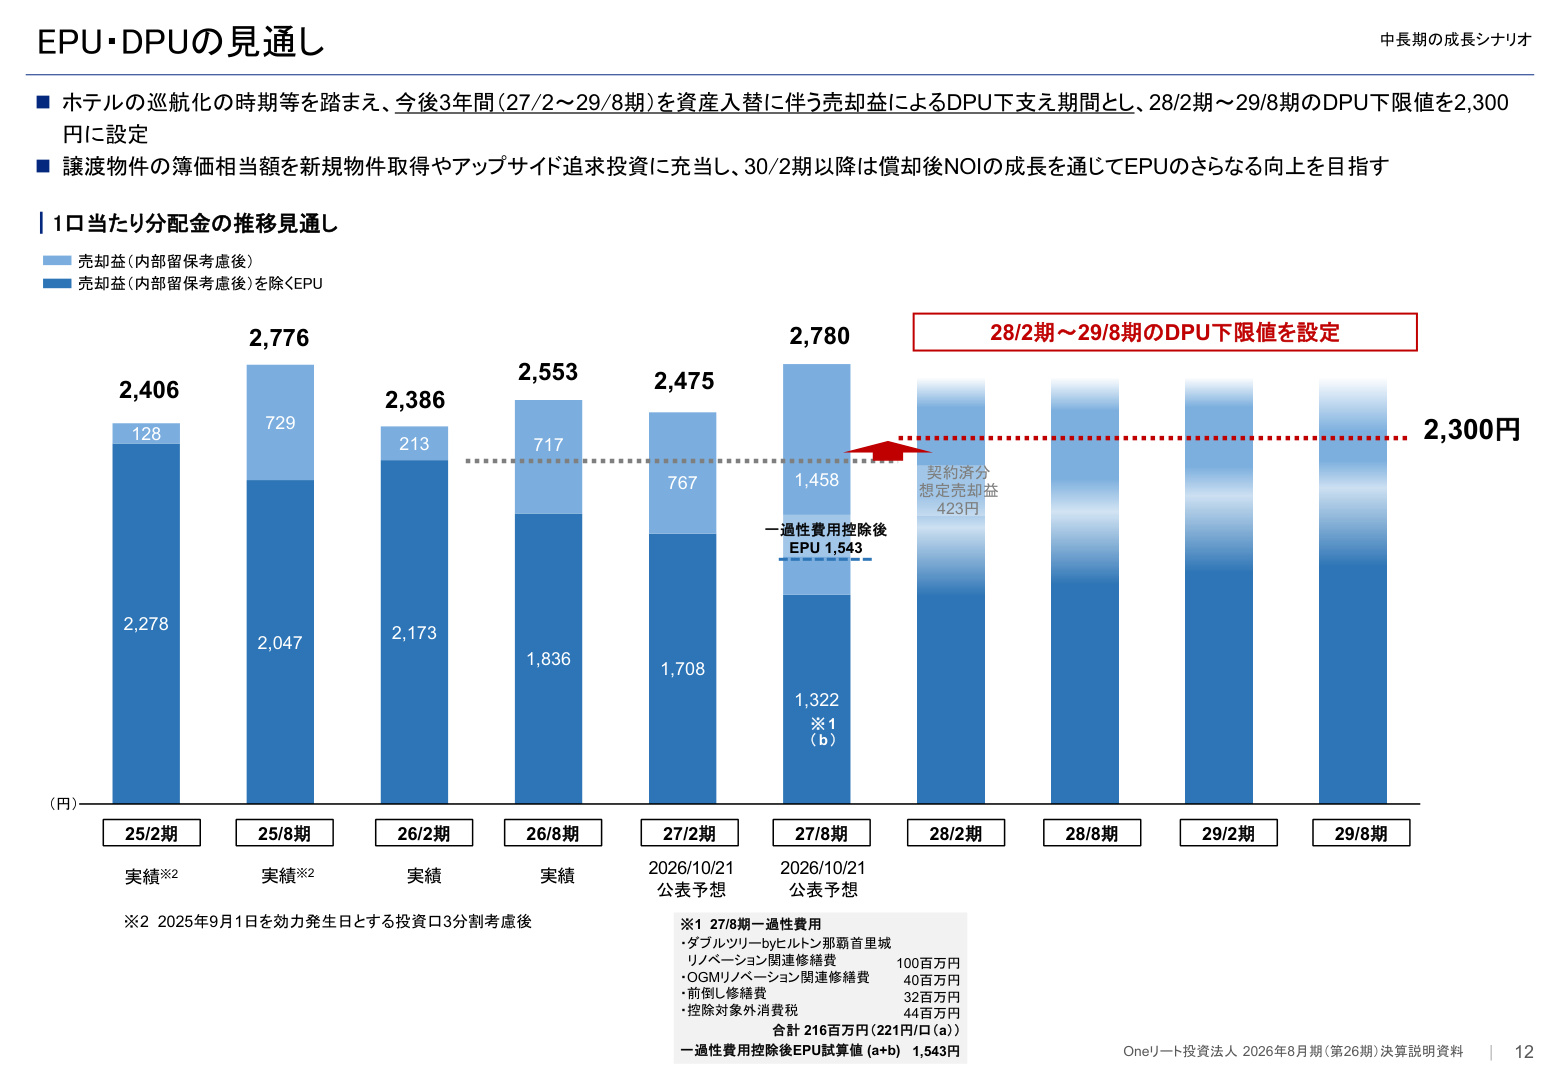
As shown in the slide above, One REIT, Inc. has set a "DPU floor of 2,300 yen" from the fiscal period ending February 2028 through the fiscal period ending August 2029. We plan to reinvest the book value equivalent of divested properties into new property acquisitions or "upside-seeking investments," and from the fiscal period ending February 2030 onwards, we aim to improve the level of EPU itself through the growth of NOI after depreciation. From the 27th to the 28th fiscal period, we anticipate temporary expenses such as renovation-related repair expenses for Naha Shuri Castle and OGM, and front-loaded repair expenses (totaling 216 million yen in the 28th fiscal period, equivalent to 221 yen per unit). The calculated EPU after deducting these temporary expenses is shown as 1,543 yen.
Specific Measures for Asset Replacement: Nagoya Fushimi Square Building and OKINAWA GRAND MER RESORT
The first step of our mid-to-long-term strategy was the split divestment of the Nagoya Fushimi Square Building, a 38-year-old office building, and the acquisition of the resort hotel "OKINAWA GRAND MER RESORT (OGM)" in Okinawa City, Okinawa Prefecture.
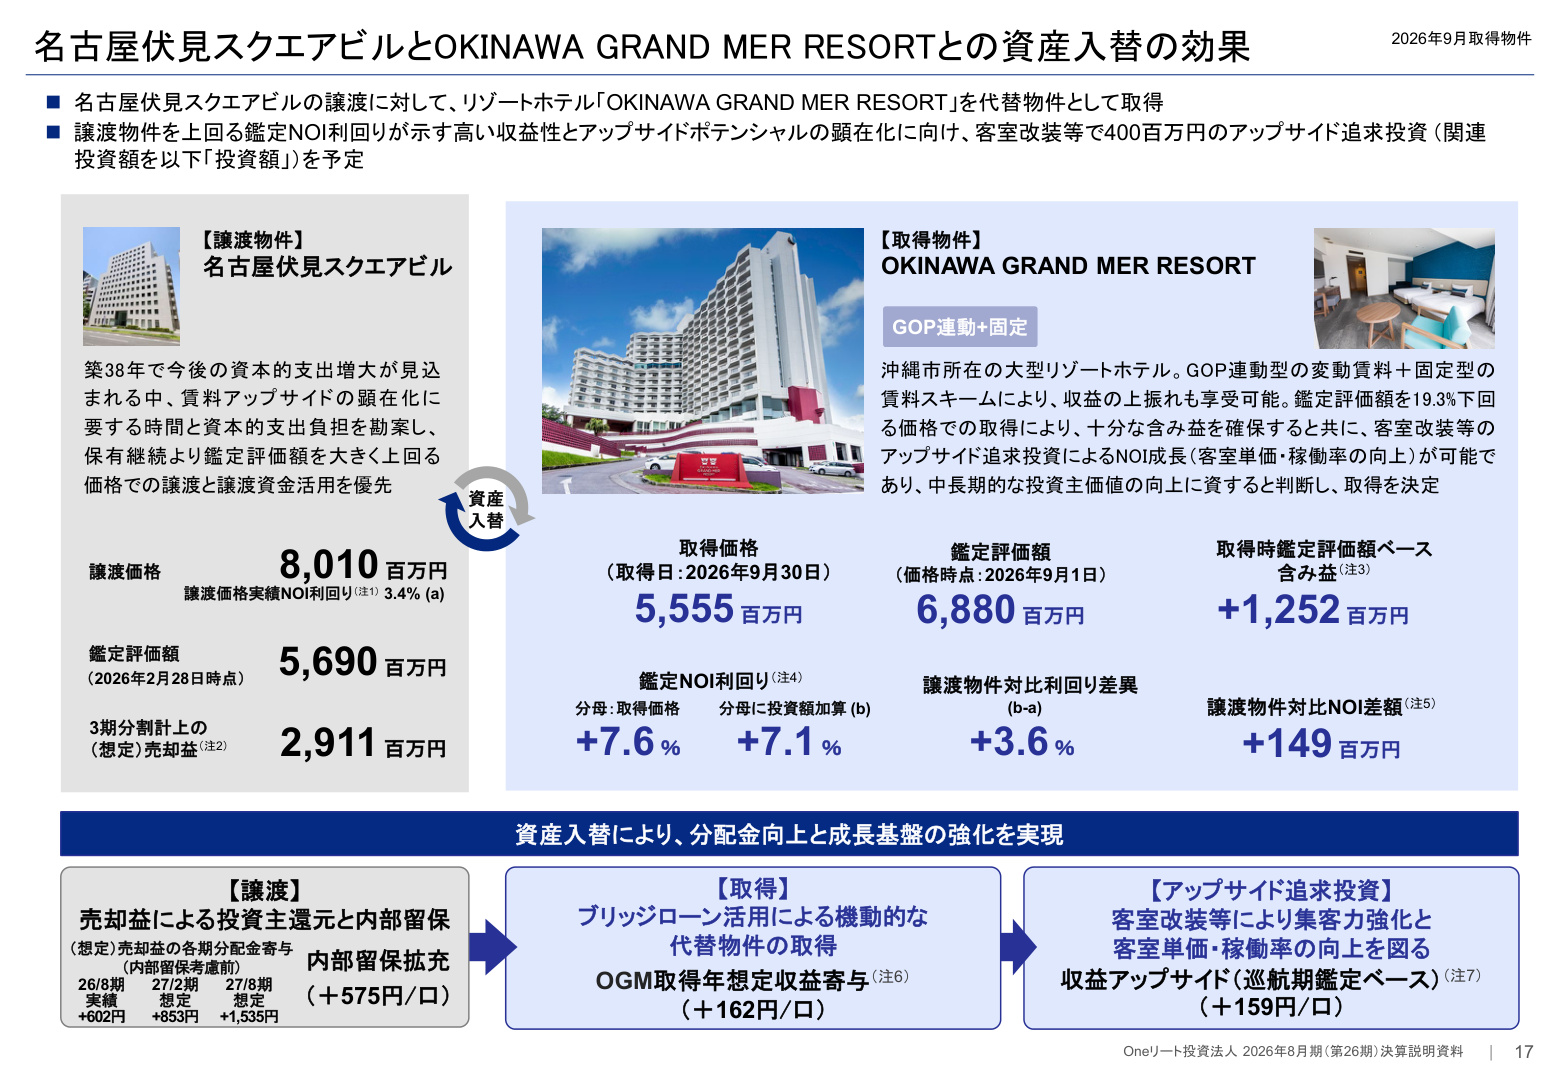
This slide shows the specific changes in the financial and earnings structure resulting from the asset replacement.
Key Conditions and Effects of Asset Replacement
- Divested Property (Nagoya Fushimi Square Building) :
- Divestment price: 8.01 billion yen (a level 40.8% higher than the appraisal value of 5.69 billion yen, and +68% compared to book value).
- Actual NOI yield at divestment price: 3.4% .
- Through a three-stage split divestment (20% in 26/8, 29% in 27/2, 51% in 27/8), we expect a total gain on sale of 2.911 billion yen . This gain on sale will be used for distribution and for expanding internal reserves (+575 yen per unit) to prepare for future earnings fluctuations.
- Acquired Property (OKINAWA GRAND MER RESORT) :
- Acquisition price: 5.555 billion yen (acquisition date: September 30, 2026). It was acquired at a price 19.3% lower than the appraisal value of 6.88 billion yen at the time of acquisition, containing an unrealized gain of 1.252 billion yen at the time of acquisition.
- Appraisal NOI yield: +7.6% based on acquisition price (+7.1% based on investment amount including costs), resulting in a yield spread of +3.6 percentage points against the 3.4% yield of the divested property.
- The NOI difference is +149 million yen , and the estimated earnings contribution of OGM in the acquisition year is +162 yen per unit , with an earnings upside of +159 yen per unit based on the appraisal at the stabilization stage.
OGM Property Characteristics and Upside-Seeking Investment OGM is a large resort hotel with 300 guest rooms and a capacity of about 900 people. Okinawa City has zero new guest room supply scheduled for hotels and inns from 2026 to 2029, and it has the characteristics of being a recipient of group accommodation demand in the surrounding area. One REIT, Inc. will implement about 400 million yen in upside-seeking investment from late January to late April 2027, including converting 40 guest rooms to Western-style, renovating 6 suites, and refurbishing common areas, with the renewal scheduled to start in May 2027. We have appointed Kato Pleasure Group (KPG HOTEL & RESORT) as the operator and adopted a variable rent scheme linked to GOP plus fixed rent.
Portfolio Status and Operational Trends by Segment
1. Overall Portfolio and Growth Targets With the acquisition of OGM in September 2026, the asset scale of the portfolio reached 156.7 billion yen (composition by use: 72.4% offices, 27.6% hotels). One REIT, Inc. has set a medium-term target asset scale of 200 billion yen , and the target portfolio composition upon achieving this is 60% or more for office buildings and 40% or less for hotels, etc. Through information provided by the sponsor and proprietary sourcing, we have secured a pipeline of acquisition candidate properties worth about 30 billion yen (approx. 30% offices, 70% hotels).
2. Office Portfolio Operations
- Occupancy Rate and Leasing : The office occupancy rate at the end of the fiscal period ended August 2026 was 98.3% (97.6% average during the period), which was 1.5 percentage points higher than the initial forecast of 96.8%. Contracts for large sections progressed, and the tenant renewal rate was 99.2% on an area basis. The occupancy rate forecast for the end of the fiscal period ending February 2027 is 99.2%, and for the fiscal period ending August 2027, it is expected to be 98.5% due to some expected move-outs.
- Progress in Rent Increases : The monthly rent increase in the 26th fiscal period, including both existing contract revisions and new contracts (replacements), totaled 11.036 million yen/month , marking a record high (up 1.8% compared to contracts at the end of the previous period). The increase rate against pre-revision rent was +9.4% for existing contracts and +25.7% for new contracts.
- Rent Gap : With the rise in market rents, the rent gap for office sections in the portfolio including ONEST Iidabashi Square has expanded to -12.6% (-10.0% in the Tokyo economic zone, -17.8% outside the Tokyo economic zone), indicating that there is room for rent increases by resolving under-rent situations.
3. Hotel Portfolio Operations
- Operational Results : The cumulative RevPAR of the 5 discloseable properties ended up +4.3% year-on-year (occupancy rate 85.9%, ADR 9,554 yen). Total hotel rent for variable rent properties exceeded the April 14, 2026 forecast of 544 million yen by 22 million yen.
- Rebranding and Operational Measures : Earnings improvement measures through upside-seeking investments are underway, such as Naha Shuri Castle (operator change in January 2027, rebranding construction from January to June) and The Edister Hotel Narita (construction from September 2026 to January 2027, scheduled to open in February 2027).
Trends in Financial Management
On the financial front, we carried out refinancing of 15 billion yen on July 10, 2026, and 12.12 billion yen on September 7, 2026, inviting 5 new lenders to diversify our lender composition. As of September 30, 2026, the average interest rate was 1.475% , the average remaining duration was 2.47 years , and the fixed interest rate ratio was 59.0% .
Regarding the acquisition funds for OGM on September 30, 2026, they were procured through a bridge loan from Mizuho Bank, and we plan to proceed with repayment as we receive the proceeds from the scheduled split sale of the Nagoya Fushimi Square Building.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.