

Home Position Co.,Ltd. FY2026 Financial Results: V-Shaped Recovery with 87% Growth in Operating Profit and New Mid-Term Management Plan Targeting 30 billion yen in Sales
Sentiment Analysis
1. FY2026 Full-Year Financial Highlights and Significant Profit Recovery
Home Position Co.,Ltd. achieved a strong V-shaped recovery in its full-year financial results for the fiscal year ended August 2026, with both sales and profits at all levels significantly exceeding the previous fiscal year's performance.
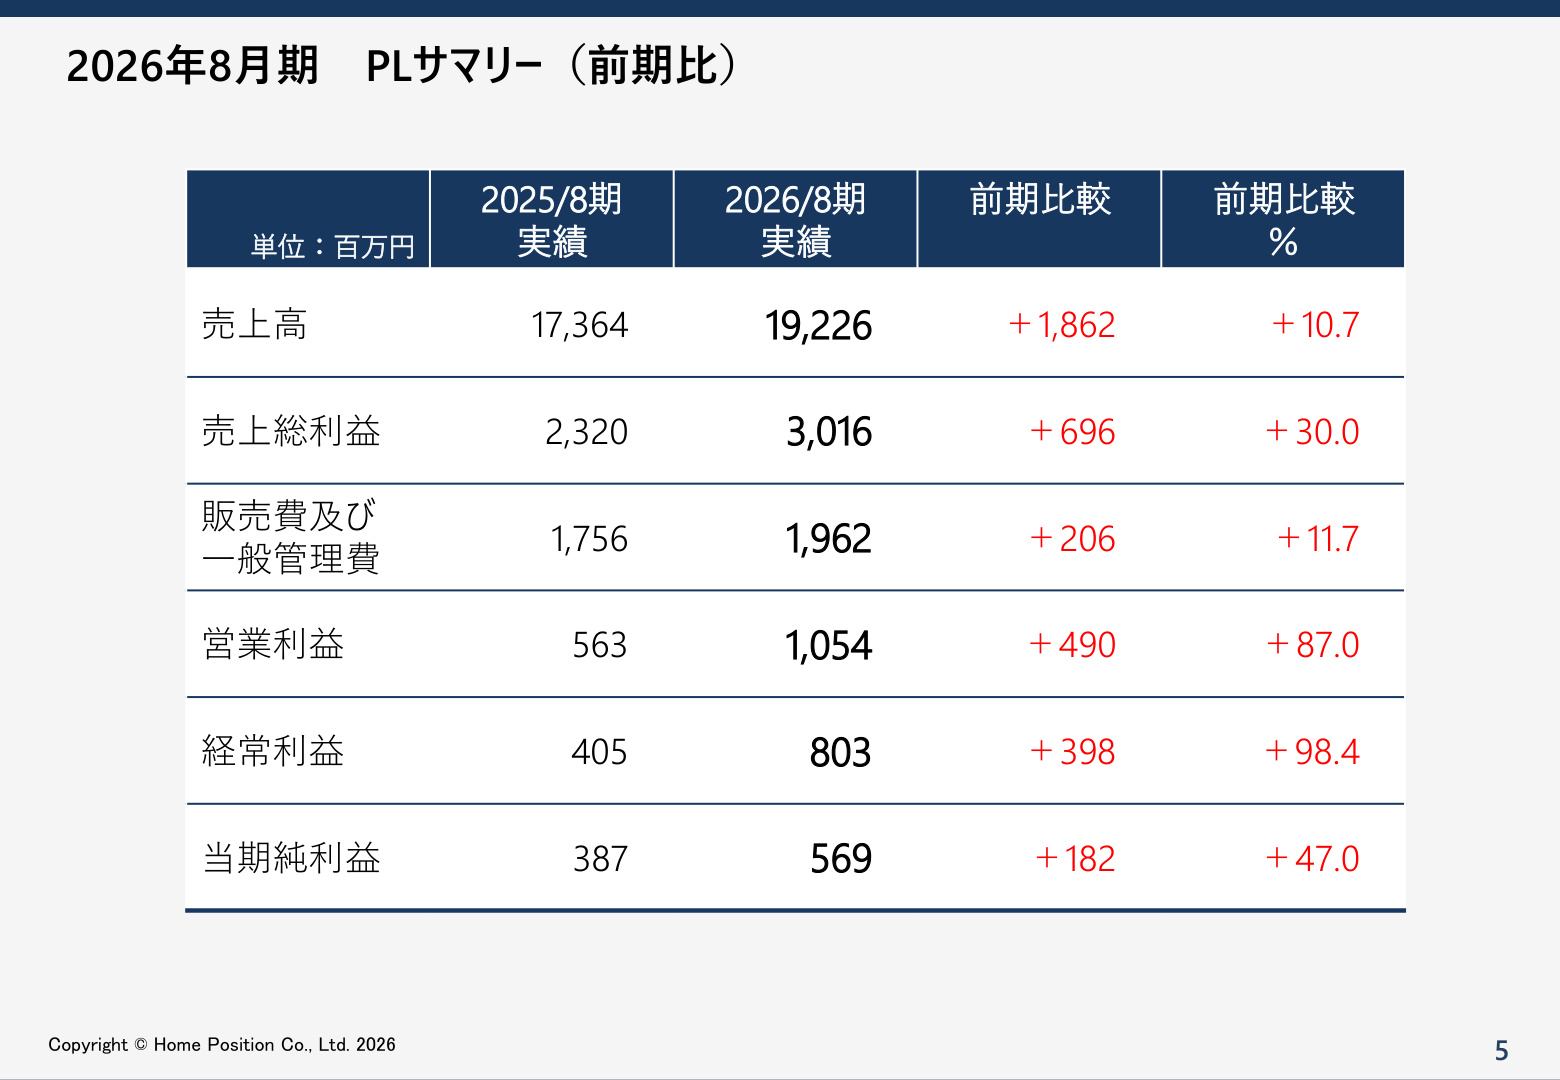
As shown in the slide above, the financial results for the fiscal year ended August 2026 are as follows:
- Net Sales : 19,226 million yen (+10.7% YoY)
- Gross Profit : 3,016 million yen (+30.0% YoY)
- Operating Profit : 1,054 million yen (+87.0% YoY)
- Ordinary Profit : 803 million yen (+98.4% YoY)
- Net Income : 569 million yen (+47.0% YoY)
- ROE : 9.5% (+1.1pt YoY)
The significance of these financial highlights lies in the fact that gross profit (+30.0%) and operating profit (+87.0%) are expanding rapidly , significantly outpacing the growth rate of net sales (+10.7%). This clearly demonstrates the steady transition to a highly profitable business structure, driven by the completion of the disposal of long-term stagnant inventory, the promotion of selective land procurement, and the strengthening of sales activities.
Although selling, general and administrative (SG&A) expenses increased to 1,962 million yen (+11.7% YoY) due to business expansion, the increase in gross profit (+696 million yen) significantly absorbed the rise in SG&A expenses (+206 million yen), resulting in operating profit nearly doubling from 563 million yen in the previous fiscal year to 1,054 million yen.
2. Progress Against Initial Plans and Quarterly Trends
Compared to the initial plans, the company achieved performance that significantly exceeded all profit indicators.
- Net Sales : 19,226 million yen against an initial plan of 19,000 million yen (+1.2% vs. plan, +226 million yen)
- Operating Profit : 1,054 million yen against an initial plan of 500 million yen (+110.8% vs. plan, +554 million yen)
- Ordinary Profit : 803 million yen against an initial plan of 350 million yen (+129.6% vs. plan, +453 million yen)
- Net Income : 569 million yen against an initial plan of 240 million yen (+137.4% vs. plan, +329 million yen)
Even when compared to the revised plan disclosed on July 10, 2026 (operating profit of 1,040 million yen, ordinary profit of 800 million yen, and net income of 540 million yen), the results exceeded these levels, confirming that the momentum of profit margin improvement was maintained through the second half of the year.
Looking at the quarterly sales volume trends, after 205 units in Q2 FY2024 (a temporary increase due to long-term inventory disposal) and 81 units in Q1 FY2025 (affected by suppressed procurement), the company has recovered to a stable cruising level in FY2026, with 139 units in Q1, 138 units in Q2, 117 units in Q3, and 137 units in Q4. Particularly in the high-demand Kanto area, the company recorded 75 sales in Q4, indicating that a virtuous cycle of procurement and sales is being established.
3. Changes in Asset Structure and Expansion of Inventory Portfolio
As a leading indicator supporting the company's future business expansion, the trend of inventories on the balance sheet (BS) is noteworthy.
- Current Assets : 17,594 million yen (+3,785 million yen from the end of the previous fiscal year)
- Real Estate for Sale (Completed Inventory, etc.) : 2,934 million yen (-209 million yen from the end of the previous fiscal year)
- Real Estate for Sale in Process (Under Procurement/Construction) : 11,437 million yen (+3,898 million yen from the end of the previous fiscal year)
- Fixed Assets : 340 million yen (-324 million yen from the end of the previous fiscal year, decrease due to the sale of rental properties)
- Short-term Loans Payable : 7,558 million yen (+2,047 million yen from the end of the previous fiscal year)
- Total Net Assets : 6,256 million yen (+487 million yen from the end of the previous fiscal year)
Quarterly trends in total inventory balance bottomed out at 8,223 million yen in Q4 FY2024 and reached 14,371 million yen at the end of Q4 FY2026. It is worth noting that while real estate for sale (completed inventory) is being appropriately controlled and is on a downward trend, real estate for sale in process, which will serve as the source of future sales, has been significantly increased. By area, active land procurement is being carried out, centered on the Kanto area where sales are strong, building a robust pipeline for future sales expansion.
4. FY2027 Full-Year Earnings Forecast and Acceleration of Growth
Against the backdrop of accumulated inventory in process, the company plans to jump to a sales scale of 25 billion yen in FY2027.
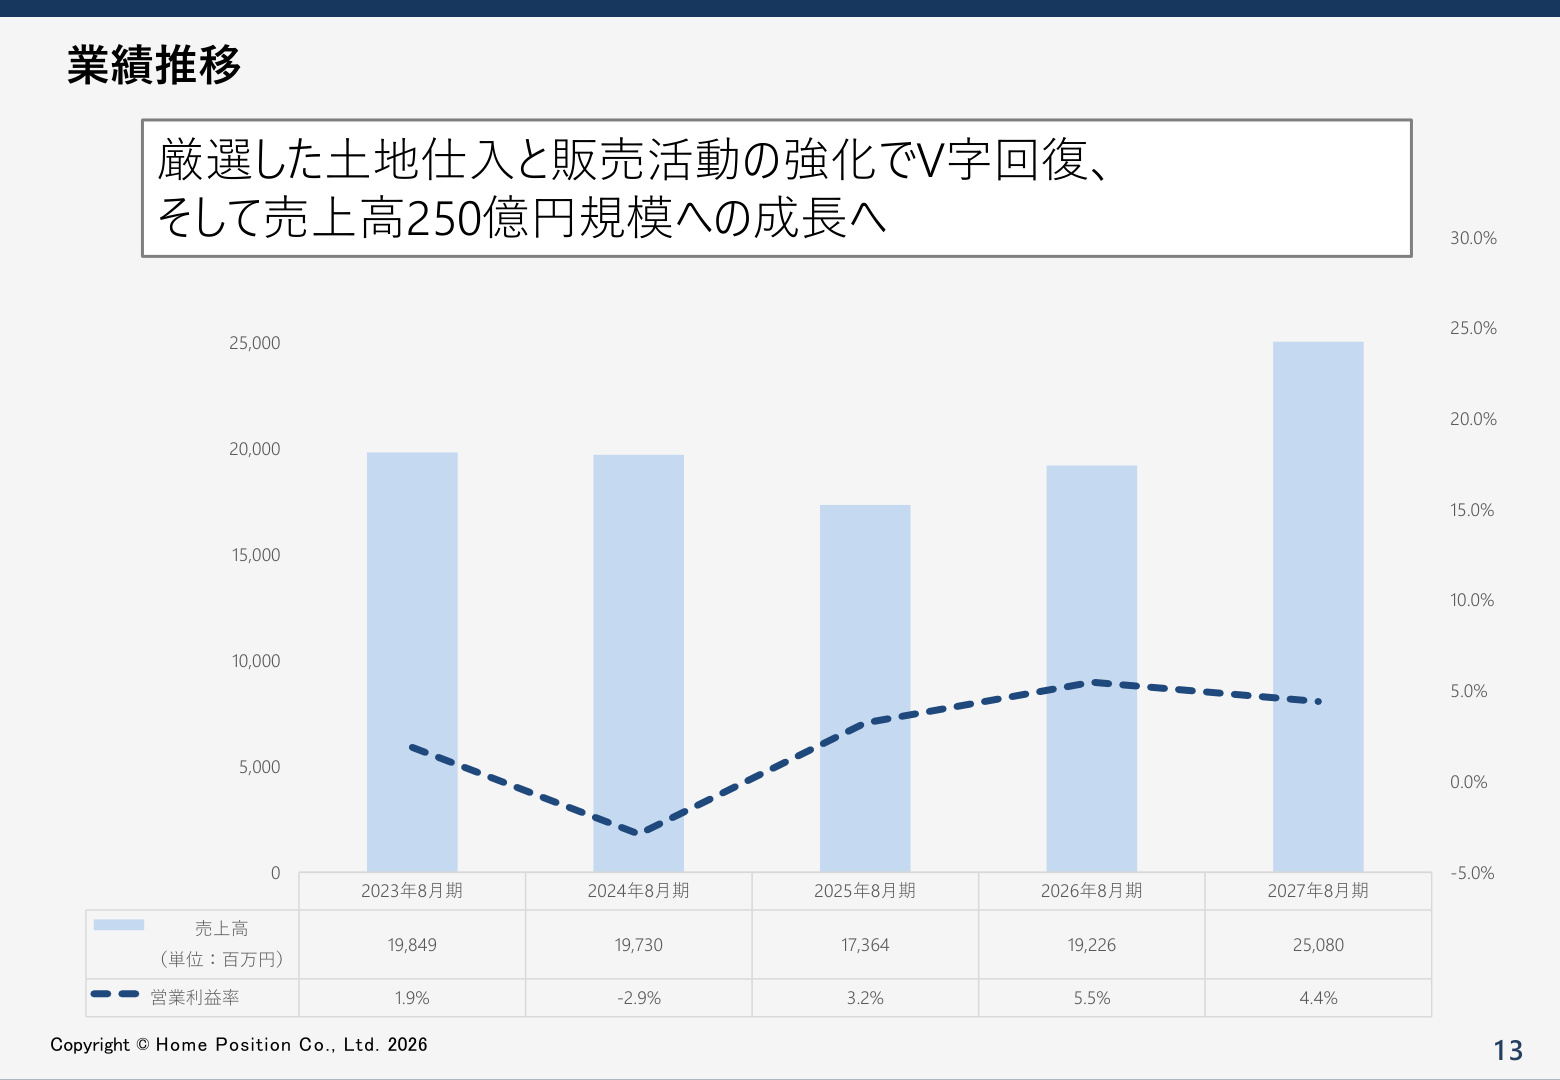
The full-year earnings forecast for FY2027 is as follows:
- Net Sales : 25,080 million yen (+30.4% YoY, +5,853 million yen)
- Operating Profit : 1,107 million yen (+5.0% YoY, +52 million yen)
- Ordinary Profit : 785 million yen (-2.3% YoY, -18 million yen)
- Net Income : 543 million yen (-4.7% YoY, -26 million yen)
The most important implication of this earnings forecast slide is that the company has shifted its phase from a "period of structural improvement" to a " period of full-scale business expansion ." By promoting high-quality land procurement and organizational strengthening, the company expects a 30.4% year-on-year increase in sales. In terms of profit, considering the burden of borrowing interest and upfront investments, the plan projects a slight increase of 5.0% in operating profit and a slight decrease in ordinary profit and net income. However, by establishing a 25 billion yen sales structure, the company is positioning itself to solidify a strong foundation for achieving the next mid-term management plan.
Regarding shareholder returns, the company maintains a basic policy of returning profits through dividends and has paid dividends every term since listing. The policy to maintain an annual dividend of 10 yen per share (forecast EPS of 57.79 yen) for FY2027 has also been indicated.
5. Overall Concept of the New Mid-Term Management Plan (FY2027–FY2029)
Home Position Co.,Ltd. has formulated a new mid-term management plan (FY2027–FY2029) aimed at sustainable growth and the maximization of corporate value. The theme of the new plan is " —Transformation to a profit-oriented structure through differentiation & Maximization of corporate value through strengthened risk management and financial discipline— ."
Management Vision and Business Strategy Drivers
With the vision of "becoming the most trusted, one-of-a-kind company in the region by providing high quality that exceeds the common sense of built-for-sale housing at an affordable price," the company aims to achieve high turnover and high profitability through the following operational mechanisms, rather than just competing for sales volume share:
- Differentiation (Securing an "Exit" through a high-value-added strategy) : In addition to uniqueness through "Design x ZEH," the company provides products that align with national policies and market trends as a company strongly promoting GX. By breaking away from price competition with power builders, it secures price maintenance power that can be appropriately passed on even when costs rise.
- Reproducibility (Digital customer acquisition and investment evaluation model) : By focusing sales strategies on web marketing and fixed brokerage networks, the company eliminates reliance on specific individuals and resolves inconsistencies in sales performance.
- Speed (Mechanism to support inventory turnover) : Using a proprietary evaluation algorithm, the company blocks properties at the entry stage that are not expected to have a fast recovery speed. Lead times are shortened through design standardization and the use of DX such as BIM.
- Stable Gross Profit (Approval process where "profit is determined at the time of procurement") : Instead of "profit remaining after selling," the company strictly enforces a system of only procuring properties that clear rigorous investment hurdle criteria.
- New Business (Diversification of portfolio) : By leveraging its know-how in new built-for-sale housing, the company will fully launch a used renovation and remodeling business to diversify risks against macro environmental changes such as interest rate hikes.
Procurement Decision Algorithm and Four Defensive Strengths
The decision-making process for procurement will evolve from traditional "intuition" to an " algorithm ," strictly judging each property based on two axes: "profitability" and "speed of capital recovery (time value)." Furthermore, by using four defensive logics—"product defense," "business defense," "sales defense," and "financial defense"—the company will build a robust risk management system capable of withstanding market fluctuations.
6. Mid-Term Numerical Targets and Growth Roadmap
The three-year numerical plan disclosed in the slide above through FY2029 is as follows:
- FY2027 : Net Sales 25,080 million yen / Gross Profit 3,385 million yen / Operating Profit 1,107 million yen / Ordinary Profit 785 million yen / Net Income 543 million yen
- FY2028 : Net Sales 28,000 million yen / Gross Profit 3,920 million yen / Operating Profit 1,400 million yen / Ordinary Profit 1,040 million yen / Net Income 720 million yen
- FY2029 : Net Sales 30,000 million yen / Gross Profit 4,350 million yen / Operating Profit 1,560 million yen / Ordinary Profit 1,140 million yen / Net Income 789 million yen
The important roadmap indicated by this plan is to expand net sales by approximately 1.56 times (from 19.2 billion yen to 30 billion yen) and operating profit by approximately 1.48 times (from 1.05 billion yen to 1.56 billion yen) over three years, aiming for a constant 750 units sold and an operating profit margin of over 5% in the final year.
As a prerequisite for supporting this growth, the plan explicitly states the promotion of asset-light management by increasing the composition ratio of the "used renovation and remodeling business," which has a relatively fast capital recovery speed, to improve the company-wide inventory turnover efficiency. Furthermore, the strategy shows that by accelerating the turnover of invested capital, the company will avoid excessive dependence on external interest-bearing debt and achieve both a strong financial structure and high capital efficiency while applying financial leverage discipline.
In summary, the financial results of Home Position Co.,Ltd. present a growth scenario that has moved past the inventory adjustment phase, with a track record of rapidly expanding operating profit and a clear path toward 30 billion yen in sales under the discipline of introducing procurement algorithms and asset-light management.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.