

KOSHIDAKA HOLDINGS Co.,LTD. Fiscal Year Ended August 2026 Earnings In-Depth Report: Growth Scenario Toward Surpassing 80 billion Yen in Sales via Large-Scale M&A and Double-Digit Profit Growth in the Next Fiscal Year
Sentiment Analysis
KOSHIDAKA HOLDINGS Co.,LTD. Fiscal Year Ended August 2026 Earnings In-Depth Report
KOSHIDAKA HOLDINGS Co.,LTD. (Securities Code: 2157) has significantly expanded its business scale through aggressive new store openings for its core karaoke business, "Karaoke Manekineko," as well as the acquisition of Standard Corp. (a former subsidiary of XING Inc.), which brought approximately 70 directly operated "JOYSOUND" stores into the group. Based on the published earnings presentation materials, this report provides a comprehensive analysis of the performance trends for the fiscal year ended August 2026, rapid changes in the cost structure, KPI transitions, financial and cash flow status, and earnings forecasts and shareholder return policies for the fiscal year ending August 2027.
1. Fiscal Year Ended August 2026 Consolidated Earnings Highlights
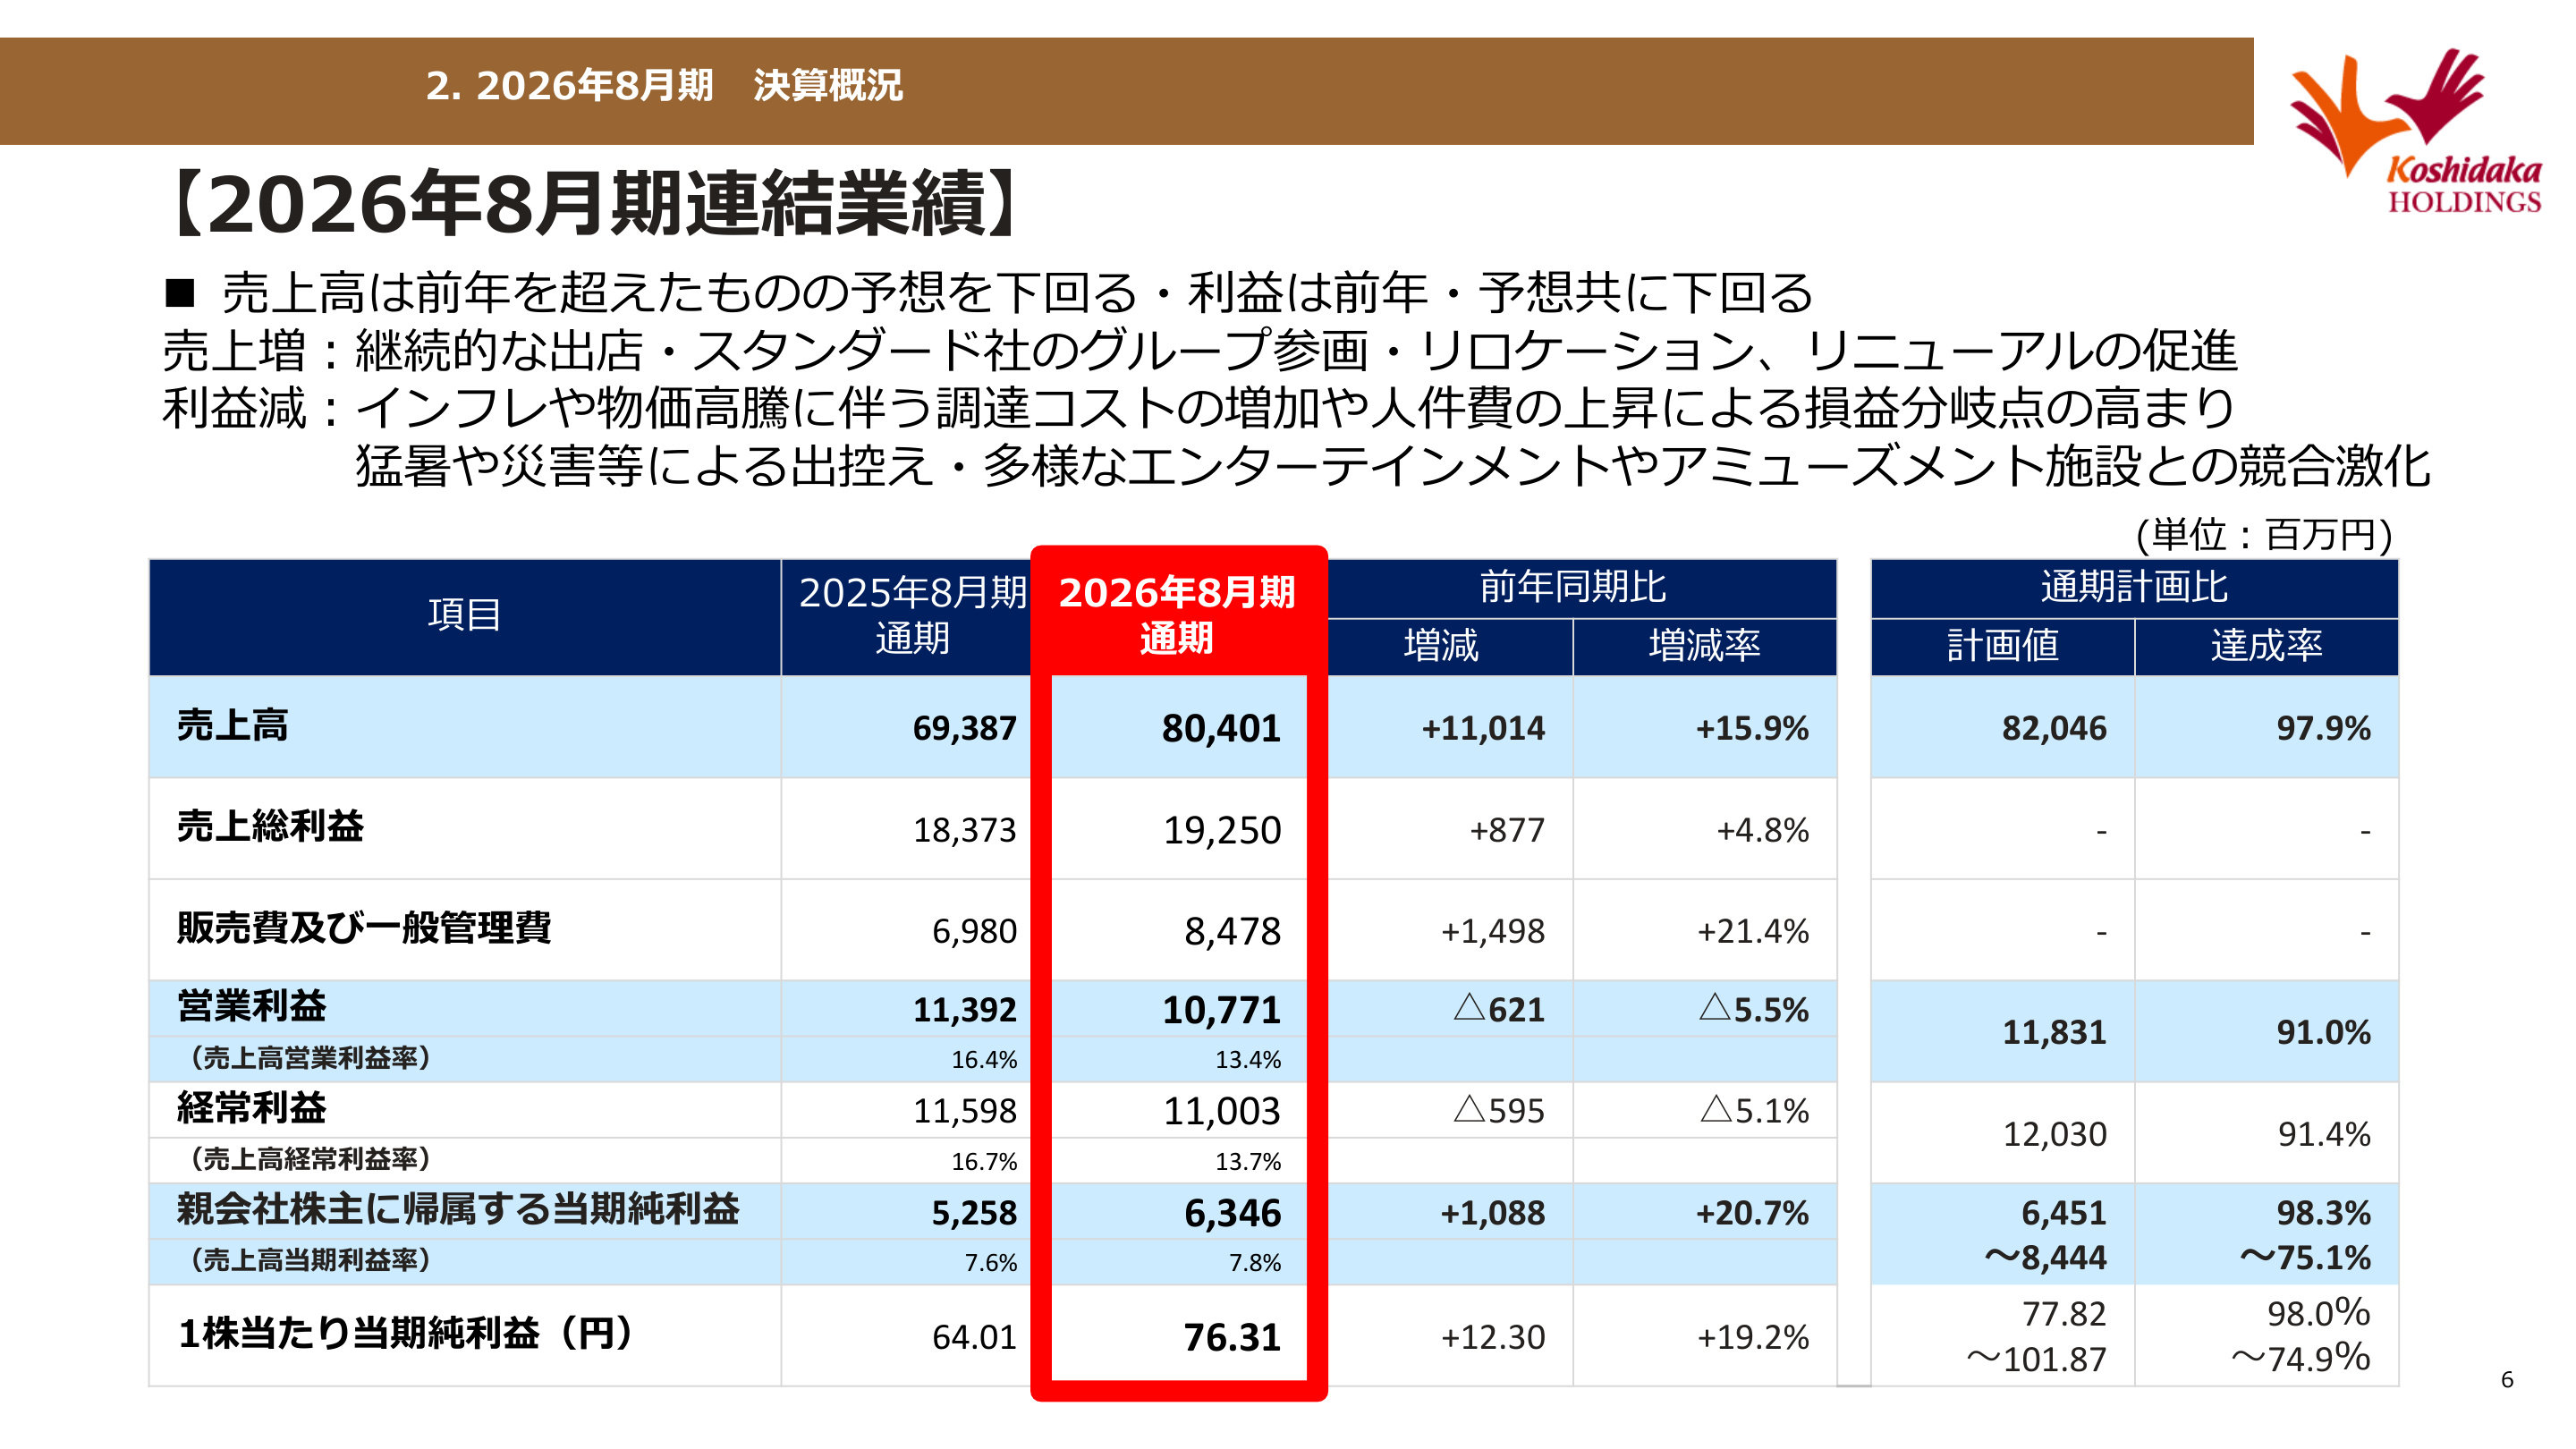
For the fiscal year ended August 2026, consolidated earnings reached a record high, with net sales increasing 15.9% year-on-year to 80.401 billion yen . Meanwhile, operating profit decreased 5.5% year-on-year to 10.771 billion yen , and ordinary profit decreased 5.1% year-on-year to 11.003 billion yen , resulting in higher sales but lower profits. However, profit attributable to owners of parent increased 20.7% year-on-year to 6.346 billion yen , achieving double-digit profit growth.
Background and Significance of Performance Figures
The slide above is a crucial document showing the overall picture of the consolidated statement of income for the fiscal year ended August 2026 and the progress against the full-year plan. Although net sales surpassed the 80 billion yen mark, the achievement rate against the full-year plan (82.046 billion yen) was 97.9%, falling slightly short. Operating profit also reached 91.0% of the plan (11.831 billion yen).
In terms of sales, continuous new store openings , the inclusion of Standard Corp. in the group , and the promotion of relocations and renewals drove the revenue increase. On the profit side, however, the gross profit margin and operating profit margin were pressured by factors such as increased procurement costs due to inflation and rising prices , higher break-even point sales due to rising labor costs including minimum wage revisions, as well as reduced outings caused by the intense summer heat and natural disasters, and intensified competition with diversified entertainment and amusement facilities.
2. Analysis of Factors Behind Operating Profit Changes: Breakdown of Sales Expansion and Cost Increases
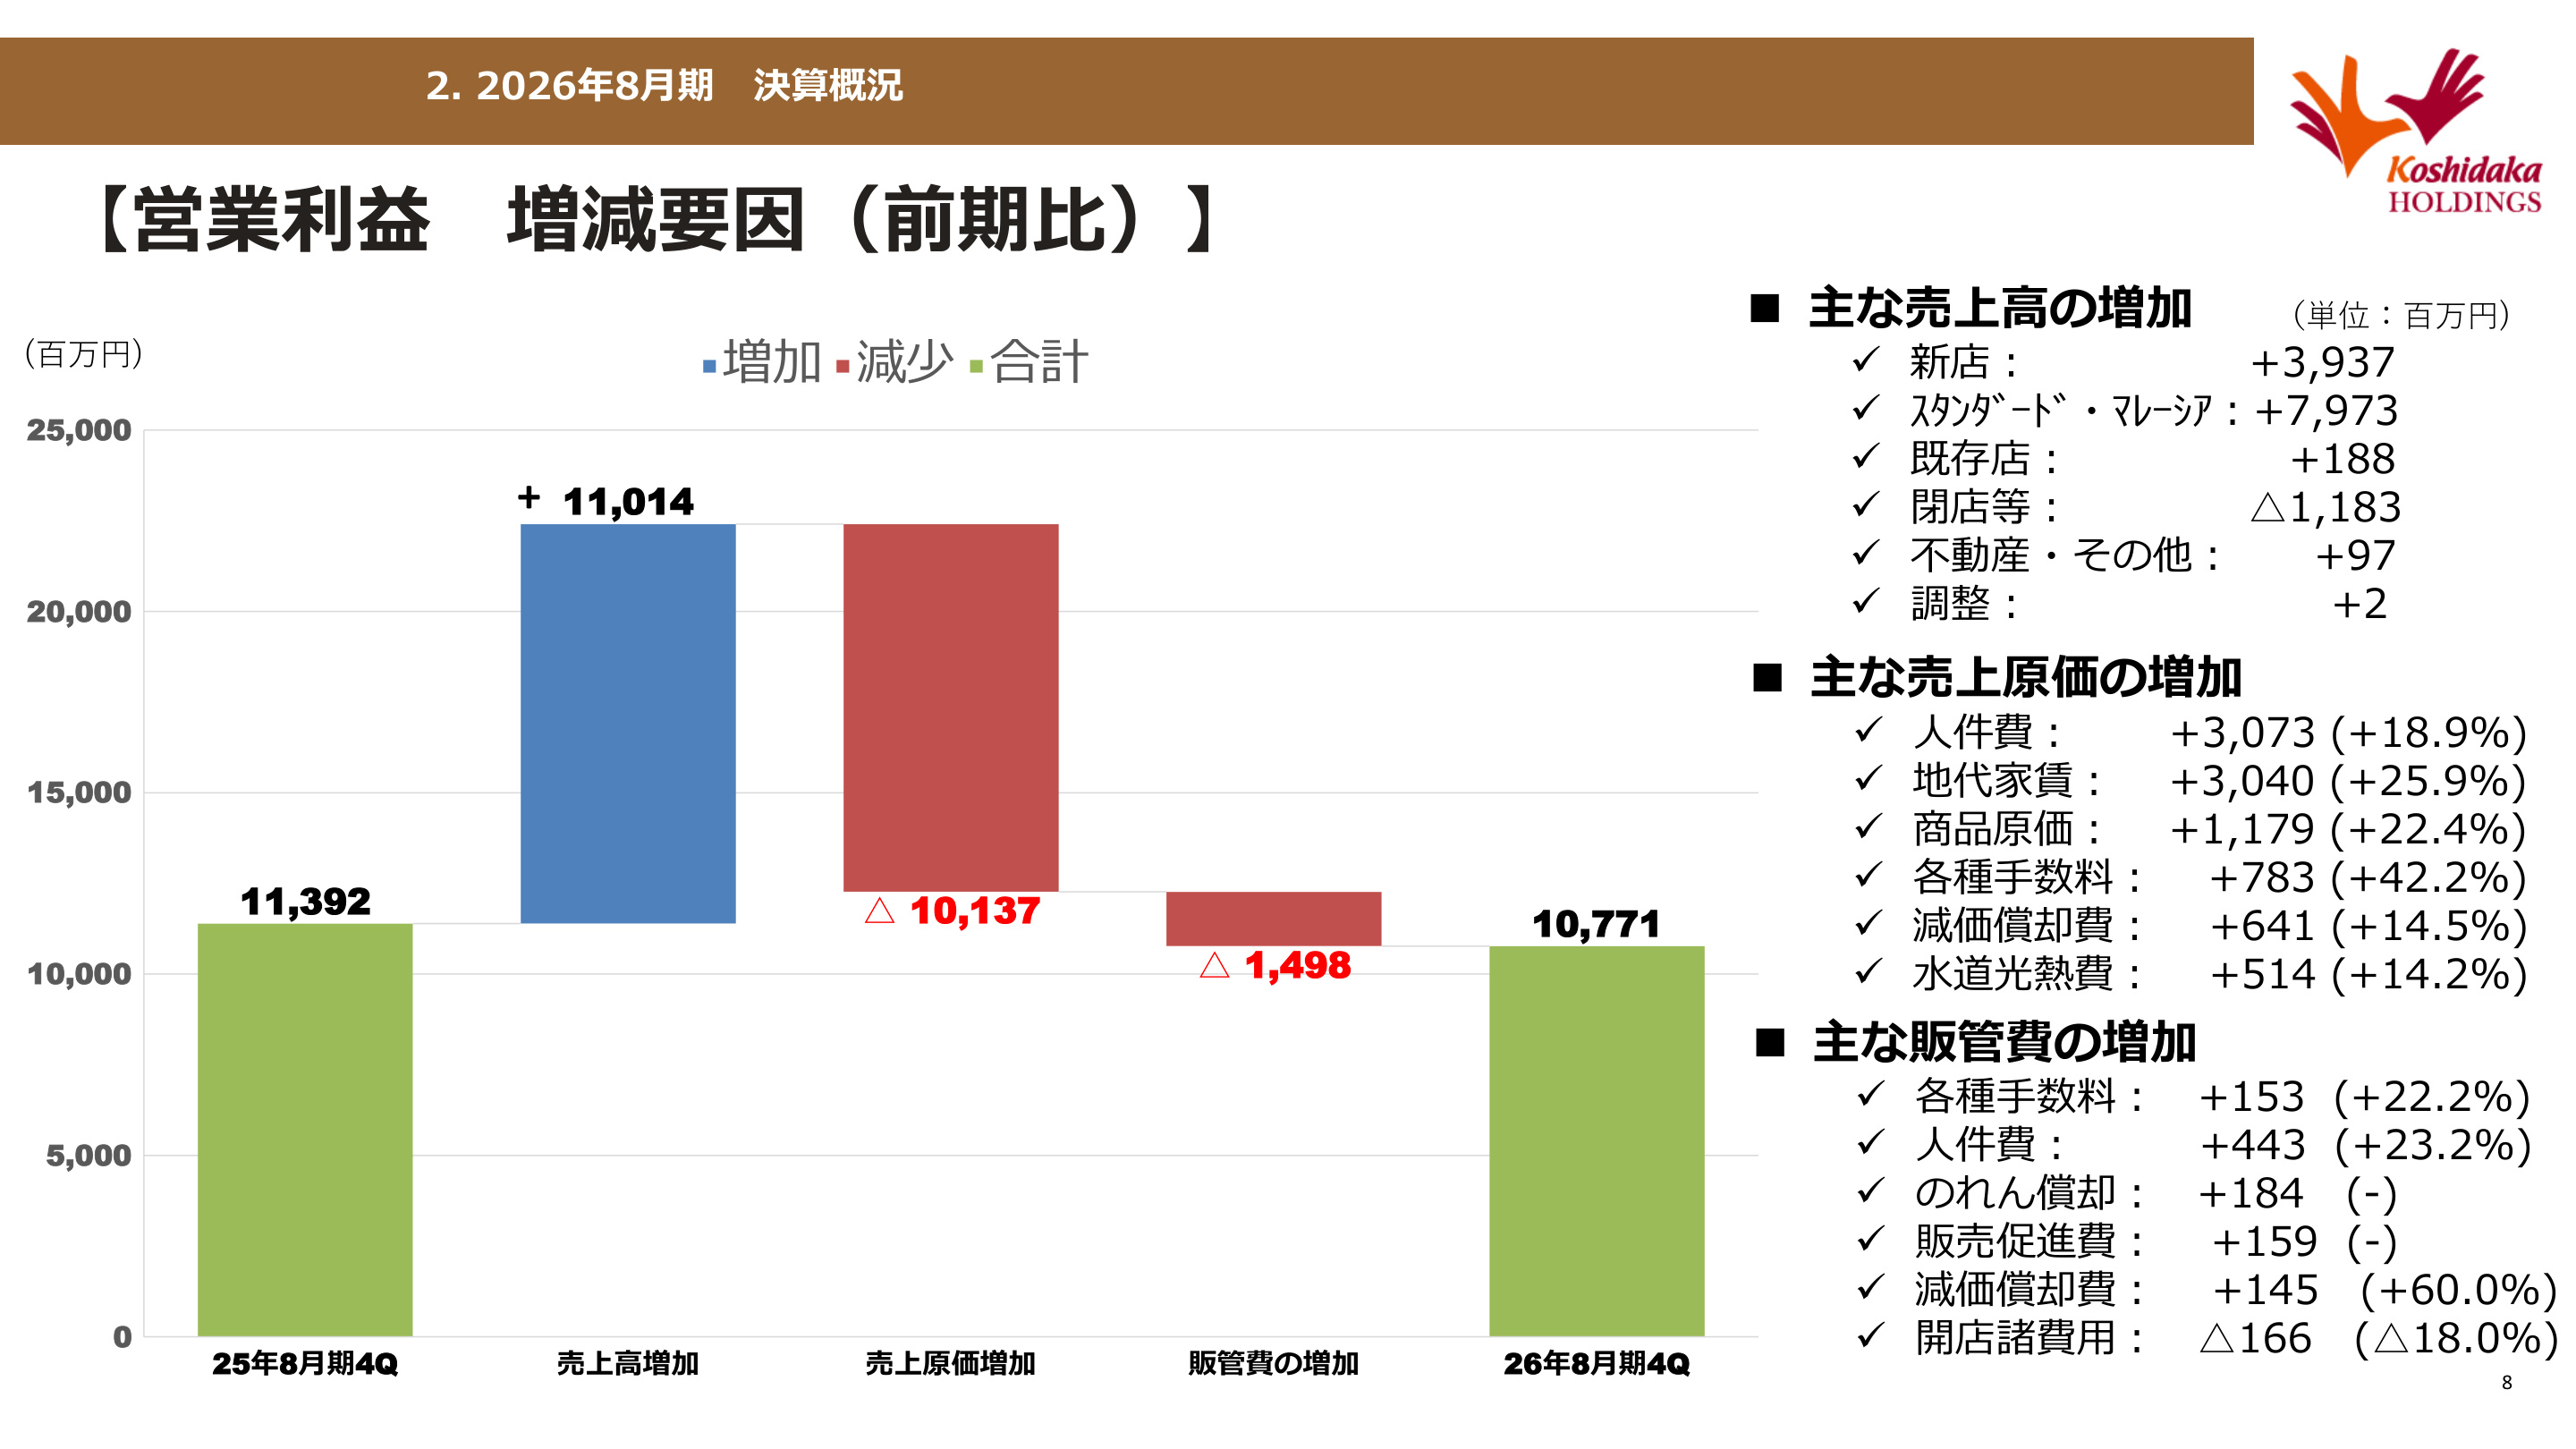
Breaking down the factors behind the change in operating profit from the previous fiscal year (a decrease of 621 million yen from 11.392 billion yen to 10.771 billion yen) clarifies the composition of top-line growth and rapid cost-push factors.
Changes in Cost Structure and Impact on Profitability
The slide above is an important page that visualizes the increase and decrease in operating profit using a waterfall chart and discloses in detail the factors behind the increases in gross profit and SG&A expenses.
- Increase in Net Sales (+11.014 billion yen) : External growth and new investments accounted for the majority of growth, with contributions of +3.937 billion yen from new store openings and +7.973 billion yen from the consolidation of Standard Corp. and the Malaysian subsidiary. Existing store sales increased by +188 million yen, while the closure of unprofitable stores resulted in a decrease of 1.183 billion yen.
- Increase in Cost of Sales (△10.137 billion yen) : The rise in core costs was significant, with labor costs increasing by 3.073 billion yen (+18.9%) , rent increasing by 3.040 billion yen (+25.9%) , and merchandise costs increasing by 1.179 billion yen (+22.4%) . In addition to the cost increase associated with taking over the Standard Corp. store network, upward pressure on unit prices weighed on earnings.
- Increase in SG&A Expenses (△1.498 billion yen) : In addition to a 443 million yen (+23.2%) increase in labor costs, goodwill amortization of 184 million yen was incurred due to the acquisition of Standard Corp. Furthermore, sales promotion expenses increased by 159 million yen, and depreciation increased by 145 million yen (+60.0%) due to marketing and system development.
3. Segment Trends and Business Structural Reform
① Karaoke Business
- Net Sales : 78.076 billion yen (+16.3% YoY)
- Operating Profit : 12.030 billion yen (△3.0% YoY)
Although double-digit sales growth was achieved through new store openings and the inclusion of Standard Corp., segment operating profit decreased slightly due to rising labor and procurement costs, as well as increased temporary expenses associated with DX investments such as the introduction of a new POS register system and the **nationwide rollout of the new entertainment platform "E-bo"."
② Real Estate Management Business
- ** Net Sales **: 1.910 billion yen (+2.9% YoY)
- ** Operating Profit **: 219 million yen (△1.3% YoY)
New and existing properties such as AQL Maebashi, Shibata 2-chome Building, and MANEKI Shimbashi Building maintained a certain level of occupancy. As part of the portfolio review, the ** Atsugi Vista Hotel (Atsugi property) was sold **.
③ Other Businesses
- ** Net Sales **: 923 million yen (+5.1% YoY)
- ** Operating Profit **: △55 million yen (compared to a profit of 37 million yen in the previous fiscal year)
While the performance of restaurant businesses such as "Gindaco Highball Sakaba" remained generally solid, the company proceeded with the withdrawal from the hot spring business, and operating losses were recorded due to the initial costs of opening two new "Café ECLA" stores (Kita-Ageo and Nagaoka).
4. KPIs and Evolution of the Core Karaoke Business Store Network
Existing Store KPIs (Trade-off between Customer Traffic and Unit Price)
For the fiscal year ended August 2026, domestic existing karaoke store performance showed ** sales at 100.3% of the previous year **, maintaining the previous year's level. Looking at the breakdown, ** customer traffic was 95.3% of the previous year **, falling below the previous year due to the intense heat and amusement competition, but ** unit price increased significantly to 105.2% of the previous year ** due to the success of pricing strategies and collaboration initiatives, covering the decline in customer traffic.
Expansion of Domestic and International Store Networks
- ** Total Group Stores **: Rapidly expanded from 703 stores at the end of the previous fiscal year to ** 794 stores (+91 stores) **.
- ** Number of Rooms **: Increased from 19,052 rooms to ** 21,718 rooms (+2,666 rooms) **.
- ** New Openings and Format Conversions : In addition to the net increase in the "Manekineko" brand (38 new stores, 13 closures), 67 "JOYSOUND" stores (4 closures) from the acquired Standard Corp. were added. For these stores, the company is sequentially proceeding with name and format changes to the new brand " Karaoke GLANZA **" or "Manekineko," leveraging their prime locations in front of train stations.
Acceleration of Overseas Expansion
The number of overseas stores reached 29 (+4 stores from the end of the previous fiscal year). In particular, ** Koshidaka Malaysia was consolidated as a subsidiary starting this fiscal year **, recording 1.139 billion yen in sales and 69 million yen in operating profit, maintaining a profitable trend. Stores in Indonesia and Thailand are also becoming profitable at the store level, and preparations for the first store openings in the United States and the Philippines are underway.
5. Financial Position and Cash Flow Status
- ** Financial Position **: Total assets increased by 10.394 billion yen from the end of the previous fiscal year to ** 78.982 billion yen **. The main reason was an increase in fixed assets to 65.257 billion yen (+12.460 billion yen) due to the acquisition of Standard Corp. and aggressive store openings. Net assets expanded to 42.506 billion yen (+7.401 billion yen) due to the completion of the stock conversion of unsecured convertible bond-type bonds with stock acquisition rights and the accumulation of retained earnings. Accordingly, the ** equity ratio rose 2.6pt from 51.2% at the end of the previous fiscal year to 53.8% **, confirming the strengthening of the financial base.
- ** Cash Flow Trends **: Although cash flows from operating activities secured a ** cash inflow of 10.626 billion yen **, cash flows from investing activities resulted in a ** cash outflow of 12.564 billion yen ** due to acquisition costs and store investments, resulting in a free cash flow of ** △1.938 billion yen **. Adding financing activities such as repayment of borrowings (△2.207 billion yen), the ending balance of cash and cash equivalents is 6.466 billion yen.
6. Full-Year Earnings Forecast and Growth Strategy for the Fiscal Year Ending August 2027
KOSHIDAKA HOLDINGS Co.,LTD. expects significant increases in both sales and profits for the fiscal year ending August 2027 through the creation of synergies from large-scale M&A and the streamlining of existing businesses.
Key Points of the Next Fiscal Year's Plan and Growth Drivers
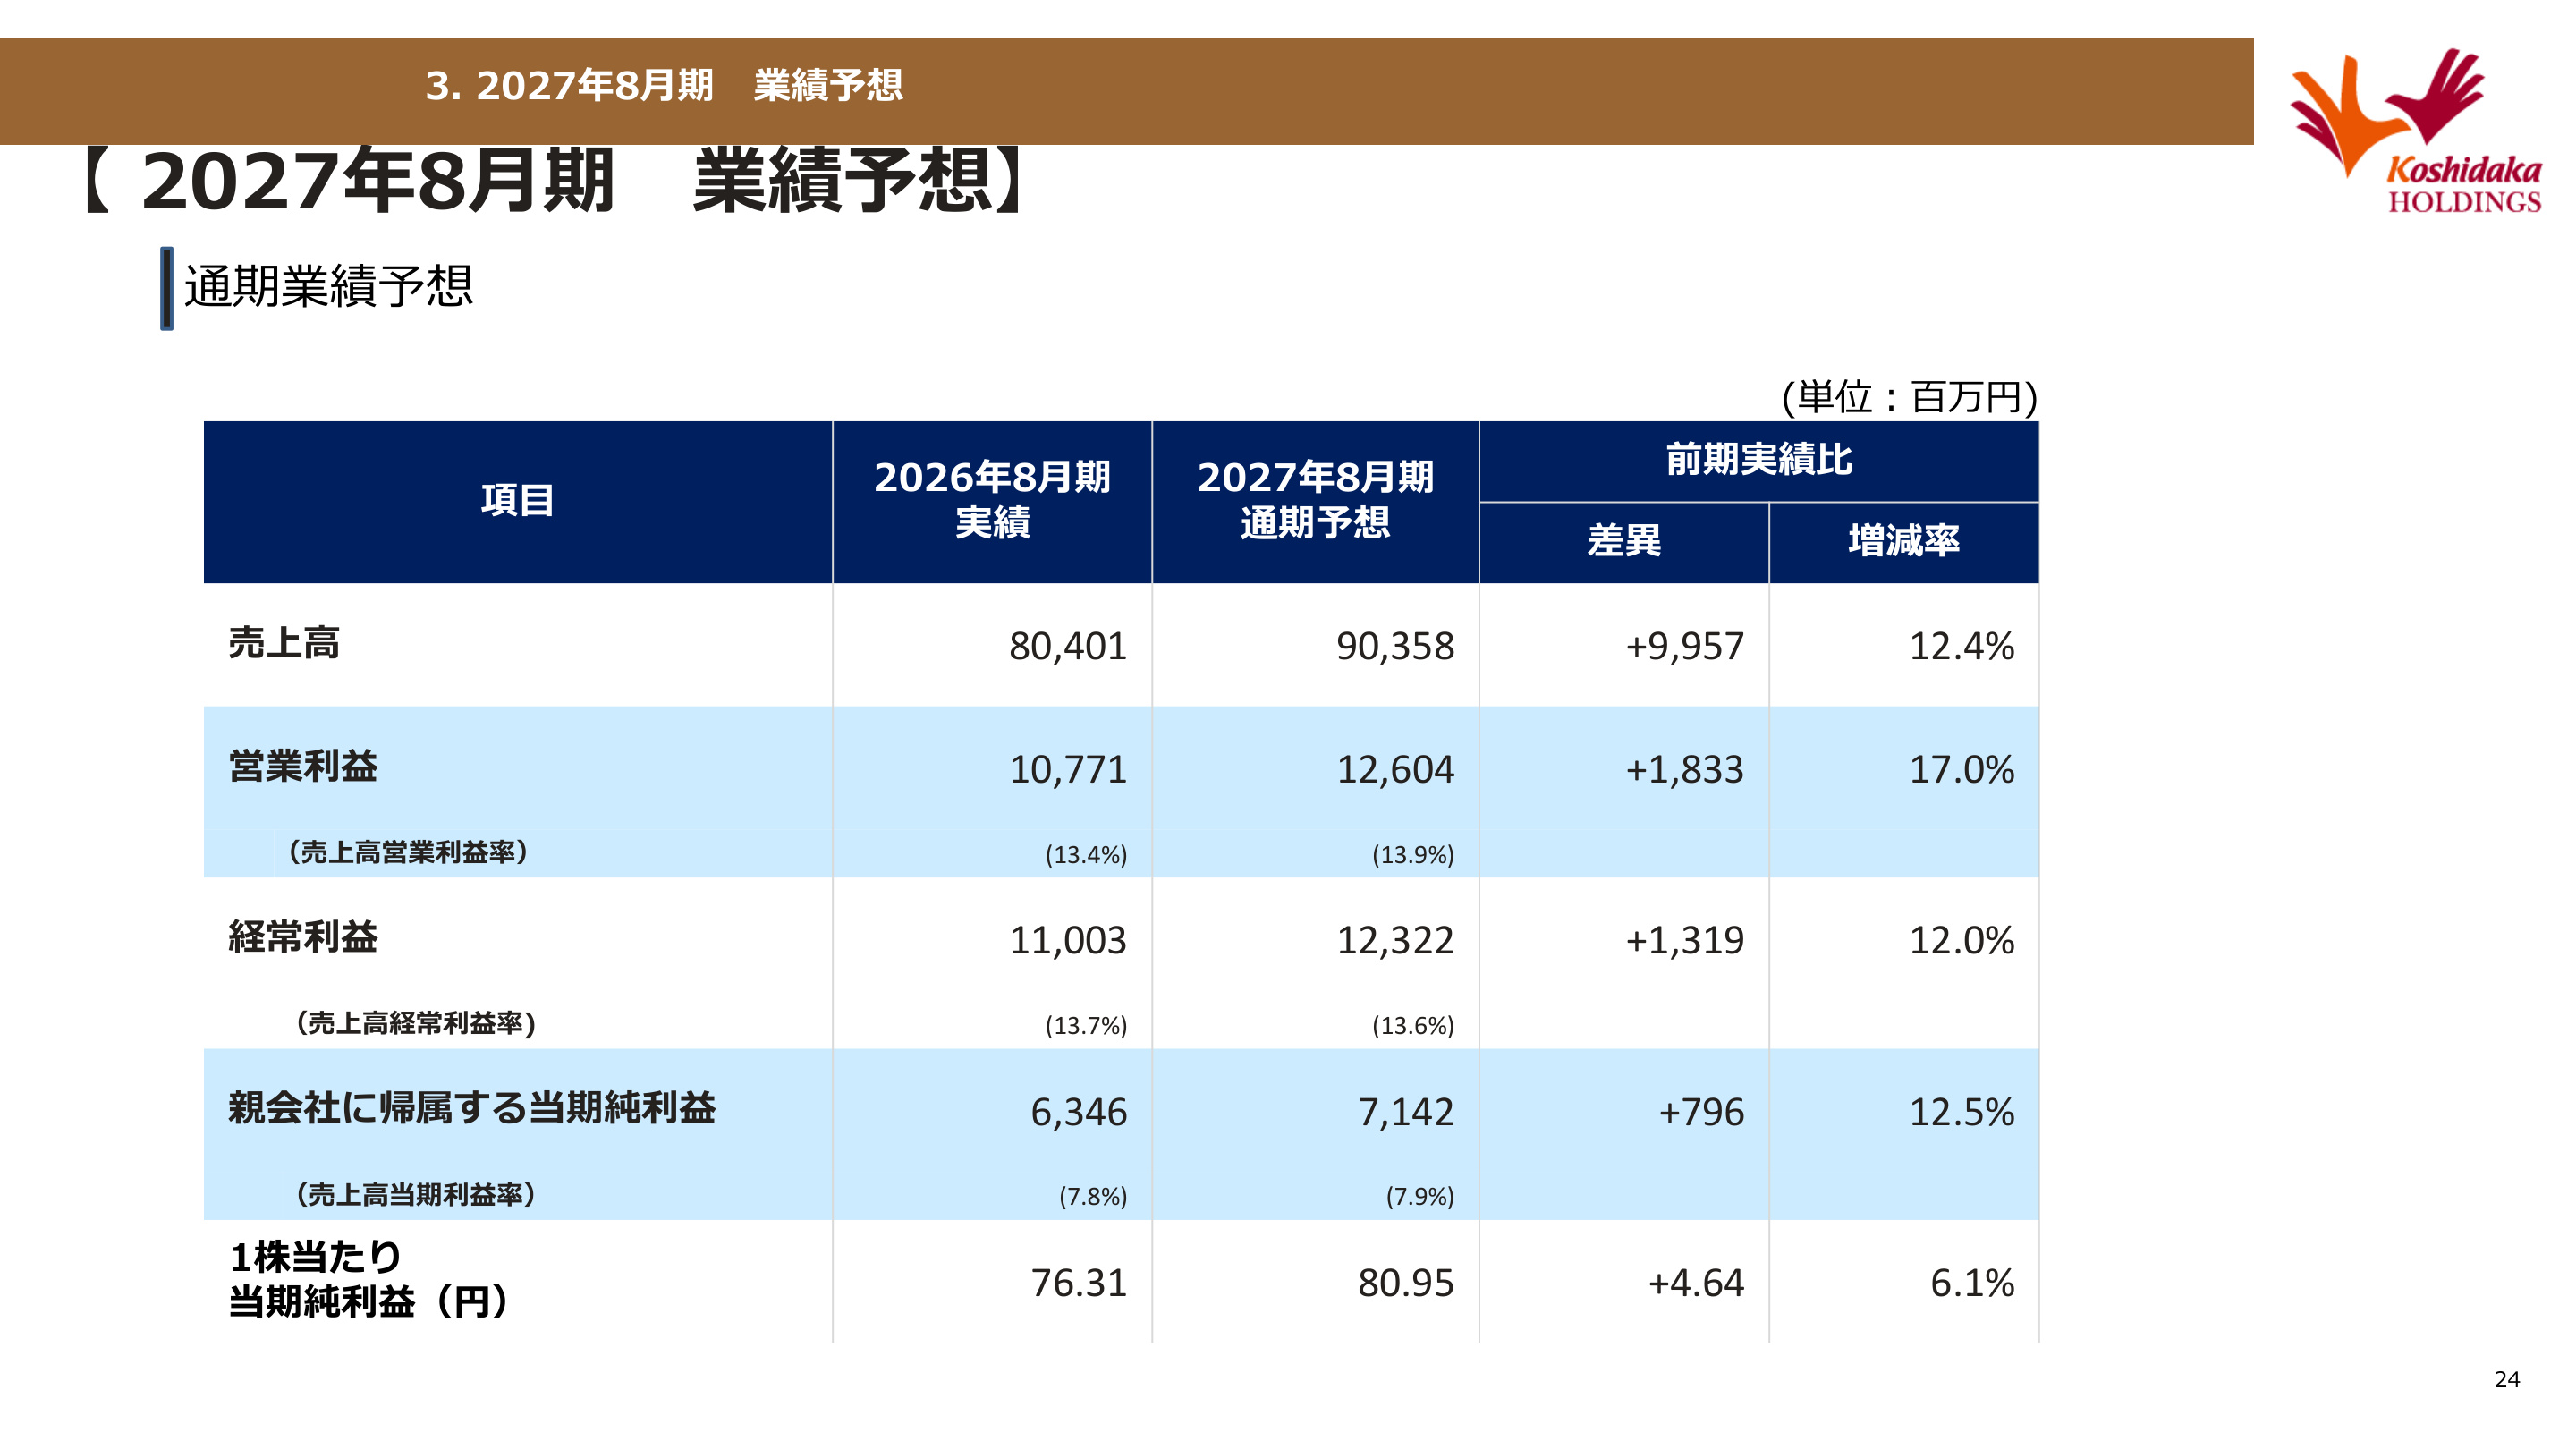
The slide above summarizes the full-year consolidated earnings forecast for the fiscal year ending August 2027. The plan is to update record-high levels for both net sales and profits at each stage.
- ** Full-Year Forecast Net Sales **: ** 90.358 billion yen (+12.4% YoY) **
- ** Full-Year Forecast Operating Profit **: ** 12.604 billion yen (+17.0% YoY) **
- ** Full-Year Forecast Ordinary Profit **: ** 12.322 billion yen (+12.0% YoY) **
- ** Full-Year Forecast Profit Attributable to Owners of Parent **: ** 7.142 billion yen (+12.5% YoY) **
- ** Earnings Per Share (Forecast) **: 80.95 yen
Specific Growth Strategies
- ** Continued Growth of the Karaoke Business **: The karaoke segment expects net sales of 87.229 billion yen (+9.153 billion yen) and segment operating profit of 13.239 billion yen (+1.209 billion yen). Domestic existing store sales are expected to be 105% of the previous year, with the full contribution of the 38 stores opened in the previous fiscal year and the effect of new stores in the next fiscal year added.
- ** Profitability Improvement of Standard Corp. **: Standard Corp. alone expects net sales of 8.8 billion yen and operating profit after goodwill amortization of 160 million yen. The company will fully implement cost ratio reductions through the consolidation of common food and drink procurement, rent negotiations, and improved productivity in store operations.
- ** Expansion of Overseas Business **: Koshidaka Malaysia expects net sales of 1.4 billion yen and operating profit of 230 million yen, increasing the profit contribution of the Southeast Asian business.
- ** Profitability of Real Estate and Other Businesses **: In addition to raising operating profit of the real estate management business to 393 million yen (+174 million yen) through the progress of leasing newly acquired properties, the company plans to turn other businesses profitable with an operating profit of 102 million yen through the new opening of "NeCoLabo Café" and the monetization of Café ECLA.
7. Shareholder Return Policy (Dividend Increase Trend and Expansion of Benefits)
- ** Dividend Policy **: The annual dividend for the fiscal year ended August 2026 was ** 28 yen per share (a 4 yen increase from the previous fiscal year) **, achieving ** 5 consecutive years of dividend increases **. For the following fiscal year ending August 2027, the company plans an ** annual dividend of 30 yen (a 2 yen increase from the previous fiscal year, with a payout ratio of 37.1%) **, consisting of 15 yen at the interim and 15 yen at the year-end, aiming for ** 6 consecutive years of dividend increases **.
- ** Expansion of Shareholder Benefit System : From the record date of August 31, 2026, the issuance frequency of benefit coupons was changed from once a year to ** twice a year (end of February and end of August), and the validity period was set to 6 months to improve convenience and promote usage. Furthermore, in addition to the conventional "Manekineko" and "Wankara," the usable stores were significantly expanded to include the acquired "Karaoke Shop JOYSOUND," the new format "GLANZA," "CAFÉ ECLA," and "Shabu-shabu Sukiyaki Dining Tenku."
Summary
The fiscal year ended August 2026 for KOSHIDAKA HOLDINGS Co.,LTD. was a "year of business base expansion" in which the company completed the group integration of Standard Corp. and DX infrastructure investment, despite being pressured by rising raw material and labor costs. In the fiscal year ending August 2027, the company is expected to proceed with business development with an eye toward achieving 90 billion yen in net sales and 12.6 billion yen in operating profit through the demonstration of scale merits in the expanded store network (approximately 800 stores) and the realization of procurement consolidation and cost reduction synergies.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.