

SHIKIGAKU.Co.,Ltd. FY2027/2 Q2 Earnings Deep Dive: Growth Strategy Through Business Portfolio Restructuring and "Long-term Holding M&A"
Sentiment Analysis
SHIKIGAKU.Co.,Ltd.'s FY2027/2 Q2 earnings reflect a period of transition, characterized by the absence of large-scale investment exit gains recorded in the same period of the previous year, a review of the business portfolio, and the emergence of upfront costs associated with the full-scale launch of its "long-term holding M&A" strategy, which is intended to become a new pillar of revenue. This report provides a detailed analysis of the consolidated profit and loss, segment-specific trends, changes in financial position, and the multi-layered growth model the company is pursuing for the medium to long term.
1. FY2027/2 Q2 Earnings Highlights and Analysis of Profit Structure
For the cumulative second quarter of the current fiscal year (hereinafter "first half"), the company reported net sales of 2.662 billion yen (down 27.6% year-on-year) , an operating loss of 156 million yen (compared to an operating profit of 840 million yen in the same period last year) , an ordinary loss of 146 million yen (compared to an ordinary profit of 857 million yen in the same period last year) , and a net loss attributable to owners of the parent of 46 million yen (compared to a net profit of 445 million yen in the same period last year) .
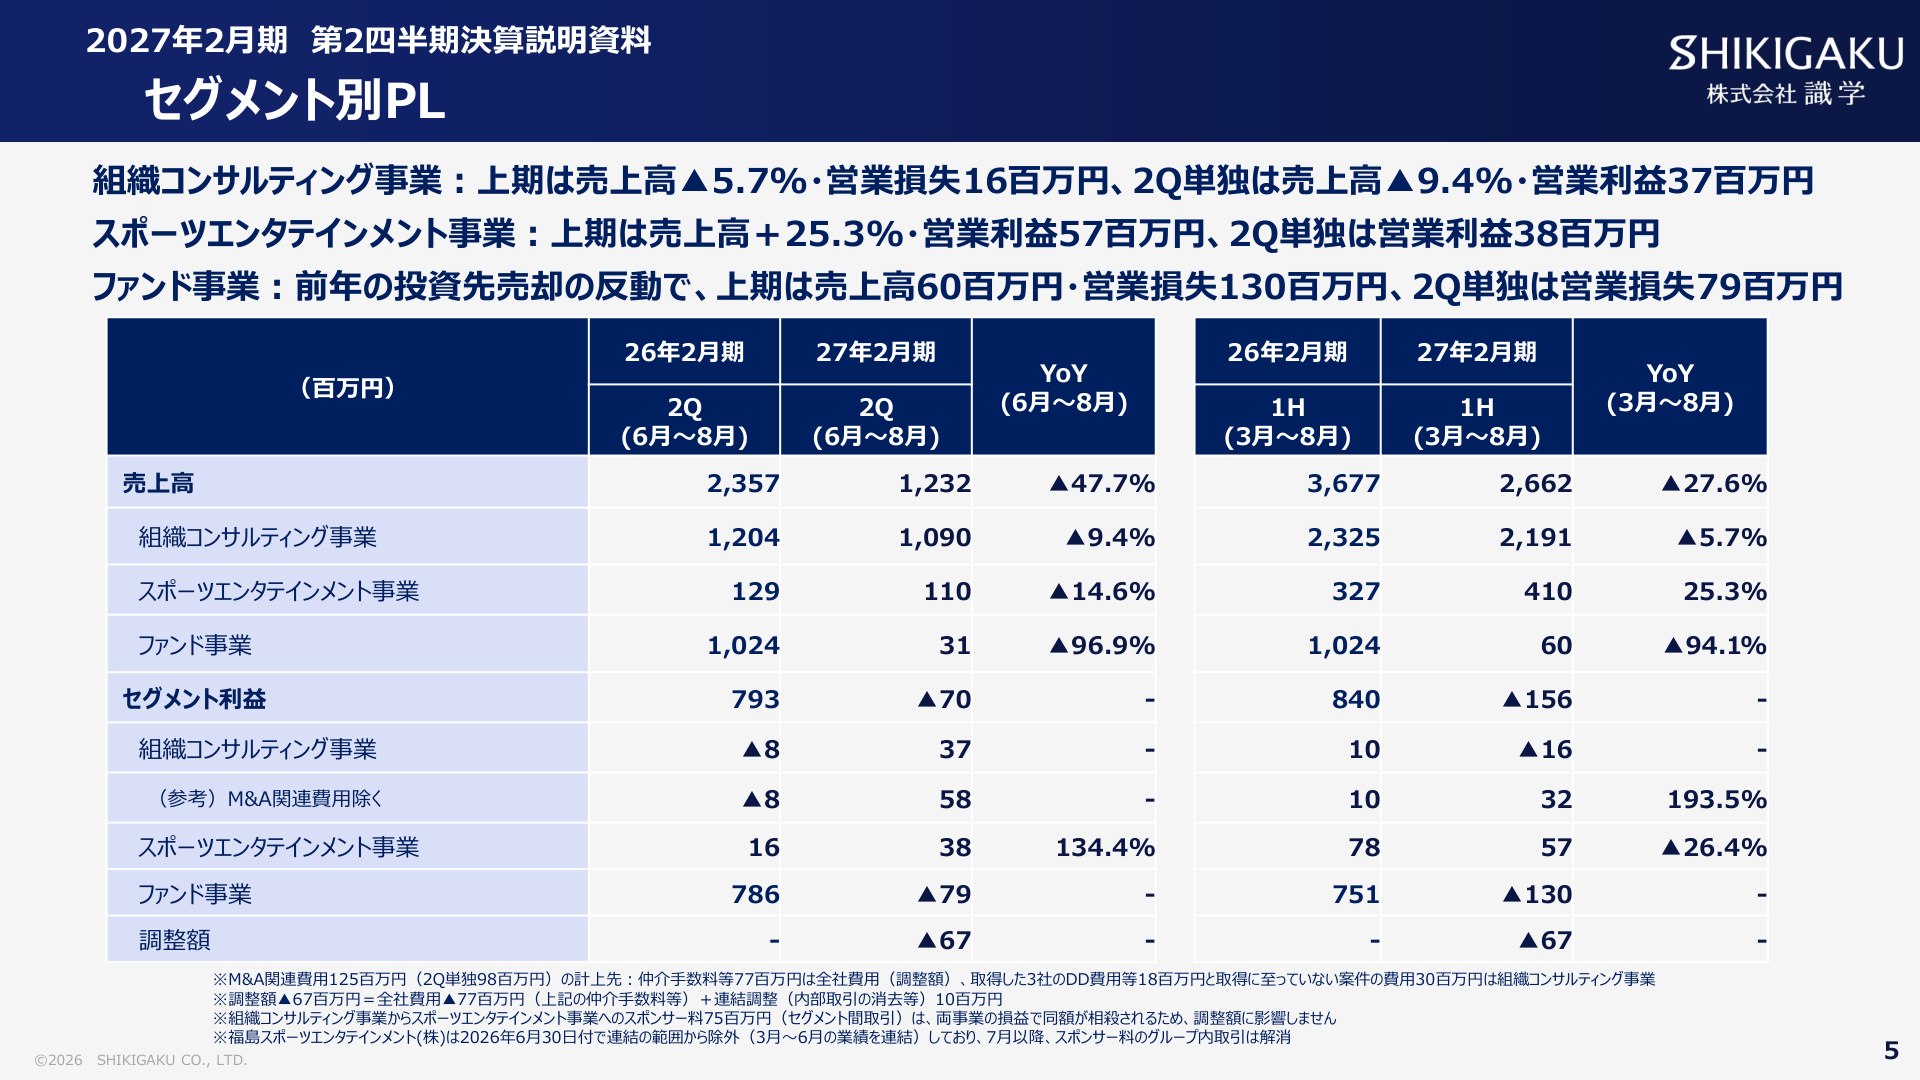
The slide above shows the consolidated statement of income, illustrating the performance trends for the current period and progress against the full-year forecast. The primary factors behind the significant decline in revenue and the shift to an operating loss are the reversal (loss) of 1.024 billion yen in net sales associated with the sale of an investment asset in the fund business during the same period of the previous year (FY26/2 Q2) . Net sales in the fund business decreased significantly from 1.024 billion yen in the same period last year to 60 million yen.
On the other hand, focusing on the second quarter (June to August) alone, net sales were 1.232 billion yen and the operating loss was 70 million yen. However, it is important to note the occurrence of M&A-related expenses (125 million yen for the first half, 98 million yen for Q2 alone) . These M&A-related expenses consist of brokerage fees and due diligence costs, and efforts are underway to improve profitability on a real basis, excluding these one-time costs. The company has disclosed a full-year forecast of a 50 million yen net loss attributable to owners of the parent and a full-year forecast of a 200 million yen operating loss , with the first-half progress rate against the full-year sales plan standing at 42.9% .
2. Segment Trends: Core Consulting and Business Restructuring
The performance and business status of each segment are as follows:
① Organization Consulting Business
Net sales for the core organization consulting business in the first half were 2.191 billion yen (down 5.7% year-on-year) , and the segment loss was 16 million yen (compared to a profit of 10 million yen in the same period last year) . This was impacted by sluggish growth in new client acquisition for management consulting and a decrease in the number of contracts for platform services. However, segment profit excluding M&A-related expenses (48 million yen) was 32 million yen (up 193.5% year-on-year) , and the segment secured a profit of 58 million yen in the second quarter alone when excluding these expenses.
- Consultant Metrics : While the number of consultants increased from 58 in the same period last year to 64 , monthly sales per consultant were 4.26 million yen/month (compared to 5.13 million yen/month in the same period last year) . The order backlog stood at 635 million yen (down 9.2% year-on-year) .
- Platform Services : The number of contracted companies was 1,029 , showing a gradual downward trend due to stagnation in new acquisitions.
- Management Consulting Orders : Orders for the second quarter totaled 562 million yen , with 529 million yen from small and medium-sized enterprises and 33 million yen from large enterprises (500 or more employees or listed companies).
② Exclusion of Sports Entertainment Business from Consolidation
The sports entertainment business, which operates a professional basketball team, achieved revenue growth with first-half net sales of 410 million yen (up 25.3% year-on-year) and a segment profit of 57 million yen (compared to 78 million yen in the same period last year) . Although the business maintained strong performance, with average attendance doubling to 4,239, it was excluded from consolidated subsidiaries as of June 30, 2026 , and transitioned to an equity-method affiliate. Consequently, from the third quarter onwards, it will no longer be consolidated in net sales and will be reflected as equity-method investment profit or loss.
③ Fund Business Status
Net sales for the fund business in the first half were 60 million yen , and the segment loss was 130 million yen . This includes a 30 million yen impairment loss on operational investment securities (VC fund). Efforts continue toward investment recovery (EXIT) through IPOs or M&A of existing portfolio companies in the Shikigaku No. 1 and No. 2 funds, the Emerging Startup Fund, and the New Shikigaku Fund.
3. Launch of "Long-term Holding M&A" Strategy and Multi-layered Growth Model
SHIKIGAKU.Co.,Ltd. is currently undergoing a major transformation of its business model. It is shifting from its previous growth model based solely on consulting to a "self-propagating cycle" centered on the accumulated "Shikigaku know-how."
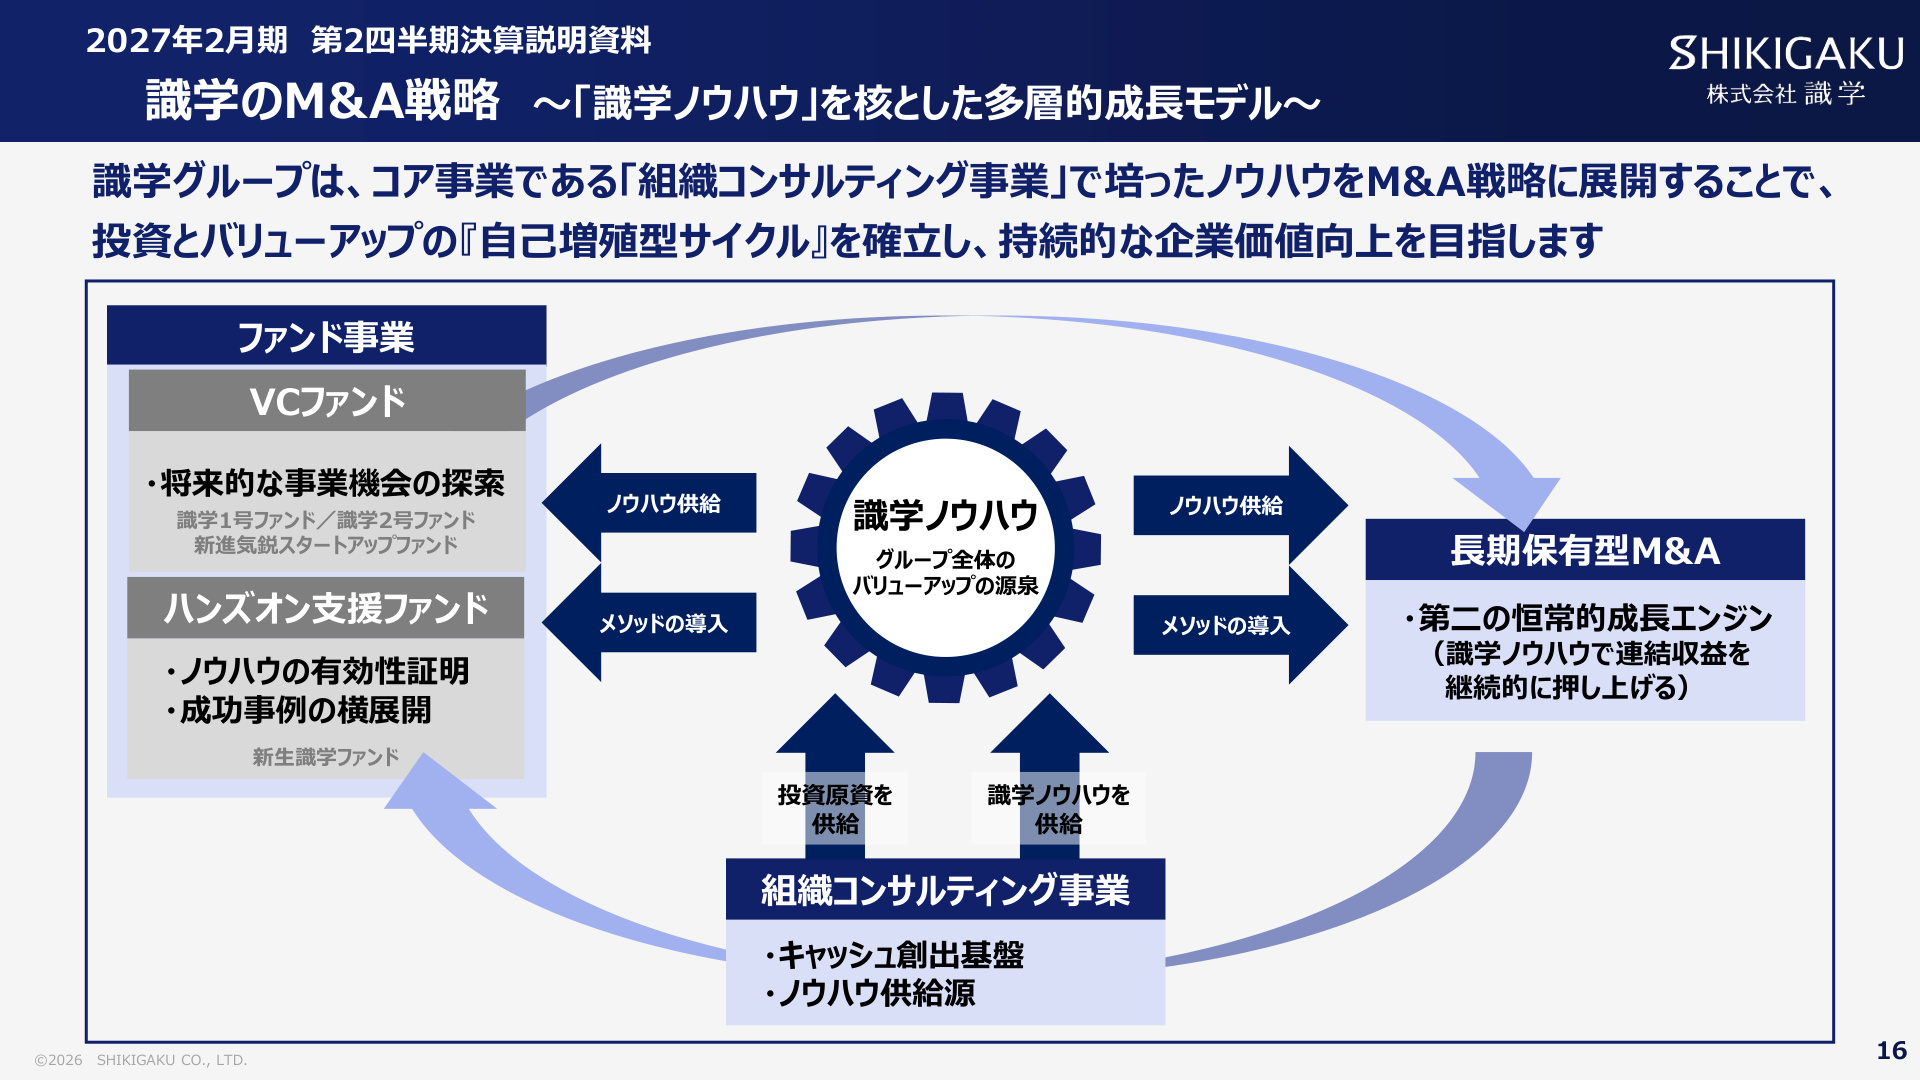
This slide shows the overall picture of the multi-layered growth model the company aims to achieve. The organization consulting business functions as a solid cash-generating foundation, and the Shikigaku method cultivated there is injected into companies acquired through "long-term holding M&A." By enhancing organizational discipline and improving productivity in acquired companies, the company aims to maximize corporate value and expand consolidated earnings on a permanent basis.
Overview of 3 Acquired Companies and Target Selection
The company focuses on "manufacturing companies that possess excellent technology, services, or products that Japan is proud of," and in the first half, it completed the 100% acquisition (subsidiary conversion) of the following three companies:
- storyteller Co., Ltd. (Acquired June 2026): Operates retail stores for handmade accessories and plans/sells collaboration goods with famous characters and companies. Operates consignment sales at 29 major commercial facilities nationwide.
- Matsuha Kiki Co., Ltd. (Acquired July 2026): Sales and maintenance of commercial fryers and edible oil filtration equipment. Its flagship product, "M-Clean," can reduce oil consumption by 30-50%, providing a stable stock revenue base through the main unit and peripheral products.
- Nexus Holdings Co., Ltd. (Acquired August 2026): Manufacturing, sales, installation, and maintenance of automotive body repair equipment (such as paint booths). The only Japanese distributor for USI paint booths.
As of the end of the second quarter, only the balance sheets of these three companies have been consolidated, and their contribution to the income statement will begin in earnest from the third quarter .
Changes in Consolidated Balance Sheet and Financial Discipline
With the acquisition of the three companies and the execution of borrowings, total consolidated assets increased by 2.684 billion yen from the end of the previous fiscal year to 7.490 billion yen . Cash and deposits were 3.069 billion yen, and goodwill of 187 million yen was recorded. Interest-bearing debt increased by 1.944 billion yen to 2.050 billion yen , net assets were 4.173 billion yen, and the equity ratio was 44.4% (a 13.0pt decrease from 57.4% at the end of the previous fiscal year). The company has established financial discipline by maintaining a certain level of equity ratio and managing repayment capacity relative to EBITDA.
4. Medium- to Long-term Growth Scenario and Management Conscious of Cost of Capital
SHIKIGAKU.Co.,Ltd. is moving away from a structure dependent on temporary fund revenue and is transitioning to a profit structure that consistently exceeds the cost of capital.
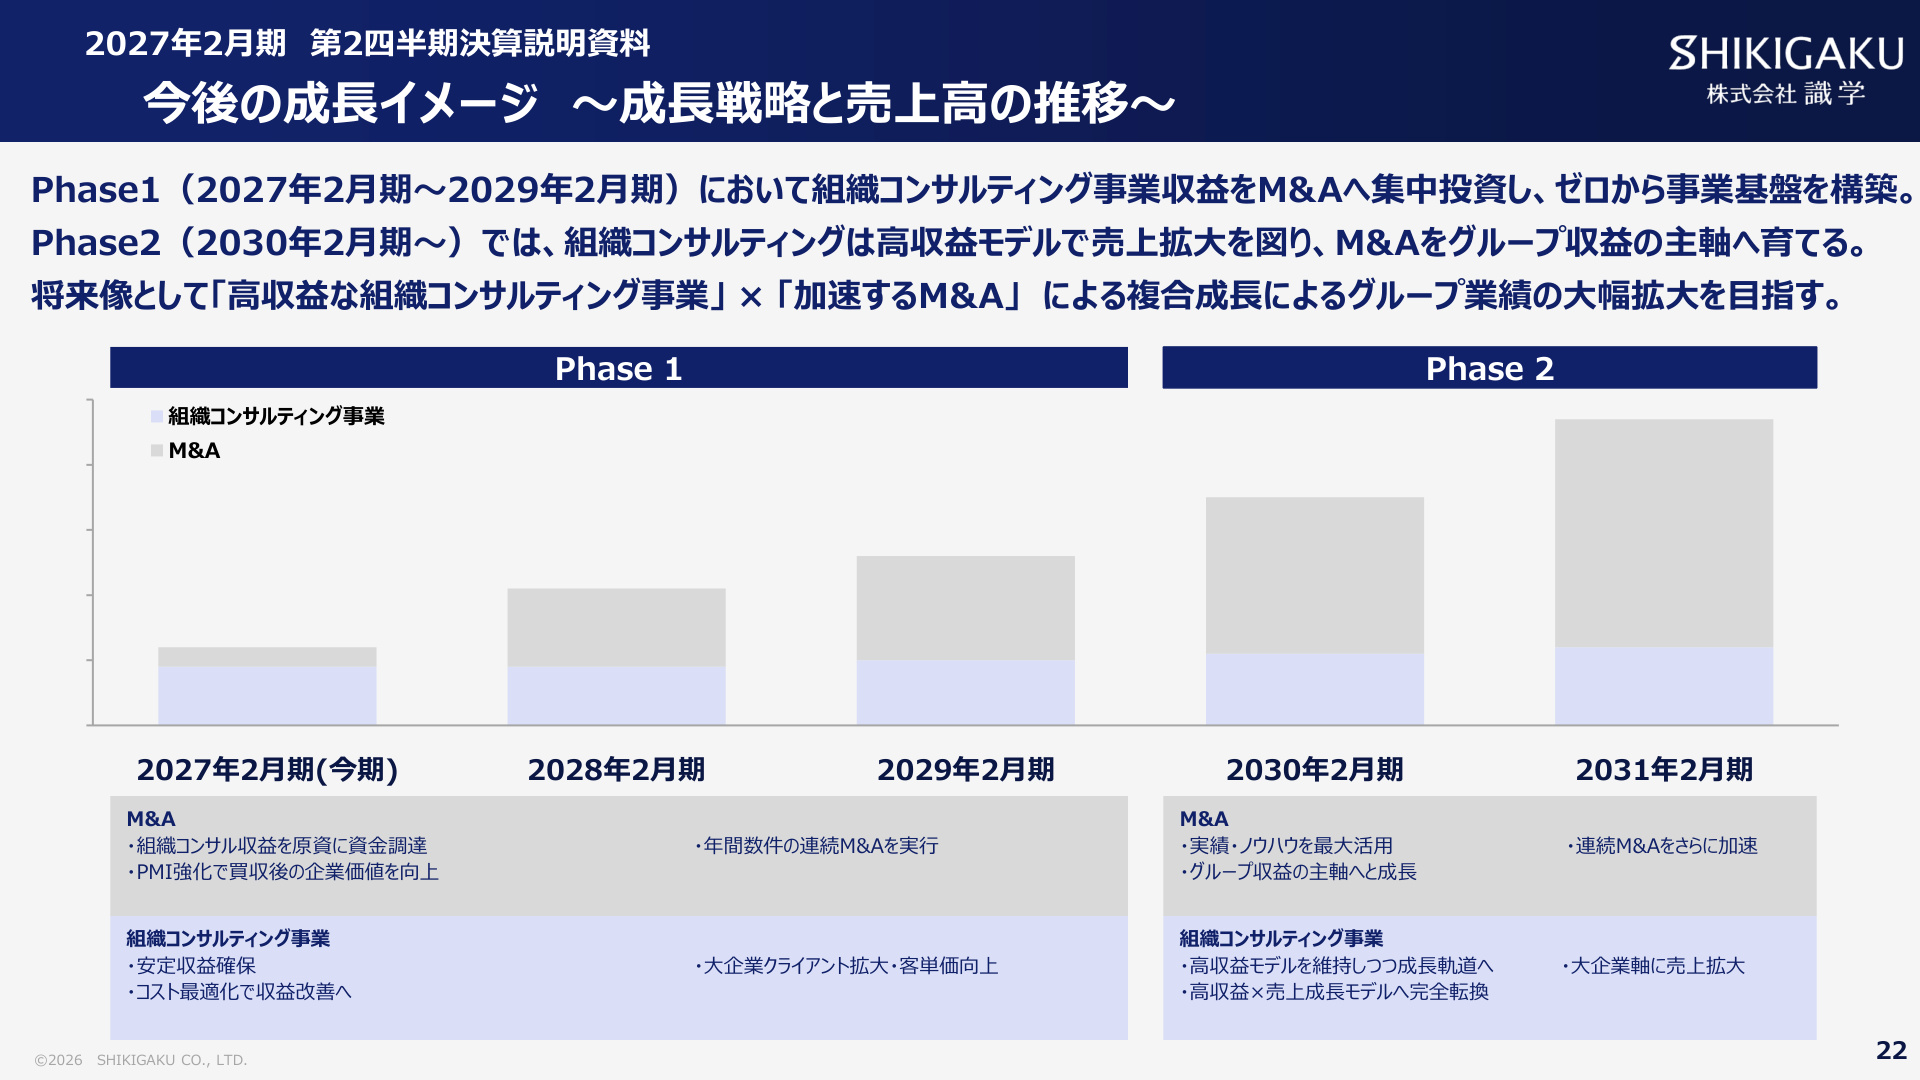
As shown in the slide above, the future growth process is divided into two main phases:
- Phase 1 (FY2027/2 to FY2029/2) : A period to concentrate profits from the organization consulting business into M&A and build a business foundation from scratch. The company will execute several consecutive M&As annually and improve corporate value through thorough PMI (Post-Merger Integration).
- Phase 2 (FY2030/2 onwards) : While transforming organization consulting into a high-profit model to drive sales growth, the company will cultivate M&A revenue as the main pillar of the entire group. It aims for complex earnings growth through "high-profit organization consulting" × "accelerating M&A."
Cost of Capital, Stock Price Awareness, and Shareholder Returns
Although the ROE for the previous fiscal year (FY26) was 11.3%, this was largely driven by gains from fund sales. The annualized ROE for the first half of the current fiscal year is approximately -3.0%, which is below the cost of shareholders' equity (CAPM estimate of 8-10%). The company's basic policy is to achieve an ROE that consistently exceeds the cost of capital by turning the organization consulting business profitable (targeting a monthly operating profit margin of 10% by the end of February 2027) and accumulating consolidated profits through long-term holding M&A.
In addition, as a shareholder return measure, the company has introduced a shareholder benefit program . It plans to present 5,000 yen worth of QUO cards (a total of 10,000 yen per year ) to shareholders who hold 200 shares (2 units) or more as of the end of February and August each year.
As described above, SHIKIGAKU.Co.,Ltd. is promoting a transition to a new growth trajectory of business diversification and scale expansion through long-term holding M&A, while simultaneously working to improve the profitability of its core business.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.