

Future Link Network Co.,Ltd. Fiscal Year Ended August 2026 Earnings Deep Dive: MRR Expansion, Structural Reform, and the Pivot Toward Profitability
Sentiment Analysis
Future Link Network Co.,Ltd. (Securities Code: 9241) reported a challenging fiscal year ended August 2026, characterized by a significant net loss. While the company saw growth in MRR (Monthly Recurring Revenue) and improved gross profit margins in its core Regional Information Distribution business, these gains were offset by a decline in hometown tax donation (Furusato Nozei) services within the Public Solutions business, a decrease in new partner contracts, and the booking of extraordinary losses. To overcome these challenges, the company is aggressively pursuing a flexible organizational restructuring through the incorporation-type company split of its hometown tax business, while concentrating management resources on its growth engines: MRR and AI-related services. This report provides a detailed analysis of the performance drivers, business structural reforms, and future growth strategies.
1. Overview of FY August 2026 Results and Background of Forecast Variance
For the fiscal year ended August 2026, consolidated net sales were 1.512 billion yen (down 2.1% YoY, 13.2% below plan), operating loss was 82 million yen (compared to a 17 million yen loss in the previous year and a 0 million yen plan), ordinary loss was 87 million yen (compared to a 20 million yen loss in the previous year and a 2 million yen loss plan), and net loss attributable to owners of the parent was 255 million yen (compared to a 28 million yen profit in the previous year and a 29 million yen profit plan).
On the revenue side, the gross profit margin improved to 66.2% (+2.2pt YoY) due to cost reductions and higher value-added services, resulting in a gross profit of 1 billion yen (up 1.3% YoY). However, the company could not absorb the increase in SG&A expenses, which rose to 1.083 billion yen (up 7.8% YoY), leading to an expanded operating loss. The primary reasons for the significant shortfall against the plan and the final net loss are as follows:
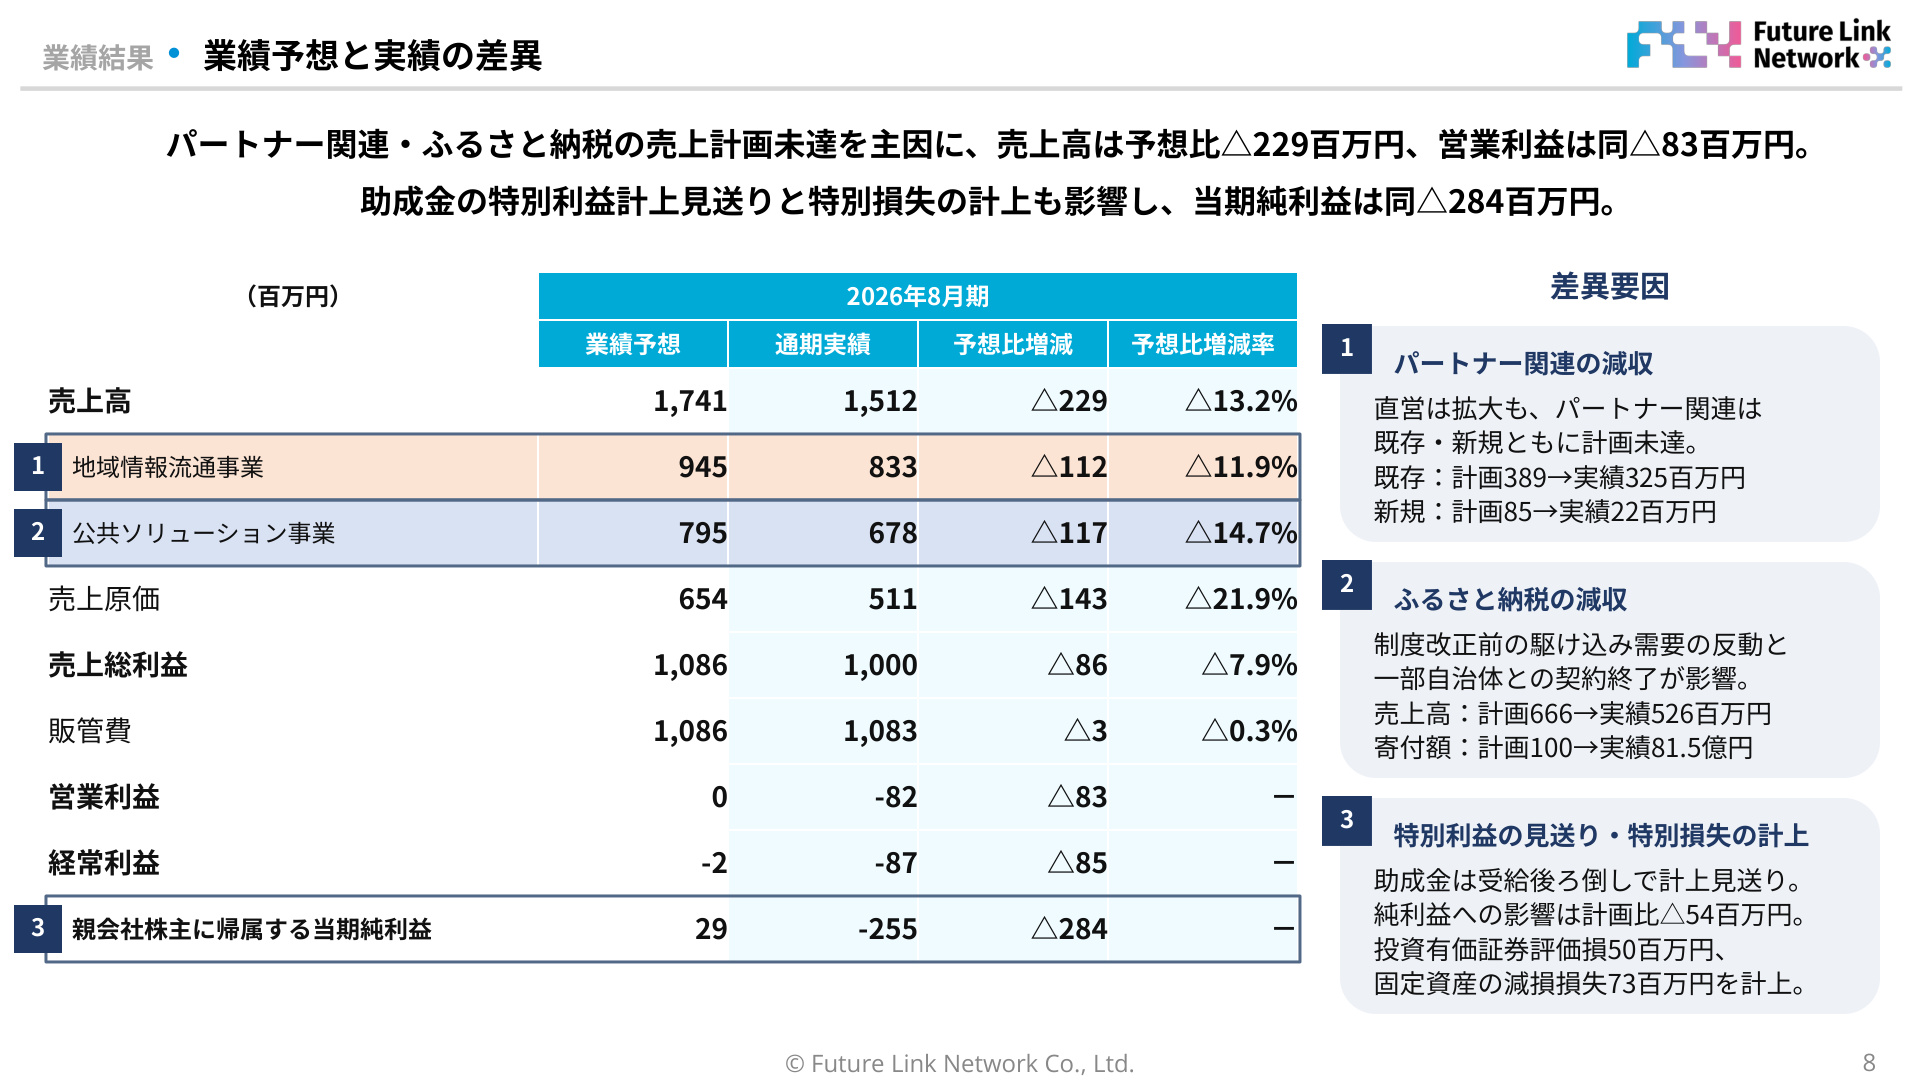
Slide Commentary (Variance between Earnings Forecast and Actual Results)
The slide above provides a detailed breakdown of the factors contributing to the variance between the initial forecast and the full-year results for the fiscal year ended August 2026. There are three key takeaways from this data:
- Revenue Decline in Partner-Related Business (Regional Information Distribution: 112 million yen below plan) While direct operations expanded successfully, partner-related sales significantly underperformed. Sales via existing partners reached 325 million yen against a plan of 389 million yen, and sales from new franchise contracts reached 22 million yen against a plan of 85 million yen. Challenges in the sales and personnel structures of partner companies hindered both new acquisitions and the expansion of existing accounts.
- Revenue Decline in Hometown Tax Business (Public Solutions: 117 million yen below plan) Hometown tax revenue stood at 526 million yen against a plan of 666 million yen. This was impacted by total donations reaching 8.15 billion yen against a plan of 10 billion yen. The decline was driven by a reactionary drop following the rush of demand prior to regulatory changes and the termination of contracts with certain municipalities.
- Deferral of Extraordinary Income and Booking of Extraordinary Losses (Net Income: 284 million yen below plan) The receipt of a human resource development subsidy (54 million yen) originally planned for the fiscal year was delayed, leading to the deferral of this extraordinary income. Furthermore, the company booked an impairment loss on investment securities of 50 million yen and an impairment loss on fixed assets of 73 million yen as extraordinary losses, significantly deepening the final net loss.
2. Segment Trends: MRR Driving Growth vs. Public Solutions at a Crossroads
The company's business is divided into two main segments: "Regional Information Distribution" and "Public Solutions." The contrasting performance of these segments defines the current fiscal year's results.
(1) Regional Information Distribution: Sales of 833 million yen (+8.7% YoY), Segment Profit of 192 million yen (+7.2% YoY)
This business, centered on the flagship "Maiple" platform, maintained growth in both sales and profit. A breakdown shows that the revenue foundation, MRR, grew steadily to 532 million yen (+8.9% YoY) . Additionally, marketing support sales reached 198 million yen (+11.9% YoY), and regional population creation sales —which include VTuber collaborations and municipal recruitment support—expanded rapidly to 80 million yen (+121.8% YoY) . The sharp decline in new partner franchise fees (other sales: 22 million yen, down 65.2% YoY) was offset by growth in direct MRR and new solutions.
Of particular note in the MRR business is the rapid growth of direct operations . Direct MRR accelerated in the second half, rising from 48 million yen in Q2 to 59 million yen in Q4 (+23.7%). Full-year direct MRR reached 207 million yen (+19.6% YoY), with direct operations accounting for approximately 78% (+33 million yen) of the total annual MRR increase (+43 million yen) .
Regarding key KPIs, the number of platform-using stores nationwide remained stable at 17,604 (up 64 stores YoY). Meanwhile, the average unit price for paid stores in directly managed areas rose significantly to 12,826 yen (+2,390 yen YoY, 112.8% of the plan) , driven by the proposal of the "Maiple-kun" AI assistant and the penetration of premium plans. Conversely, the number of operating partners decreased to 134 (down 20 YoY), and the number of contracted areas fell to 884 municipalities (down 30 YoY), highlighting the need to revitalize the partner network.
(2) Public Solutions: Sales of 678 million yen (down 12.7% YoY), Segment Profit of 140 million yen (down 36.5% YoY)
While public sector projects such as municipal DX promotion and regional point development performed well with sales of 152 million yen (exceeding the 128 million yen plan), this represented an 18.9% decline YoY. Sales in the core hometown tax business fell to 526 million yen (down 10.8% YoY). Combined with an increase in SG&A expenses, the segment suffered a significant decline in profit.
3. Group Management Strategy: Executing "Selection and Concentration" via Company Split
In light of the diverging business environments, the company implemented a bold group reorganization on October 1, 2026. It spun off its hometown tax business into a newly established, wholly-owned subsidiary, "Future Link Local Support Co., Ltd. (FLS)."
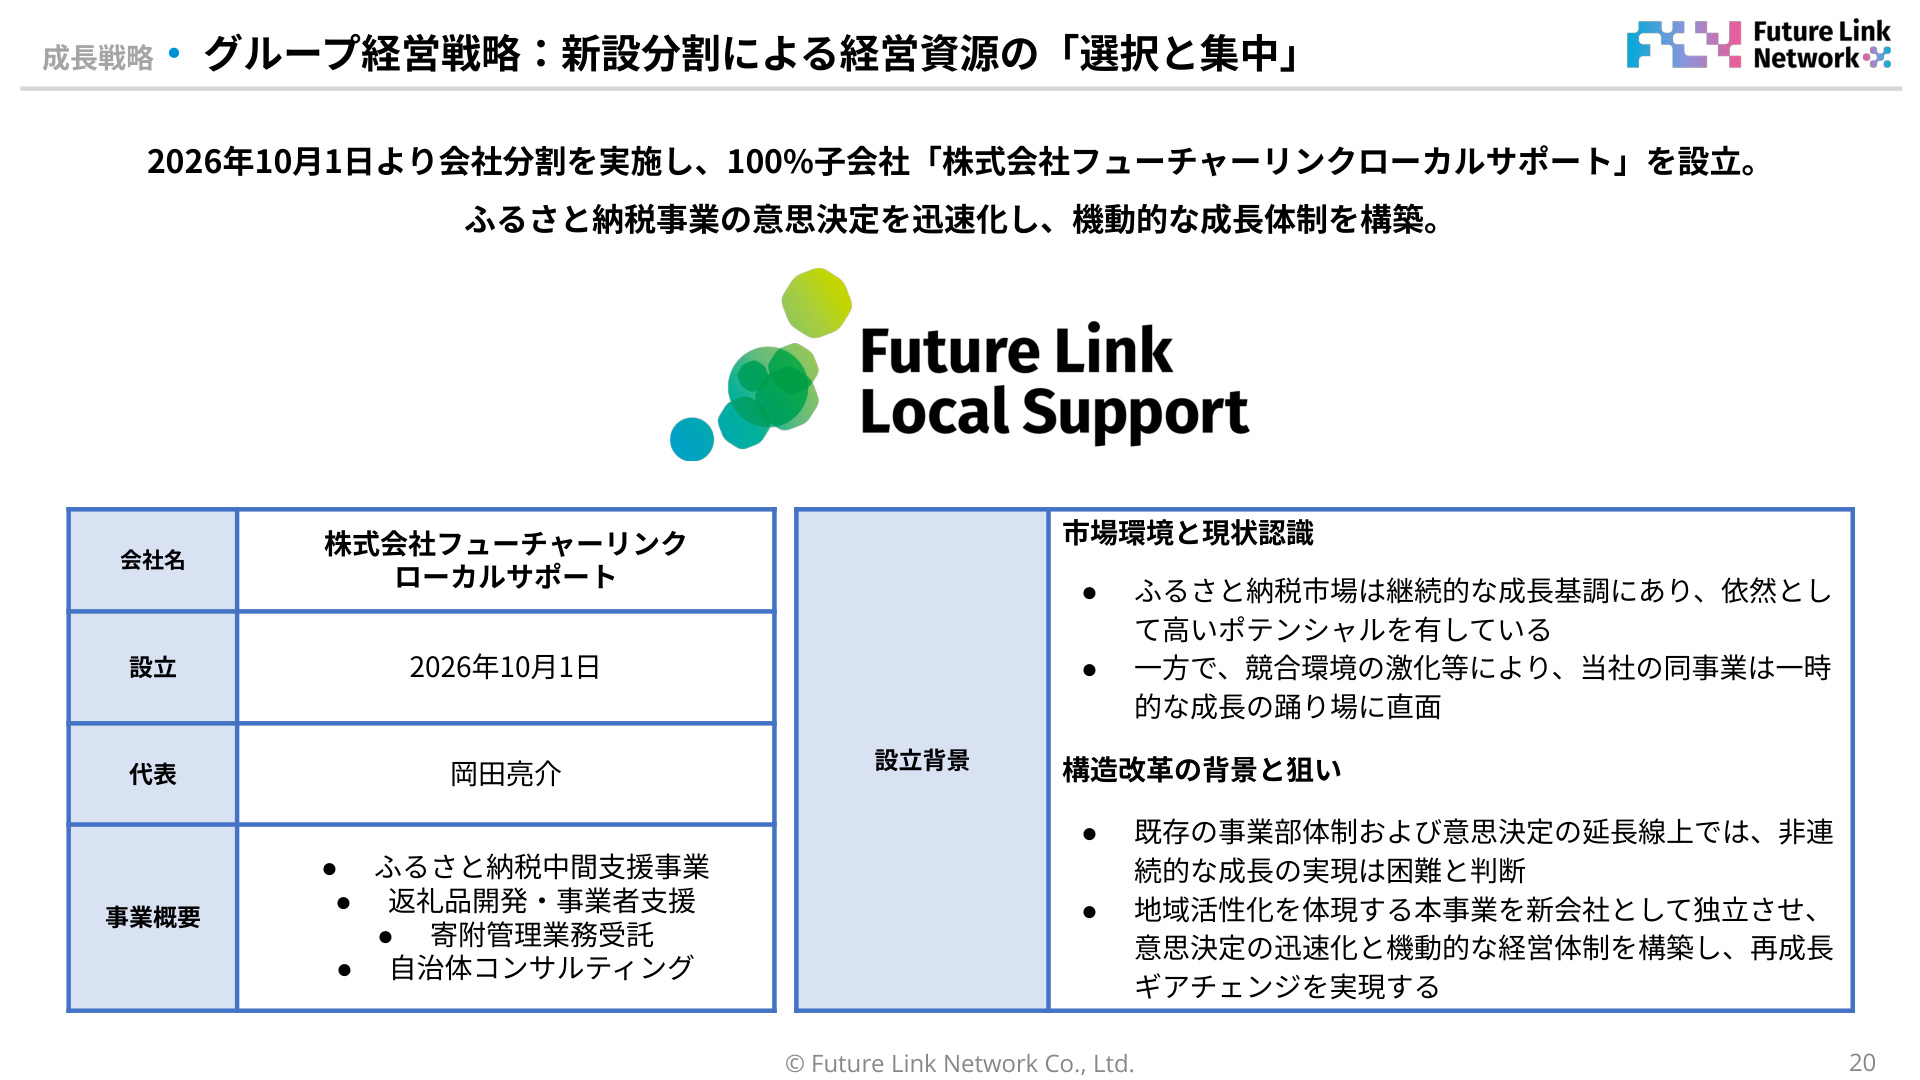
Slide Commentary (Selection and Concentration of Management Resources via Company Split)
The slide above is a strategic document outlining the objectives of this structural reform and the positioning of the new company. The importance of this measure is summarized in the following points:
- Adapting to Intensifying Competition due to Regulatory Changes Although the hometown tax market is growing, competition has intensified due to regulatory changes and the entry of new competitors, leaving the company's business at a temporary plateau. The previous divisional structure made rapid decision-making difficult, necessitating a fundamental transformation of the business model.
- Autonomous Management and Shifting Gears for Regrowth By consolidating intermediary support, gift development, donation management, and municipal consulting into FLS and establishing an independent management structure (led by Mr. Ryosuke Okada), the company will execute agile decision-making and cost structure reforms.
- Business Focus of the Parent Company (FLN) The parent company, FLN, will concentrate its resources on the Regional Information Distribution business (MRR model) centered on "Region x AI," maximizing the efficiency of capital and human resource allocation in growth areas.
4. MRR Growth Strategy: Evolution into a Local Knowledge Platform and Mid-to-Long-Term Potential
The growth strategy for the MRR business promoted by FLN is a shift from a traditional "regional information media" to a "local knowledge platform that supports the regional economy." The company is integrating its unique primary information gathered from approximately 17,000 stores nationwide, its network spanning 884 municipalities, and 26 years of operational know-how with an AI foundation.
Specific initiatives currently underway include:
- Enterprise Expansion : Leveraging direct and nationwide partner networks to horizontally deploy successful industry-specific models to multi-store operators and corporate headquarters in sectors such as housing/exterior, dentistry, and schools.
- "Maiple-kun" Development Plan : Evolving from AI-assisted news creation to proactive proposals based on history and management support utilizing regional data, thereby increasing unit prices and reducing churn rates.
- OEM and Overseas Expansion : Launching a model to provide the common system, backed by 26 years of operational experience, to regional media and advertising agencies via OEM. Internationally, the company is accelerating global expansion in Ho Chi Minh City, Vietnam, in partnership with local firm KOLLAB, surpassing 100 contracts within 3 months of launch.
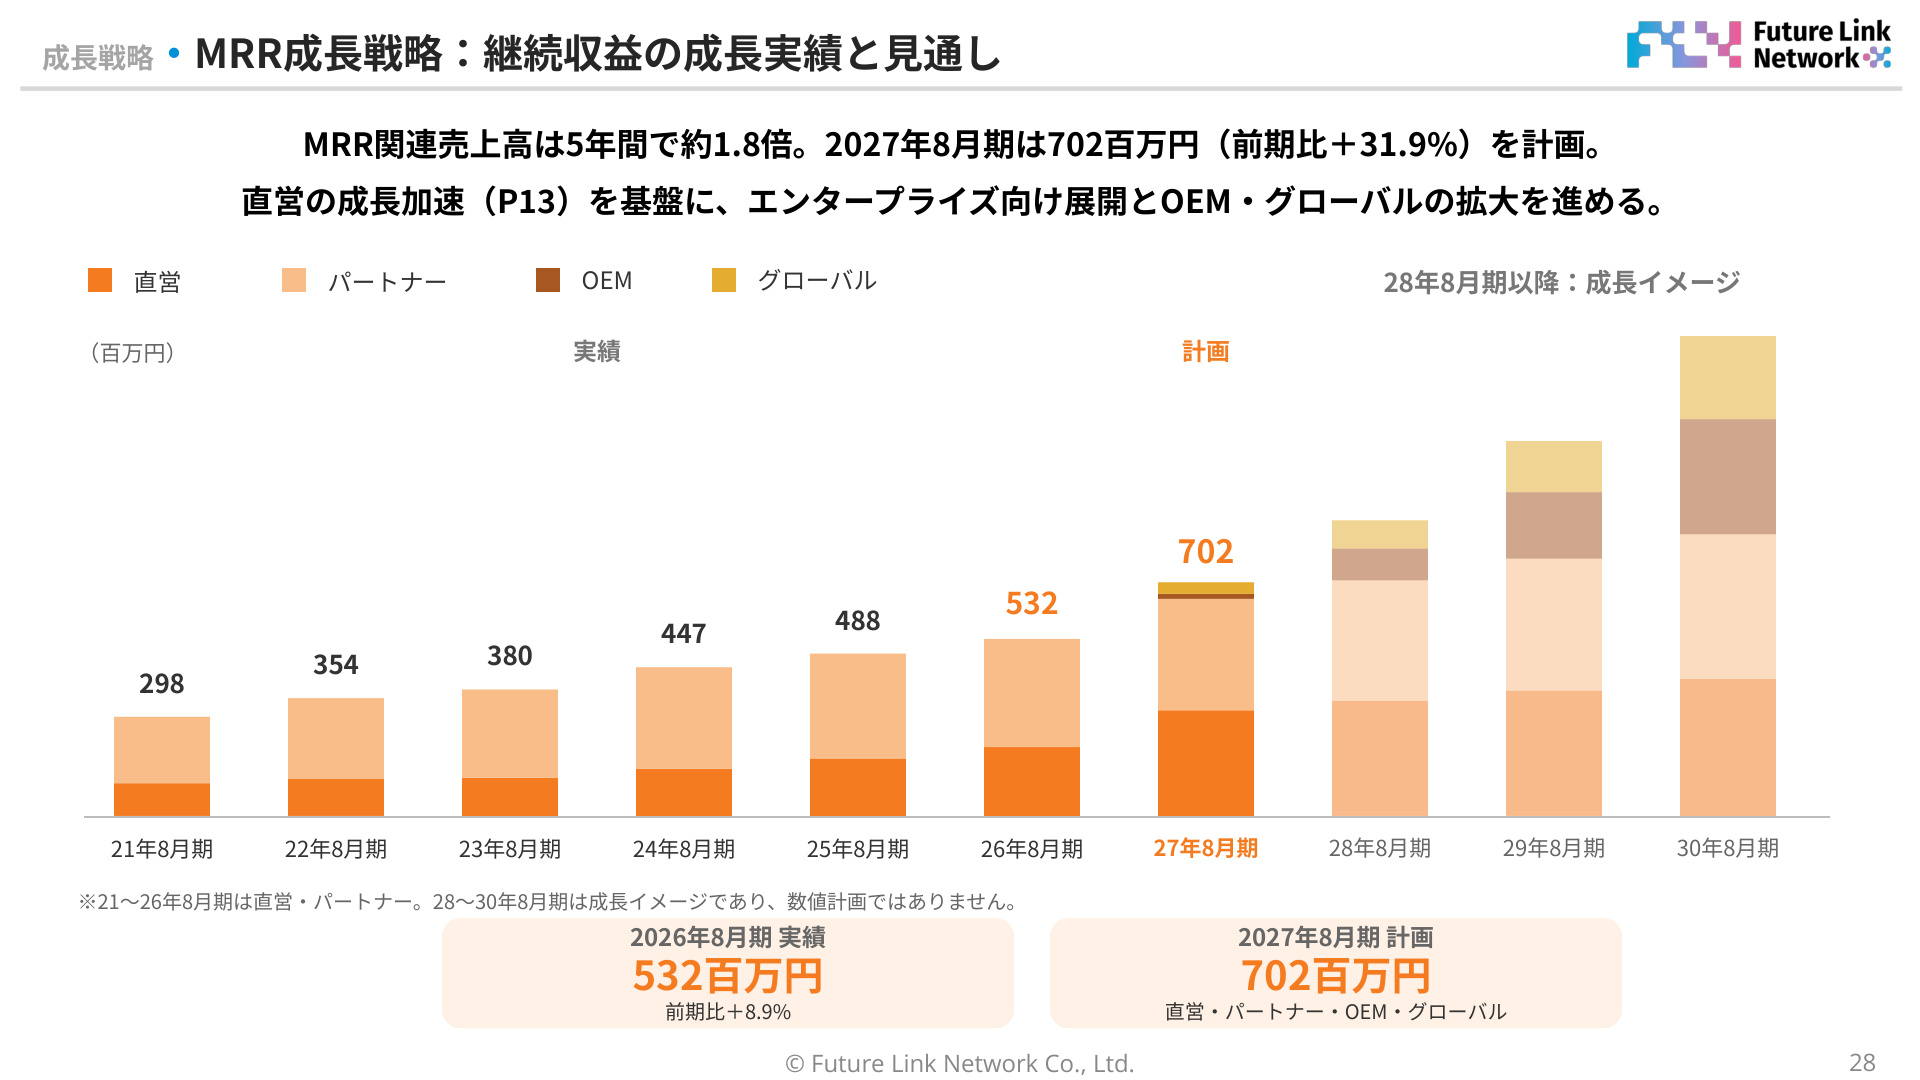
Slide Commentary (Growth Track Record and Outlook for Recurring Revenue)
The slide above is the most important chart showing the past performance and future growth plan of the company's MRR-related sales.
- Steady Accumulation of Stock Revenue MRR-related sales have grown approximately 1.8 times over five years , from 298 million yen in FY August 2021 to 532 million yen in FY August 2026. The expansion of direct operations and higher unit prices form the foundation of this growth.
- Acceleration Plan for FY August 2027 The company targets 702 million yen (+31.9% YoY) for FY August 2027. By adding "OEM" and "Global" revenue streams to the existing "Direct + Partner" dual-axis model, the company expects to achieve a non-linear growth curve.
- Domestic ARR Potential Based on the target number of paid stores (250,000 companies, representing a 6% share of the 4.21 million businesses nationwide), the ARR potential is estimated at approximately 4 billion yen. With the additional introduction of "Maiple-kun" (4–7 billion yen) and operational outsourcing (2–6 billion yen), the company is eyeing a total ARR potential of 10–17 billion yen .
5. FY August 2027 Full-Year Earnings Forecast and Roadmap to Profitability
Based on structural reforms and MRR growth initiatives, the company has announced the following consolidated earnings forecast for the fiscal year ending August 2027:
- Net Sales : 1.675 billion yen ( +10.8% YoY )
- Operating Profit : 22 million yen ( Turnaround to Operating Profit )
- Ordinary Profit : 16 million yen ( Turnaround to Profit )
- Net Income Attributable to Owners of the Parent : 50 million yen ( Turnaround to Final Profit )
By segment, the Regional Information Distribution business is expected to be the primary driver with sales of 1.103 billion yen (+32.4% YoY) , aiming for MRR sales of 702 million yen (+31.9%) and new partner contract/AI-related sales of 84 million yen (+276.5%). Meanwhile, the Public Solutions business expects sales of 572 million yen (down 15.7% YoY) as it selectively accepts hometown tax orders and reviews its organizational structure.
Cost of sales is projected at 535 million yen (+4.7% YoY) and SG&A expenses at 1.117 billion yen (+3.2% YoY). By curbing expense growth and raising the gross profit margin to 68.0% , the company aims to secure an operating profit of 22 million yen. It also anticipates booking extraordinary income from the human resource development subsidy that was deferred in the previous fiscal year.
Summary
Although the fiscal year ended August 2026 resulted in a significant net loss due to the decline in the hometown tax business and impairment charges, the company saw steady progress in stock business metrics that determine mid-to-long-term competitiveness, such as accelerated direct MRR growth (+23.7% YoY in Q4) and increased average customer unit price (+2,390 yen) . For the fiscal year ending August 2027, the focus for achieving profitability will be the restructuring of the hometown tax business within the newly split FLS and the expansion of the "Maiple" platform's monetization—including AI, OEM, and overseas operations—within the FLN parent entity.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.