

SYLA Holdings Co.,Ltd. Q1 FY2027 Earnings Deep Dive: Dual Growth in Flow and Stock, ARR Surpasses 2.3 Billion Yen, and Development Pipeline Progress
Sentiment Analysis
SYLA Holdings Co.,Ltd. (Securities Code: 8887) has announced its Q1 FY2027 financial results , marking a solid start characterized by revenue growth and a significant increase in operating profit, driven by its core comprehensive real estate and property management businesses. The company's dual-engine model—consisting of "flow revenue from development and sales" and "stock revenue (bedrock revenue) from management and holdings"—is steadily bearing fruit.
This report organizes key topics for investors from multiple perspectives, providing a detailed analysis of performance trends, segment-specific progress, growth drivers, and shareholder return policies.
1. Q1 FY2027 Earnings Highlights and Full-Year Progress
The consolidated results for the first quarter recorded figures exceeding the same period of the previous year in both revenue and core business profit.
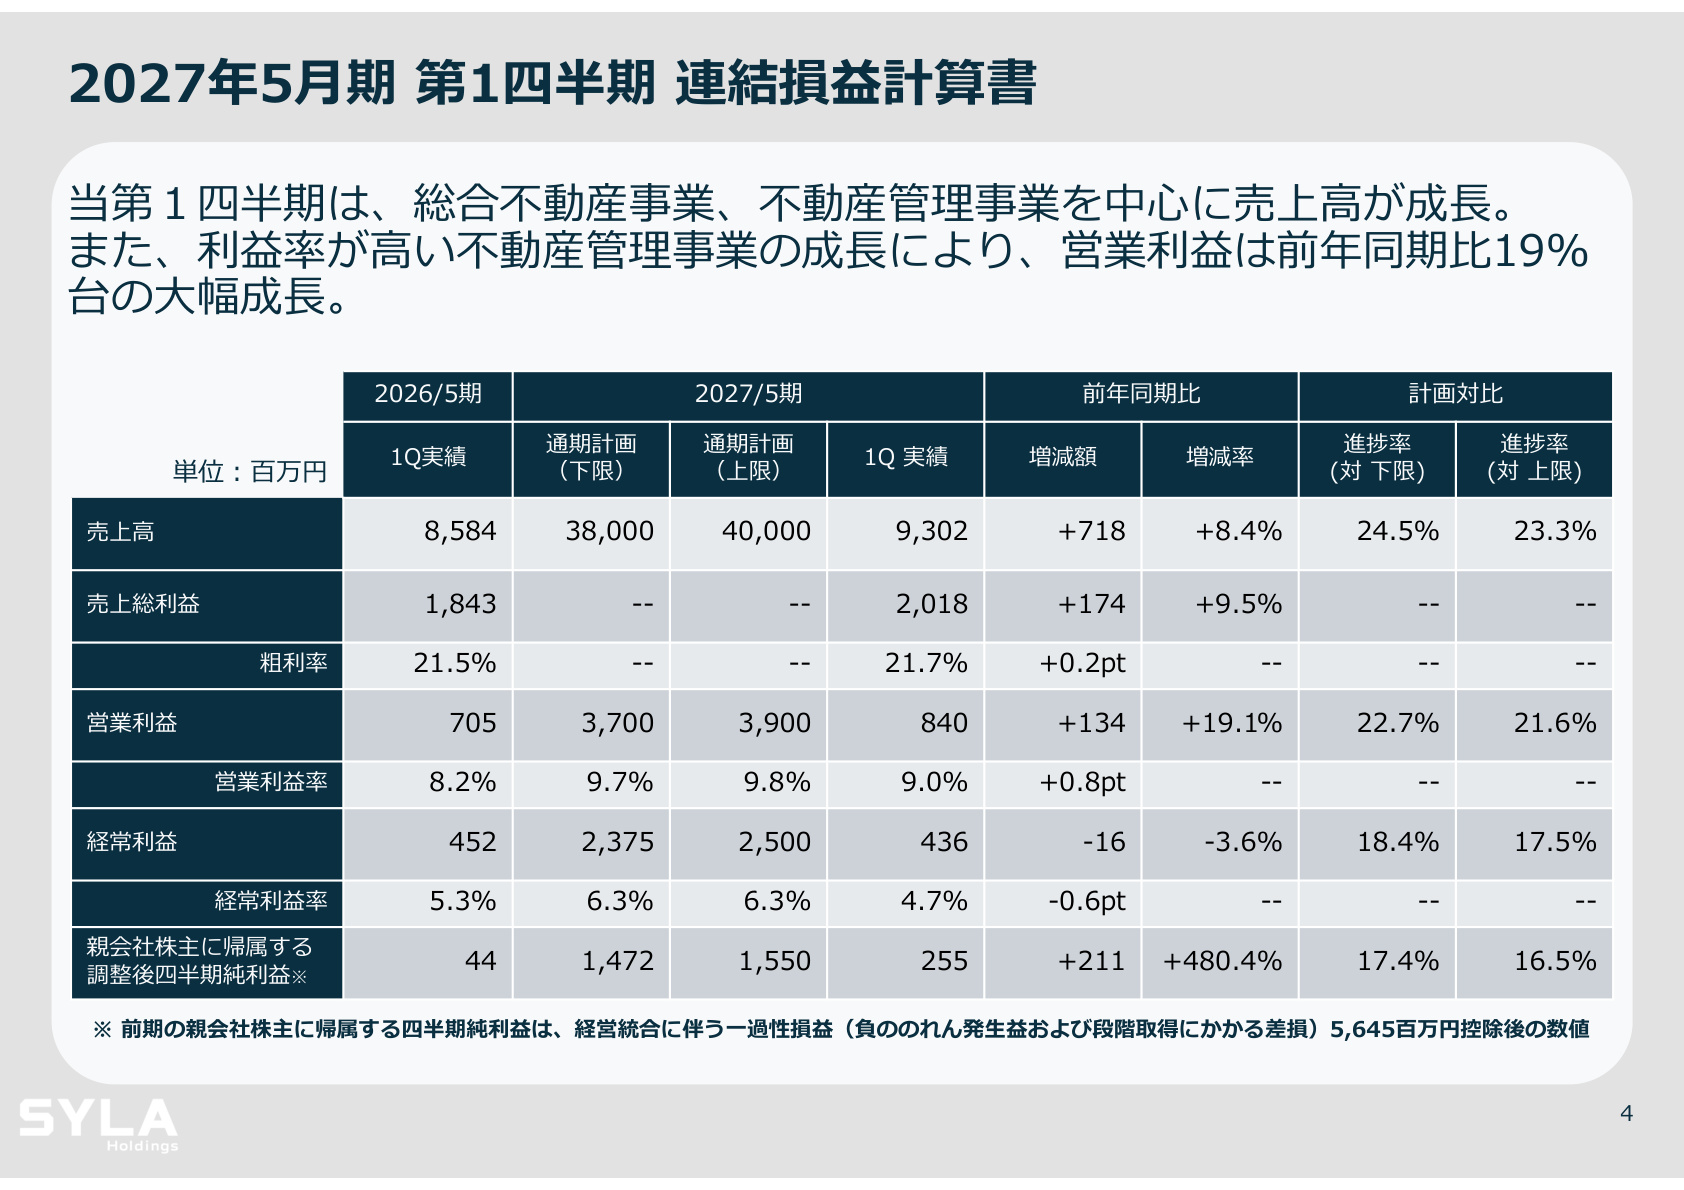
The slide above is critical data showing the consolidated statement of income for the first quarter and the progress rate against the full-year earnings forecast. Key takeaways from this slide are as follows:
- Net Sales : 9,302 million yen (+8.4% YoY)
- Gross Profit : 2,018 million yen (+9.5% YoY, gross margin 21.7%)
- Operating Profit : 840 million yen (+19.1% YoY, operating margin 9.0%)
- Ordinary Profit : 436 million yen (-3.6% YoY)
- Adjusted Quarterly Profit Attributable to Owners of Parent : 255 million yen (+480.4% YoY)
Progress against the full-year plan (disclosed as a range: net sales of 38,000–40,000 million yen, operating profit of 3,700–3,900 million yen, and profit attributable to owners of parent of 1,472–1,550 million yen) stands at 23.3%–24.5% for net sales and 21.6%–22.7% for operating profit. Since the company's development projects are scheduled to concentrate completions in the second half, the business structure is "second-half weighted." However, achieving over 20% progress in the first quarter confirms that the company is advancing at a cruising speed in line with its plan.
2. Analysis of Profit Fluctuations: Core Business Revenue Expansion and Financial Costs
The significant increase in operating profit of +134 million yen (+19.1% YoY) is primarily attributed to the following business contributions:
- Profit Expansion in Comprehensive Real Estate Business (+177 million yen) : Successful contributions from bulk sales of properties and condominium sales.
- Profit Growth in Property Management Business (+99 million yen) : Increased number of managed units, progress in rent increase negotiations, and the absence of one-time expenses incurred in the same period last year boosted profit margins.
Conversely, ordinary profit saw a slight decline of -16 million yen (-3.6% YoY) . This was impacted by an increase in non-operating expenses, such as higher interest expenses (-99 million yen) and increased payment commissions (-44 million yen) associated with borrowings. As the company is in a phase of actively accumulating inventory (up 2,967 million yen from the end of the previous fiscal year to 39,412 million yen), leading to an increase in interest-bearing debt, the pace of recovery through the delivery and sale of completed properties will be closely monitored.
3. Segment Trends and Extensive Development Pipeline
(1) Comprehensive Real Estate Business
Net sales reached 8,174 million yen (+9.5% YoY) and segment profit was 1,407 million yen (+14.4% YoY), driving the company's overall performance. Contributions came from the bulk sale of income-generating properties such as the "Okachimachi Project," "SYLA KAWASAKI," and "Nishi-Oi," as well as land sales and condominium sales at "Bandobashi."
Land acquisition for future supply is also underway, with purchases in Yokohama City and Taito Ward. Notably, in the Asakusa Kaminarimon area, the group acquired land for its first-ever residential hotel development , further diversifying its asset types.
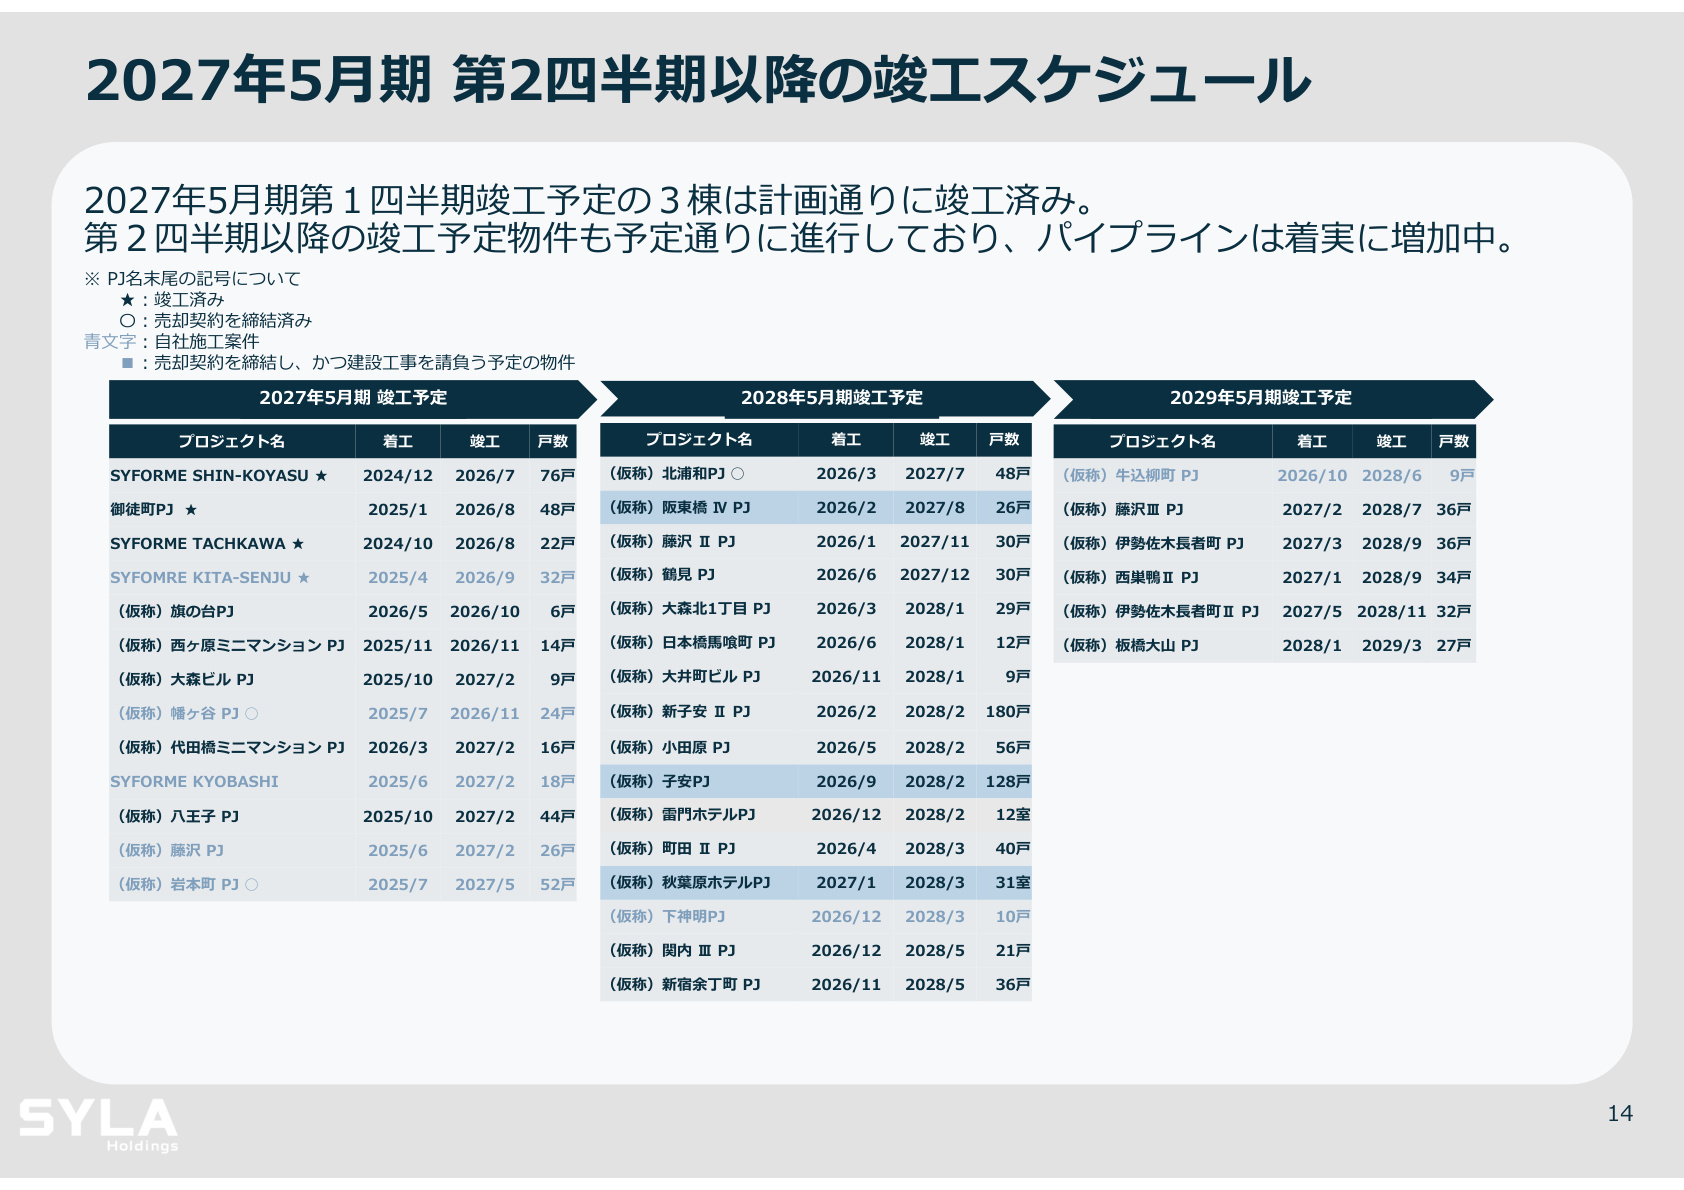
The "Completion Schedule" slide above is essential for evaluating the company's future revenue certainty and growth speed. In addition to the three buildings completed as planned in the first quarter ("SYFORME SHIN-KOYASU," "Okachimachi PJ," and "SYFORME TACHIKAWA"), numerous projects are scheduled for completion within FY2027, including Senju-Higashi, Hatanodai, Nishigahara, Omori Building, Hatagaya, Daitabashi, Kyobashi, Hachioji, Fujisawa, and Iwamotocho. Furthermore, the pipeline for FY2028 and FY2029, including large-scale projects, is steadily building up, maintaining high visibility for development supply over the medium to long term.
(2) Property Management Business
Net sales were 786 million yen (+17.9% YoY) and segment profit was 334 million yen (+42.6% YoY), achieving significant profit growth. Following the acquisition of income-generating buildings in Shimo-Ochiai, Shinjuku Ward and Akabane, Kita Ward, as well as the completion of new properties, the number of managed buildings expanded to 118 and rental management units to 4,165 . Furthermore, rent increase negotiations during contract renewals were successful, with the rent increase rate reaching 7.71% . Profitability improved significantly due to the absence of one-time expenses such as real estate acquisition taxes and tenant acquisition costs.
(3) Construction Business
Net sales were 91 million yen (+100.6% YoY), and segment profit was -115 million yen (compared to -63 million yen in the same period last year). In addition to proceeding with in-house construction projects (5 projects, construction budget of 3,616 million yen) as planned, the company secured an external construction contract for the "Bandobashi IV PJ." The total value of contracted external construction projects has expanded to approximately 3.8 billion yen , moving toward a phase of revenue and profit recognition upon completion.
(4) Renewable Energy Business
Net sales were 233 million yen (-32.1% YoY), and segment profit was -18 million yen (+8 million yen YoY). Although revenue declined due to the absence of civil engineering projects, the deficit narrowed. In addition to the development and holding of solar power plants, the company is focusing on expanding its "grid-scale battery storage business" to stabilize power supply and demand, and decided to acquire an additional grid-scale battery storage facility in Oyama City, Tochigi Prefecture, in July.
4. "Bedrock Revenue" and Unrealized Gains on Assets Strengthening the Management Foundation
The company prioritizes "bedrock revenue (stock revenue)," consisting of rental income from held properties and management fees, as its most important measure for medium- to long-term management stability.
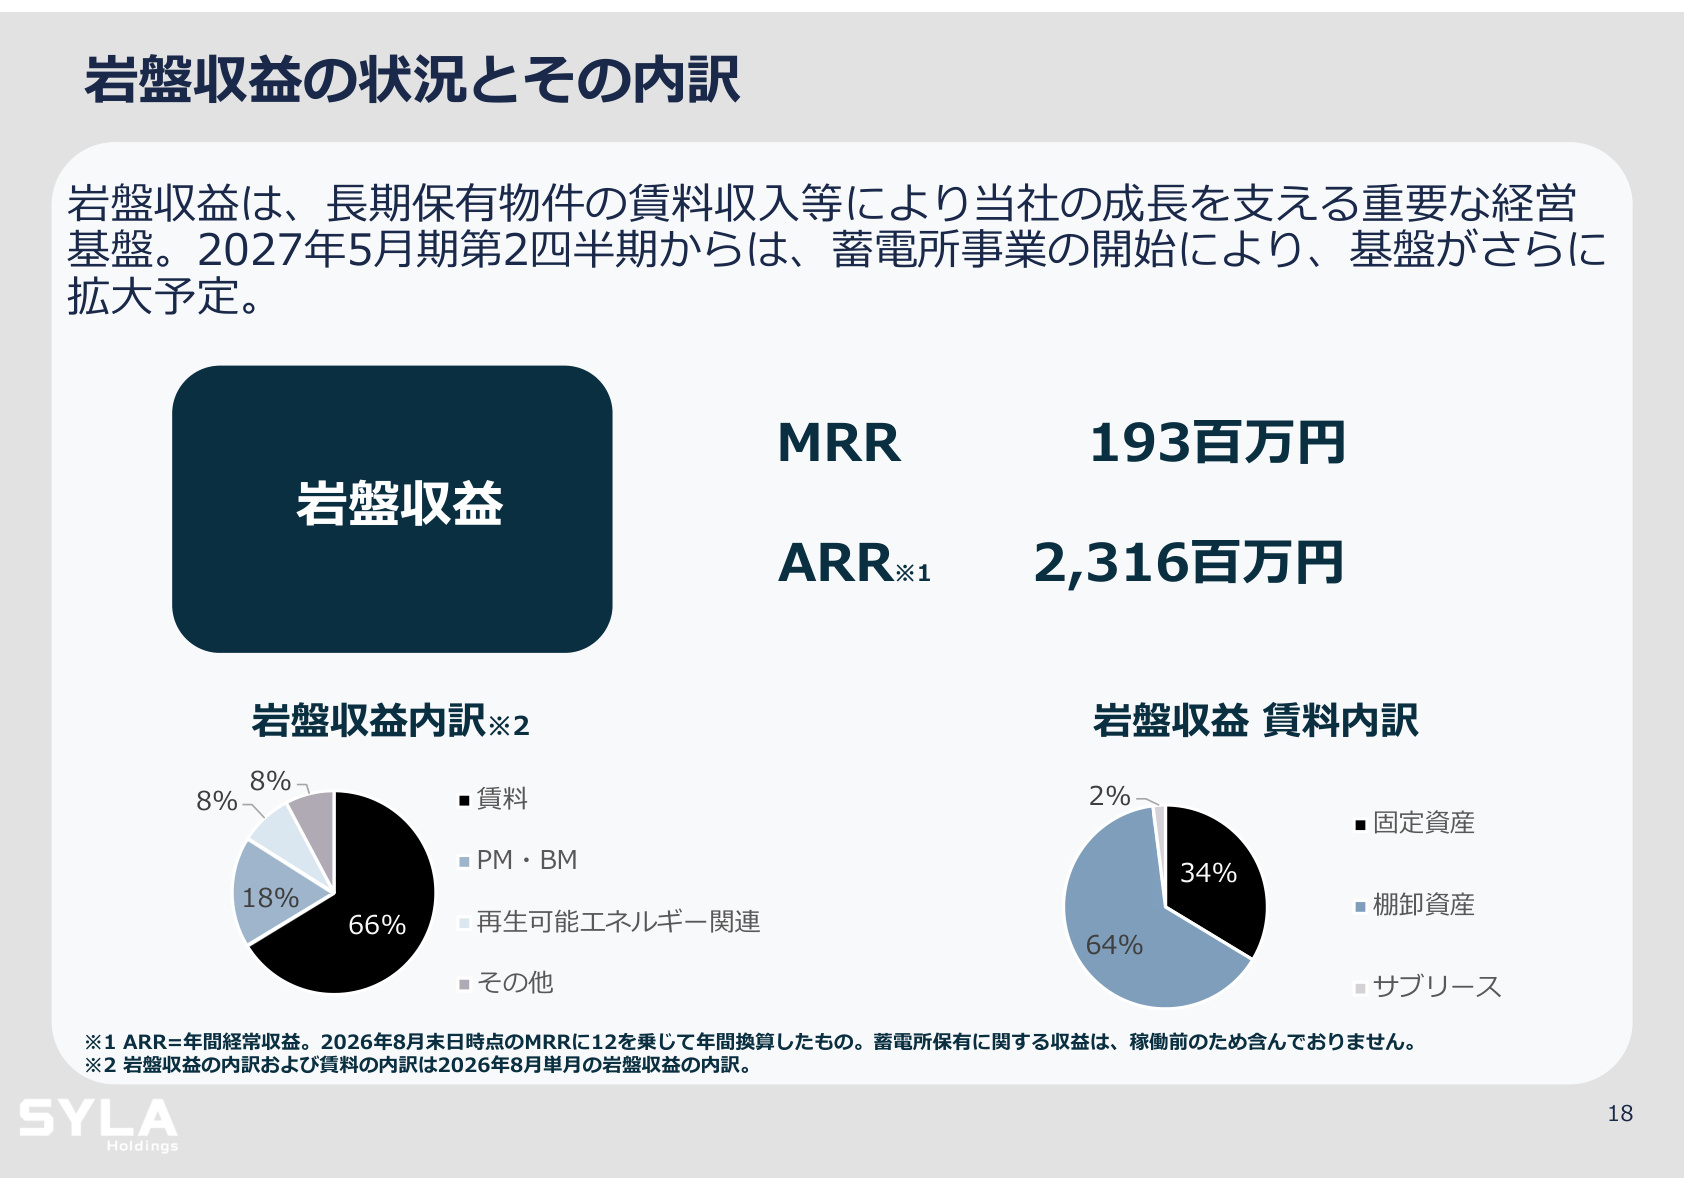
The slide above illustrates the structure of the bedrock revenue the company has accumulated. The ARR (Annual Recurring Revenue) , calculated by annualizing monthly recurring revenue, has reached 2,316 million yen (193 million yen in MRR terms). The breakdown shows that rental income, which generates stable cash flow, accounts for 66%, and property management/building management (PM/BM) accounts for 18%, demonstrating a solid recurring foundation.
Furthermore, from the second quarter onward, revenue from power sales and operations following the start of grid-scale battery storage facilities is expected to be added to bedrock revenue, with plans to expand both the quality and quantity of stock revenue.
Additionally, the value of fixed assets that the company has acquired and held over time is significant. Based on data as of the end of May 2026, against a book value of held assets of 32,607 million yen, the unrealized gains on fixed assets accumulated over many years amount to approximately 7.2 billion yen , bringing the substantial scale of held assets, considering these unrealized gains, to 39,851 million yen . These thick unrealized assets serve as a factor underpinning the substantial soundness of the company's balance sheet.
5. Shareholder Return Policy: Introduction of Progressive Dividends, Shareholder Perks, and Share Buybacks
The company positions the improvement of capital efficiency and shareholder returns as key management issues, disclosing major financial indicators (as of August 31, 2026) such as ROE of 7.9%–8.3% , ROA of 2.0%–2.1% , Net D/E Ratio of 2.0x , and DOE of 2.9% .
As for shareholder return measures, the following comprehensive policies have been implemented:
- Introduction of Progressive Dividend Policy : Transitioning to a policy of maintaining or increasing dividends without reducing them. The annual dividend forecast for FY2027 is 14 yen per share (7 yen interim, 7 yen year-end), an increase of 1 yen from the previous fiscal year (dividend yield of 3.9%).
- Acquisition of Treasury Stock : Completed the acquisition of treasury stock totaling 99.9 million yen (264,500 shares) in July and August 2026.
- Total Return Ratio : The total return ratio for the current fiscal year is expected to be 44.5%–46.9% .
- Expansion of Shareholder Perks : In addition to "Yomawari-kun Coins" usable on the crowdfunding platform, the company announced a digital gift system for long-term shareholders.
6. Summary and Future Focus
In Q1 FY2027, SYLA Holdings Co.,Ltd. showed solid progress, with three elements interlocking: "steady sales and settlement in the comprehensive real estate business," "higher profitability in the property management business (rent increase rate of 7.71%)," and "bedrock revenue with an ARR exceeding 2.3 billion yen."
Points to watch in the future include the smooth completion and delivery of large-scale development projects planned for the second half, the progress in revenue recognition for external construction contracts reaching a total of 3.8 billion yen, and the revenue contribution from the operation of new grid-scale battery storage facilities. With a capital policy supported by thick unrealized gains on held real estate and a progressive dividend policy, the company's performance in the second half toward achieving its full-year forecast will be closely monitored.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.