

【KOMPEITO (618A) FY August 2026 Financial Results】Achieving First Full-Year Profitability, Entering a Phase of Profit Growth Driven by Operating Leverage
Sentiment Analysis
KOMPEITO Inc. (Securities Code: 618A), the operator of the office-based healthy food service "OFFICE DE YASAI," has announced its financial results for the fiscal year ended August 2026. The company achieved a significant year-on-year revenue increase of +71.9% , reaching 9.865 billion yen . Operating profit turned from a loss of 225 million yen in the previous fiscal year to a profit of 895 million yen . By steadily accumulating recurring revenue and improving the marginal profit ratio, the company has surpassed its break-even point and transitioned into a profit-generating phase where operating leverage effectively drives earnings.
This report summarizes key topics from the public disclosures, detailing the factors behind the performance, trends in KPIs, progress in M&A, and the earnings outlook for the fiscal year ending August 2027, which projects a substantial increase in profit.
1. FY August 2026 Consolidated Financial Highlights
The consolidated financial results for the fiscal year ended August 2026 recorded exponential growth driven by the expansion of the core business and contributions from consolidated subsidiaries.
- Net Sales : 9.865 billion yen (+71.9% YoY)
- Gross Profit : 6.47 billion yen (+70.8% YoY, Gross Profit Margin 65.6%)
- Operating Profit : 895 million yen (Turned profitable from a 225 million yen loss in the previous year, Operating Profit Margin 9.1%)
- Ordinary Profit : 868 million yen (Turned profitable from a 245 million yen loss in the previous year)
- Net Income Attributable to Owners of Parent : 1.079 billion yen (Turned profitable from a 161 million yen loss in the previous year, Net Profit Margin 10.9%)
Compared to the initial forecasts, net sales reached 9.865 billion yen against the 9.871 billion yen forecast (99.9% achievement rate) , and operating profit reached 895 million yen against the 880 million yen forecast (+1.7% vs. forecast) , landing largely in line with the plan. The reason net income attributable to owners of parent exceeds operating profit is due to the reduction in tax expenses resulting from the application of tax effect accounting related to tax loss carryforwards during the period.
Regarding the breakdown of net sales, the core "OFFICE DE YASAI business" maintained high growth at 8.764 billion yen (+60.1% YoY) , while M&A activities executed during the period added 1.107 billion yen in sales from consolidated subsidiaries , significantly boosting the top line.
2. Mechanism of Rapid Profit Expansion: Full-Scale Realization of Operating Leverage
The most significant turning point in the fiscal year ended August 2026 was the establishment of a structure where the business surpassed the break-even point, leading to a rapid expansion in operating profit . The following factor analysis slide clearly illustrates this change in the profit structure.
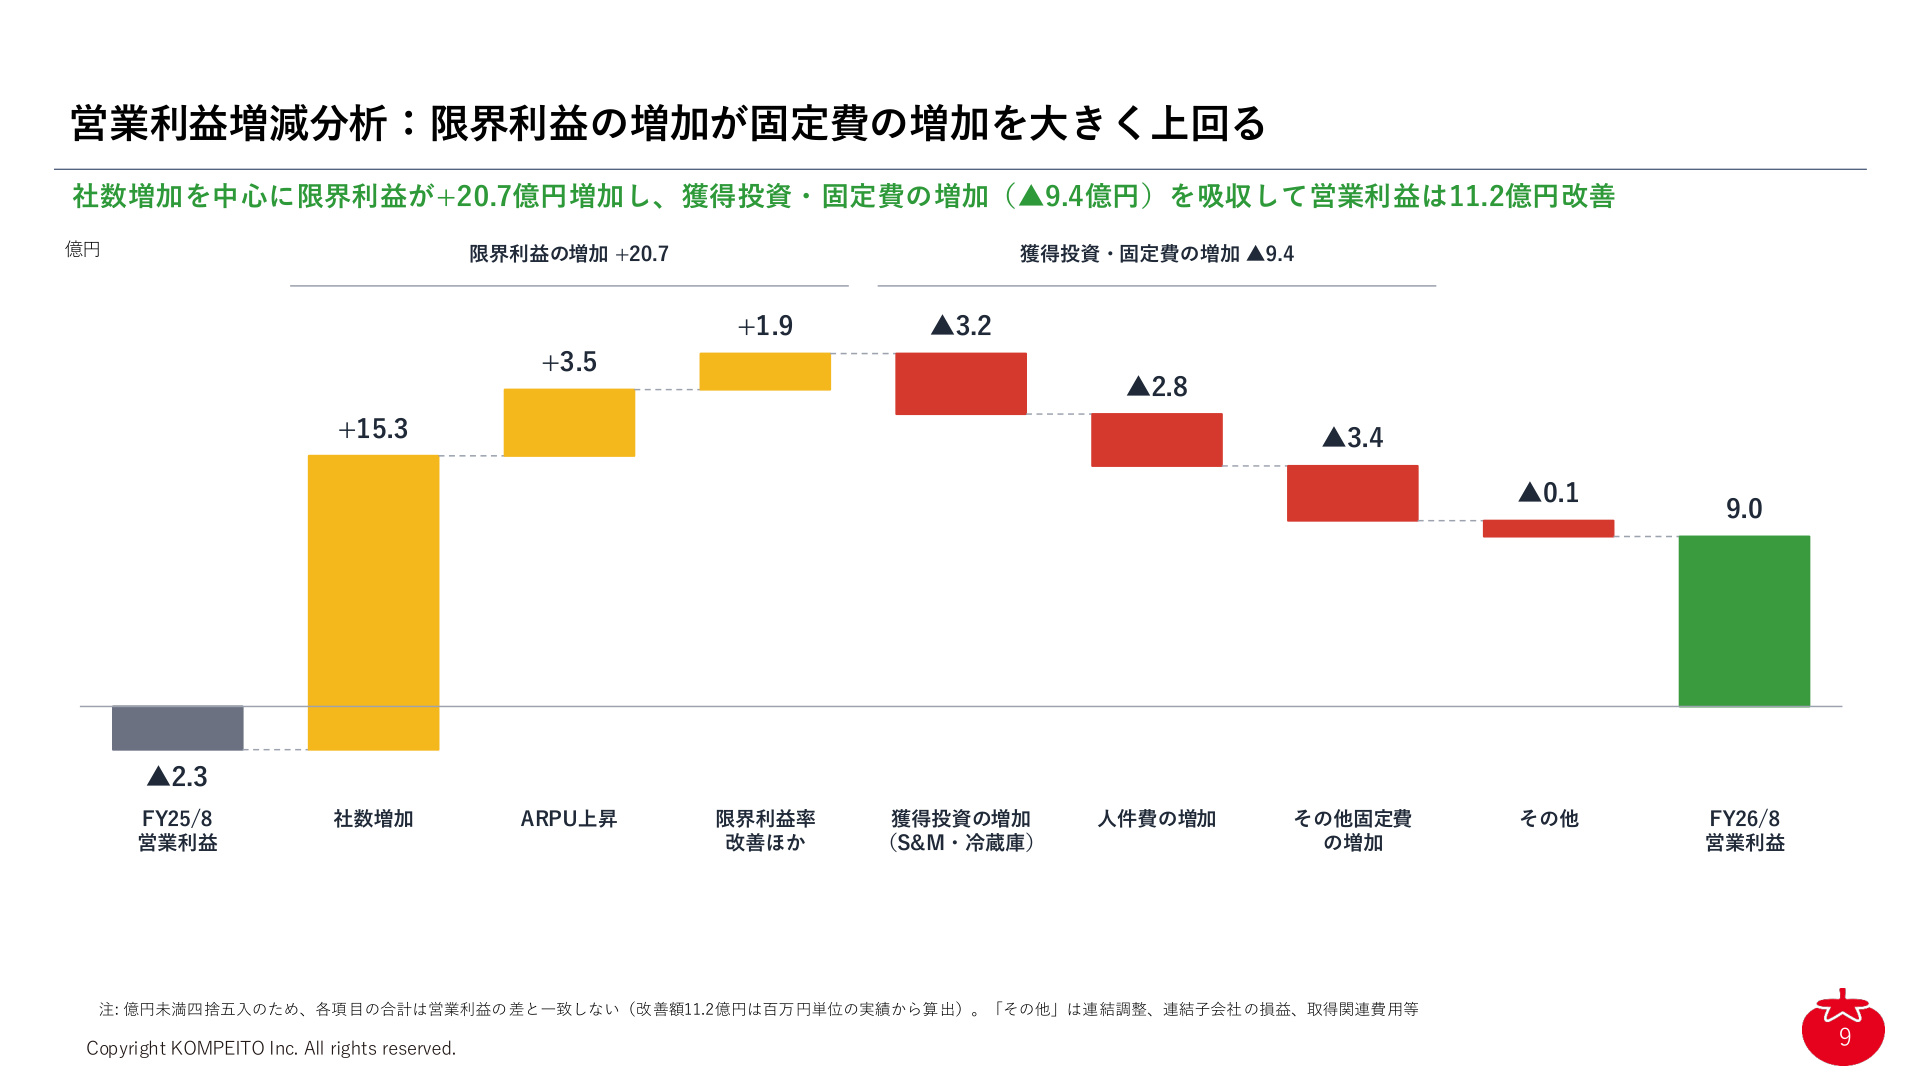
This waterfall chart demonstrates the financial logic behind how the company shifted from an operating loss in the previous year to generating approximately 900 million yen in operating profit.
- Increase in Marginal Profit (+2.07 billion yen) :
- Marginal profit increase due to the rise in the number of main contracts in the core business: +1.53 billion yen
- Increase in Average Revenue Per User (ARPU): +0.35 billion yen
- Improvement in marginal profit ratio and others due to cost and logistics efficiency: +0.19 billion yen
- Increase in Fixed Costs and Investments (-0.94 billion yen) :
- Increase in acquisition investments (S&M expenses, etc.) such as sales promotion and refrigerators: -0.32 billion yen
- Increase in personnel expenses due to the expansion of the organizational structure: -0.28 billion yen
- Increase in other fixed costs such as logistics bases and system infrastructure: -0.34 billion yen
With the marginal profit ratio improving by +1.7pt from 59.0% in the previous year to 60.7% , and the expansion of recurring revenue accumulated monthly from acquired clients, a structure was completed where the increase in marginal profit (2.07 billion yen) significantly exceeded the increase in acquisition investments and fixed costs (0.94 billion yen) . This resulted in an improvement in operating profit/loss of 1.12 billion yen .
3. KPI Trends and Sales Structure of the Core "OFFICE DE YASAI Business"
The company's business model is a highly recurring model consisting of a "monthly usage fee" received from corporate clients and "product sales" consumed from dedicated refrigerators and freezers installed in offices. As of the end of the fiscal year ended August 2026, the Annual Recurring Revenue (ARR) reached 9.676 billion yen (+54.7% YoY) .
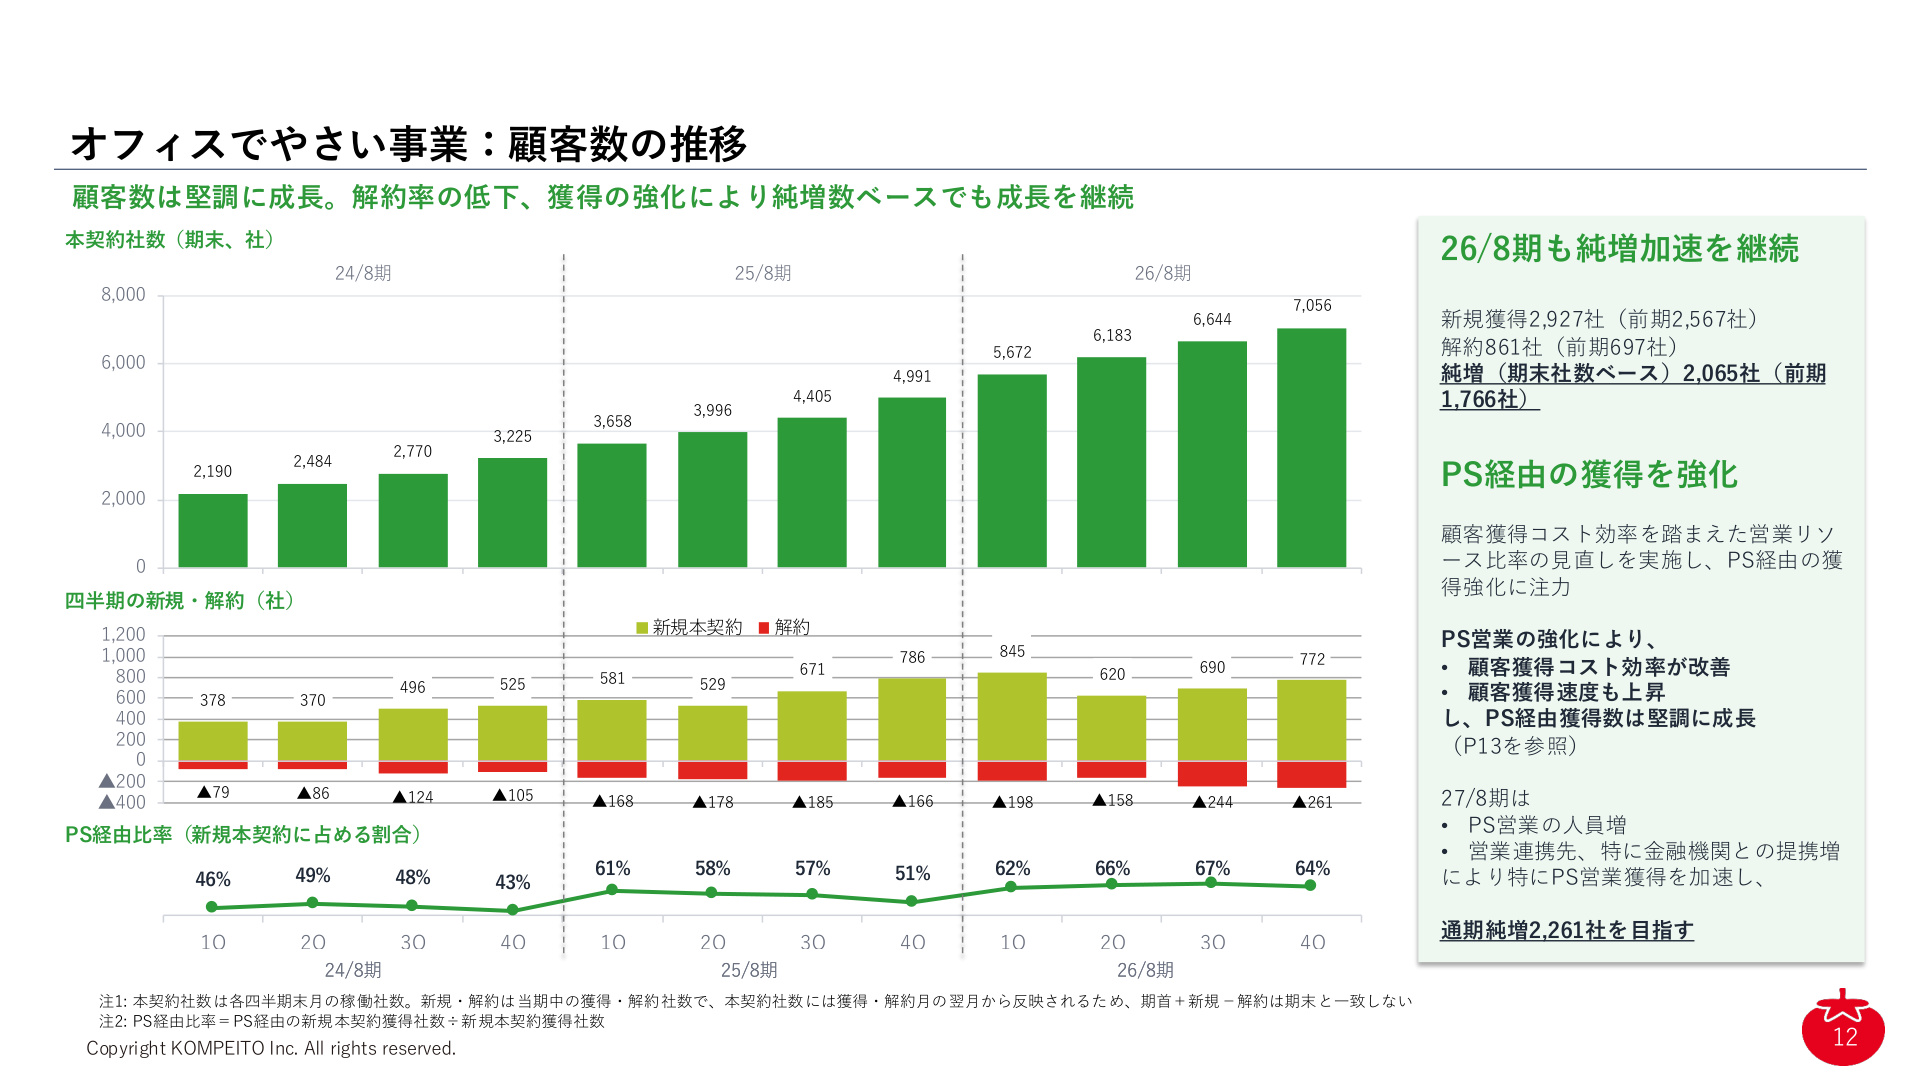
As shown in the slide above, the net growth speed of the client base is accelerating each period.
- Number of Main Contracts : Net increase from 4,991 at the end of the previous year to 7,056 (+41.4% YoY) (net increase of 2,065 companies ). The number of new annual acquisitions reached 2,927 companies (compared to 2,567 in the previous year).
- Monthly Churn Rate : Further declined from 1.4% in the previous year to 1.1% (-0.3pt YoY) . In 4Q of the fiscal year ended August 2026, it maintained an extremely low level of 1.15% . Despite multiple service price increases in the past, the churn rate has consistently trended downward.
- ARPU (Annualized Revenue Per Company) : Increased from 1.25 million yen at the end of the previous year to 1.37 million yen (+9.4% YoY) . This was driven by an increase in the number of units installed per company (from 1.77 to 1.82) and an increase in product unit prices.
Supporting this acceleration in client acquisition is the expansion of the Partner Sales (PS) team . The number of sales partners, such as financial institutions and major welfare service companies, expanded rapidly from 185 at the end of the previous year to 319 (+72% YoY) . The number of full-time employees dedicated to PS also increased from 29 to 47 , and the ratio of new main contracts via PS reached 64% . By increasing the ratio of PS channels, which have high acquisition cost efficiency, the company has established a system for mass acquisition while controlling sales promotion costs.
4. Compression of Cost Structure and Infrastructure Integration through M&A
Looking at the transition of KOMPEITO's standalone sales percentage, the decline in the fixed cost ratio accompanying sales expansion is clear. S&M (sales and marketing) expenses, which accounted for 39% of sales in the fiscal year ended August 2020, fell to 21% , and other fixed costs such as personnel expenses were significantly diluted from 42% to 13% . The cost of goods sold ratio also decreased from 33% to 28% , steadily demonstrating economies of scale.
Furthermore, the company is actively promoting M&A aimed at strengthening its business foundation.
- Acquisition of Milk Delivery Businesses (3 cases in total) : Following the acquisition of Yamazaki Co., Ltd. in November 2024, the company acquired the businesses of Meiji Dairy Products Co., Ltd. in September 2025 and Value Quest Co., Ltd. in November 2025. By integrating a network of 7 stores in Tokyo and approximately 10,000 customers, the company is promoting the in-house production of last-mile delivery and the reduction of delivery costs.
- Acquisition of Food Service/Delivery Business : In October 2025, the company made Yushoku Co., Ltd. (Okayama Prefecture), which handles food delivery for the elderly, a wholly-owned subsidiary, and began in-house manufacturing .
The FY August 2026 sales of these acquired businesses reached approximately 1.07 billion yen , and synergy creation is progressing through the standardization of delivery routes and the increase in the ratio of in-house deliveries.
5. Earnings Outlook for the Fiscal Year Ending August 2027
For the following fiscal year ending August 2027, the company expects further earnings expansion.
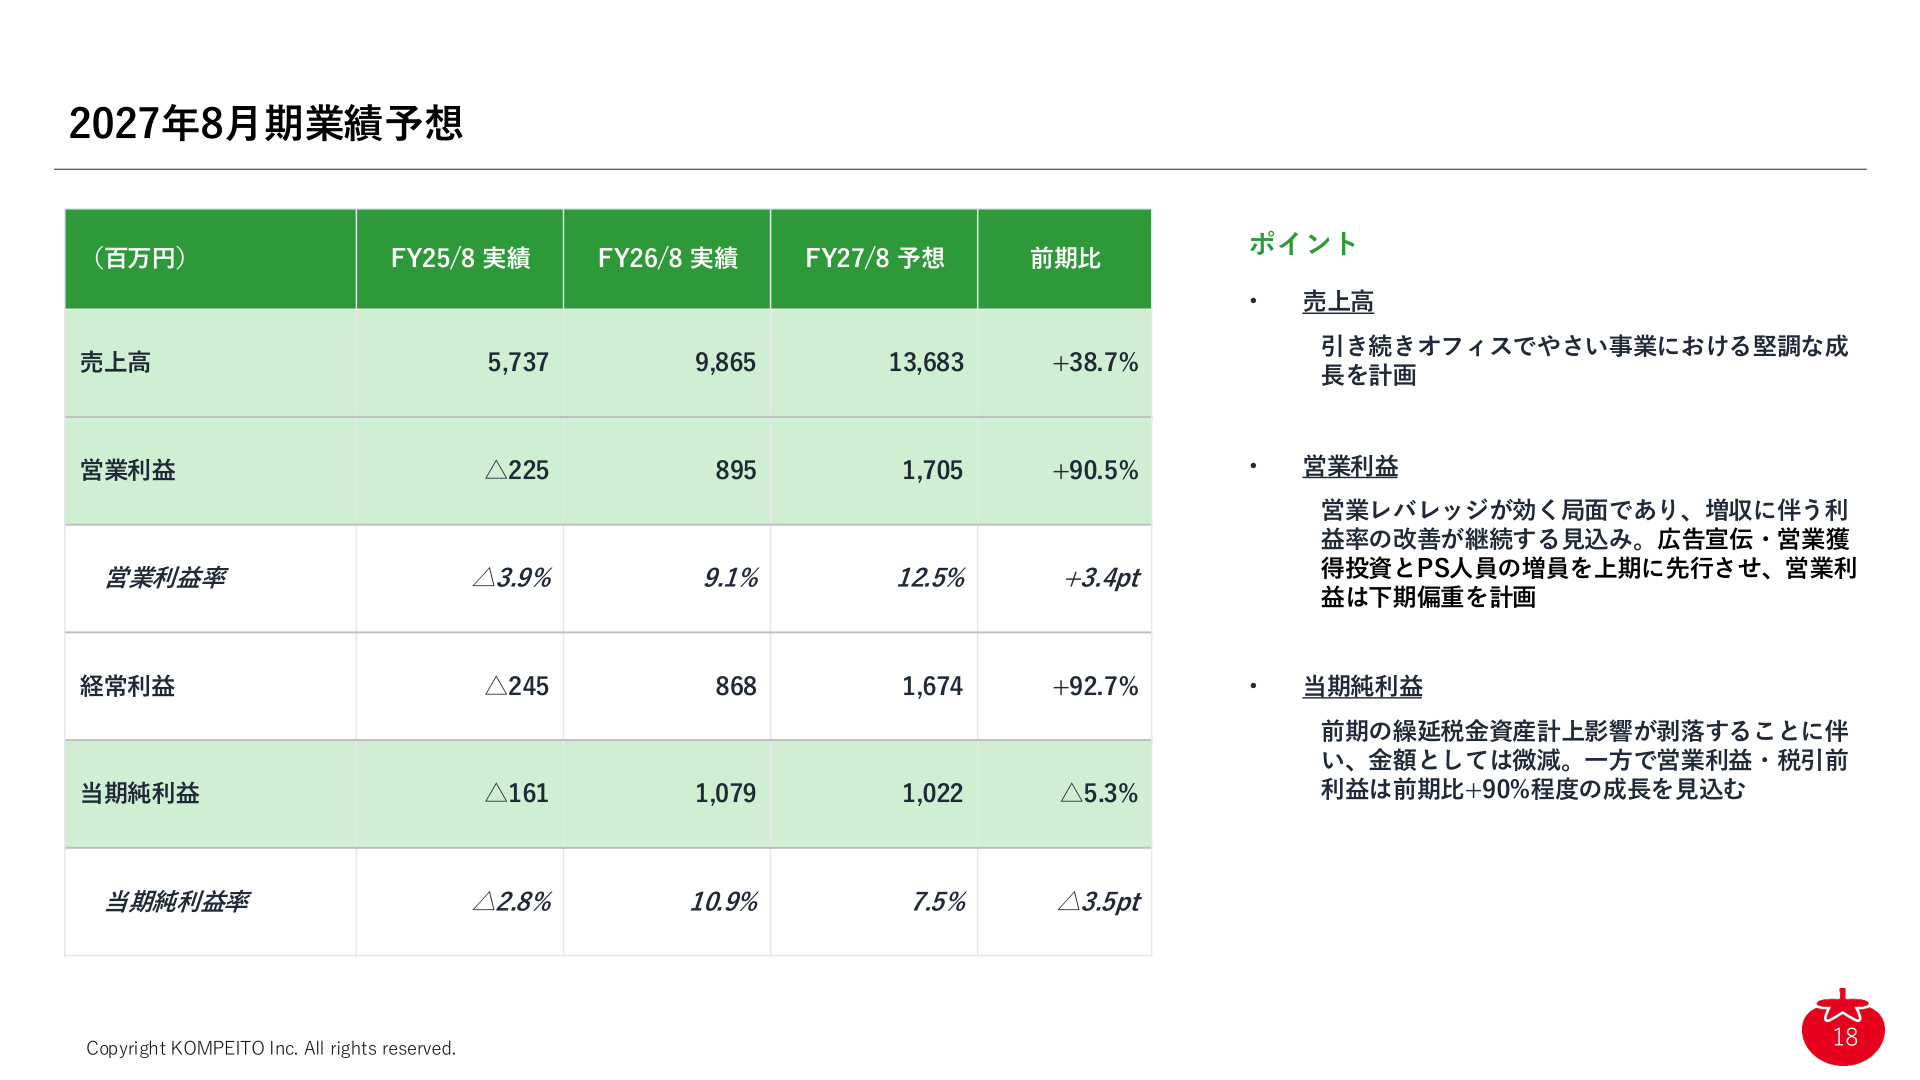
The consolidated earnings forecast for the fiscal year ending August 2027 is as follows:
- Net Sales : 13.683 billion yen (+38.7% YoY)
- Operating Profit : 1.705 billion yen (+90.5% YoY, Operating Profit Margin 12.5%)
- Ordinary Profit : 1.674 billion yen (+92.7% YoY)
- Net Income Attributable to Owners of Parent : 1.022 billion yen (-5.3% YoY, Net Profit Margin 7.5%)
Net sales are expected to reach an ARR of 13.96 billion yen , based on the net increase in the core business (number of main contracts 9,317, +32% YoY ) and ARPU improvement ( 1.5 million yen, +9% YoY ). In terms of profit, due to the continued effect of operating leverage, the company plans an operating profit of 1.705 billion yen (operating profit margin 12.5%) , which is nearly double the previous year. The slight decrease in net income attributable to owners of parent (-5.3%) is because the impact of the deferred tax assets (tax effect accounting) recorded in the previous year has run its course, returning to normal tax expense burdens; on a pre-tax profit basis, the company expects significant growth of +92% .
6. Mid- to Long-Term Business Development Concept
As a mid- to long-term strategy, the company aims to position "OFFICE DE YASAI" at the intersection of its established "nationwide cold chain delivery network" and "sales partnership network of over 300 companies," aiming for multi-faceted development as a platform.
- Expansion of Food and Beverage Delivery Area : Diversification of handled products utilizing existing delivery networks, such as office beverage sales and water server delivery, leveraging milk delivery and food service M&As.
- Expansion of Welfare and General Affairs Area : Promoting cross-selling of welfare card businesses and various peripheral services for general affairs to a corporate client base of over 7,000 companies.
- Geographic Expansion such as US Market Entry : Laying the groundwork for the global expansion of the model cultivated domestically.
With a solid recurring revenue base and a high retention rate (low churn rate) as its two wheels, the company is expanding its business as a corporate platformer that goes beyond a mere office food service.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.