

Asahi Kagaku Kogyo (7928) FY2026 Earnings Deep Dive: Achieving Operating Profitability and Optimizing Global Production
Sentiment Analysis
1. Executive Summary
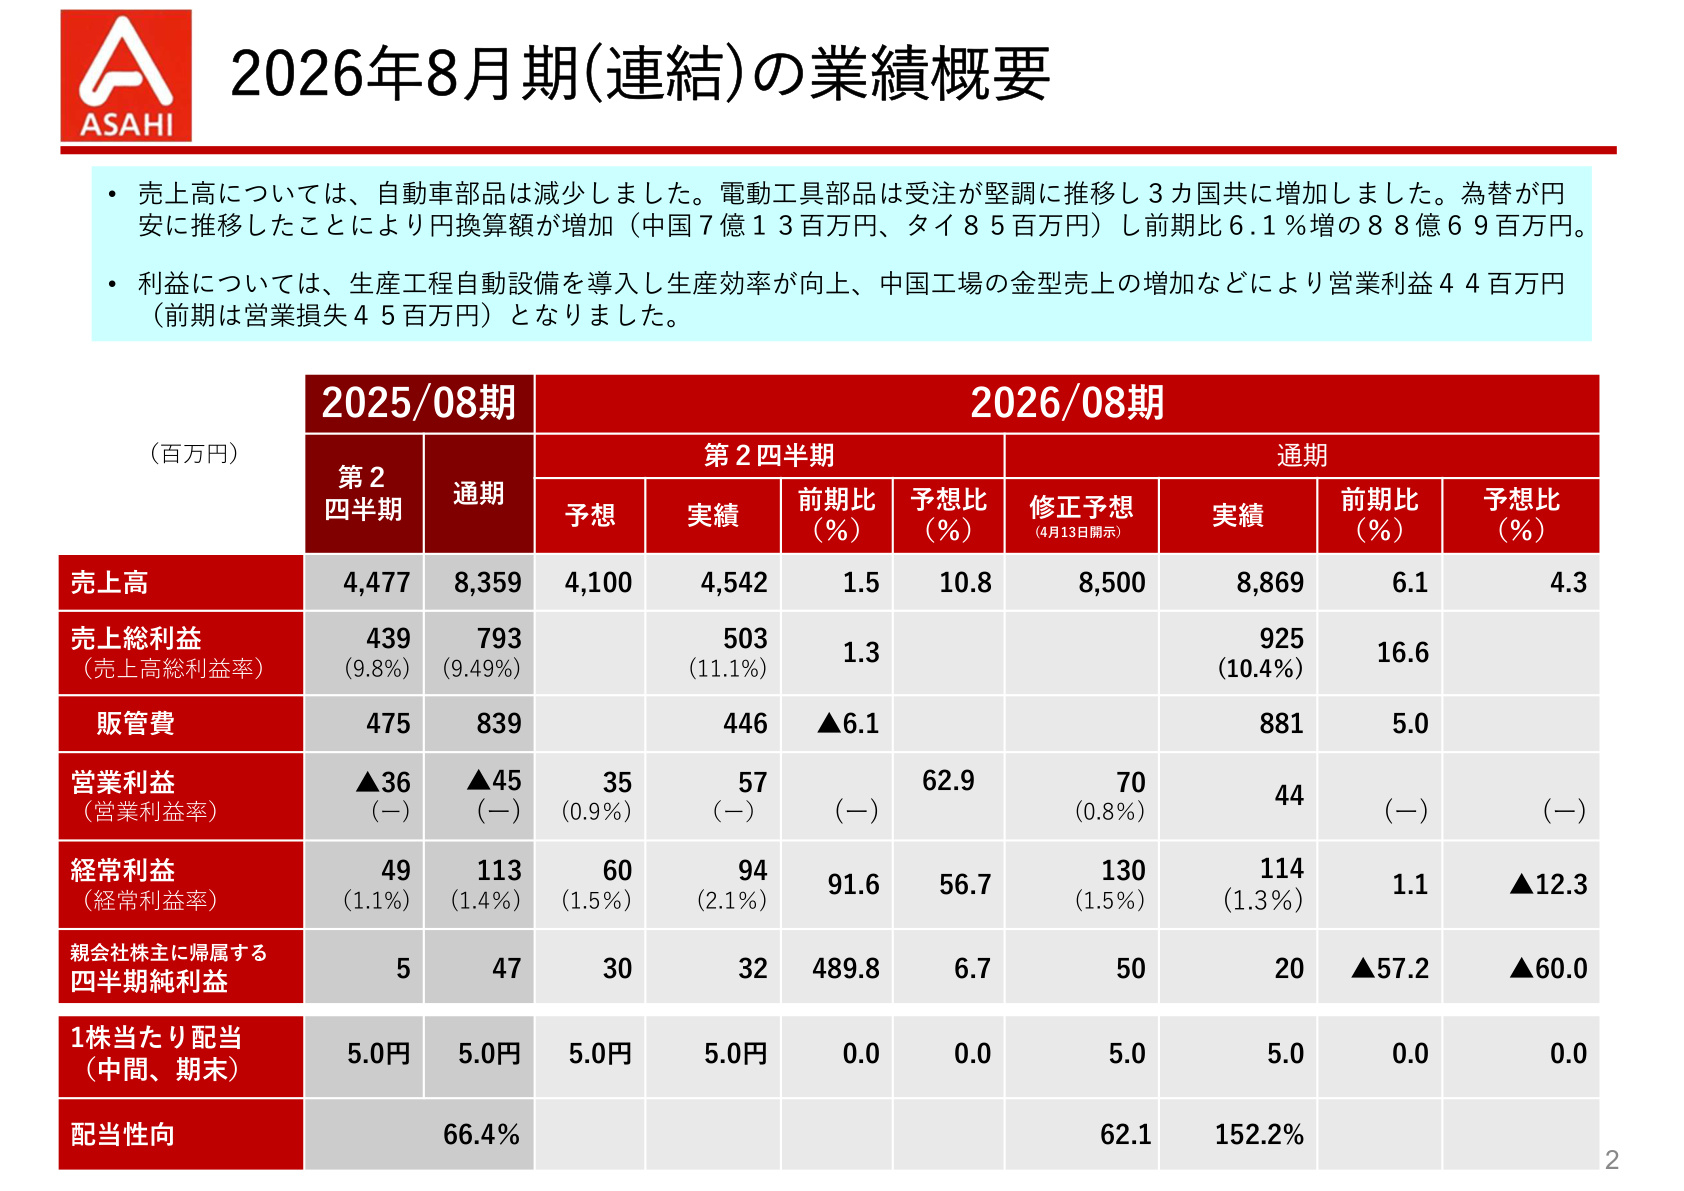
Asahi Kagaku Kogyo Co., Ltd. (Securities Code: 7928, TSE Standard/NSE Main) reported its FY2026 financial results , with net sales of 8.869 billion yen (up 6.1% YoY) and an operating profit of 44 million yen (compared to an operating loss of 45 million yen in the previous fiscal year) , marking a turnaround to operating profitability . Ordinary profit was 114 million yen (up 1.1% YoY) , and net profit attributable to owners of the parent was 20 million yen (down 57.2% YoY) .
Sales growth was driven by the steady performance of core power tool components across all three countries—Japan, China, and Thailand—as well as the impact of the weaker yen , which boosted yen-denominated figures (contributing 713 million yen from China and 85 million yen from Thailand). Regarding profitability, despite the burden of depreciation costs for molding machines in Japan, overall profitability was significantly bolstered by improved production efficiency through the introduction of automated equipment and an increase in high-margin mold sales at the Chinese plant.
2. FY2026 Consolidated Performance Highlights and Profit Structure Analysis
The following slide shows the consolidated performance for FY2026 compared to the revised forecasts and the previous fiscal year's results.
Overview and Implications
This slide demonstrates a clear improvement in Asahi Kagaku Kogyo's profitability compared to the previous year. Full-year net sales reached 8.869 billion yen , exceeding the initial forecast of 8.5 billion yen by 4.3% . Gross profit reached 925 million yen (up 16.6% YoY) , with the gross profit margin improving by approximately 0.9 percentage points from 9.49% in the previous year to 10.4% .
With selling, general and administrative (SG&A) expenses limited to a modest increase of 5.0% YoY to 881 million yen , the company recorded an operating profit of 44 million yen , achieving a turnaround to profit from the previous year's operating loss of 45 million yen. While this fell slightly short of the revised forecast announced on April 13 (operating profit of 70 million yen, ordinary profit of 130 million yen, and net profit attributable to owners of the parent of 50 million yen), the return to core profitability amidst rising raw material costs and equipment burdens represents steady progress.
While ordinary profit remained flat at 114 million yen , net profit attributable to owners of the parent was limited to 20 million yen . The annual dividend was maintained at 10.0 yen per share (5.0 yen interim, 5.0 yen year-end) as initially forecast, resulting in a dividend payout ratio of 152.2% .
3. Financial Foundation and Capital Investment Trends
Solid Financial Position and Asset Structure
Total assets at the end of FY2026 were 7.353 billion yen , an increase of 675 million yen from the end of the previous fiscal year (6.678 billion yen). While current assets expanded to 3.85 billion yen (up 693 million yen YoY), non-current assets remained largely flat at 3.503 billion yen (down 17 million yen YoY).
Total liabilities were 1.642 billion yen (up 255 million yen YoY) , and total net assets were 5.711 billion yen (up 421 million yen YoY) . Shareholders' equity stood at 4.088 billion yen, and the equity ratio remained at a very high level of 77.7% (79.2% at the end of the previous year), maintaining a sound financial position.
Active Capital Investment and Automation/Labor-Saving
Capital investments for the current period (60th term) totaled 305.11 million yen . The breakdown is as follows:
- Japan (Asahi Kagaku Kogyo Co., Ltd.) : 240.38 million yen invested primarily in molding machines and auxiliary production equipment (an 850t molding machine was installed at the head office plant in January 2026).
- China (Asahi Plastic (Kunshan) Co., Ltd.) : 55.02 million yen invested in molding machines, auxiliary production equipment, labor-saving equipment, and mold manufacturing equipment.
- Thailand (ASAHI PLUS CO., LTD.) : 9.7 million yen invested in auxiliary production equipment.
Efforts are being concentrated on upgrading molding machines and building automated lines to improve productivity.
4. Regional Performance Details
Asahi Kagaku Kogyo's operations consist of three bases: Japan, China, and Thailand, each exhibiting different profitability characteristics and challenges.
Domestic Business: Depreciation Burden and Shift to In-house Production
- Net Sales : 3.36 billion yen (down 6.6% YoY)
- Operating Profit : Operating loss of 172 million yen (compared to an operating loss of 239 million yen in the previous year)
Although power tool components performed steadily, sales were weighed down by a decrease in mass production shipments of high-unit-price painted automotive parts and production/shipment declines due to temporary shutdowns at client facilities following natural disasters such as earthquakes. Regarding profitability, while the business remains in the red due to the heavy depreciation burden of new molding machines, the deficit narrowed by 67 million yen from the previous year's 239 million yen, thanks to labor cost reductions through the introduction of labor-saving equipment and expense-cutting measures such as returning a leased warehouse in December 2025. Moving forward, the company plans to bring some outsourced products in-house to reduce outsourcing costs.
China Business: High-Margin Mold Manufacturing and Automation Driving Performance
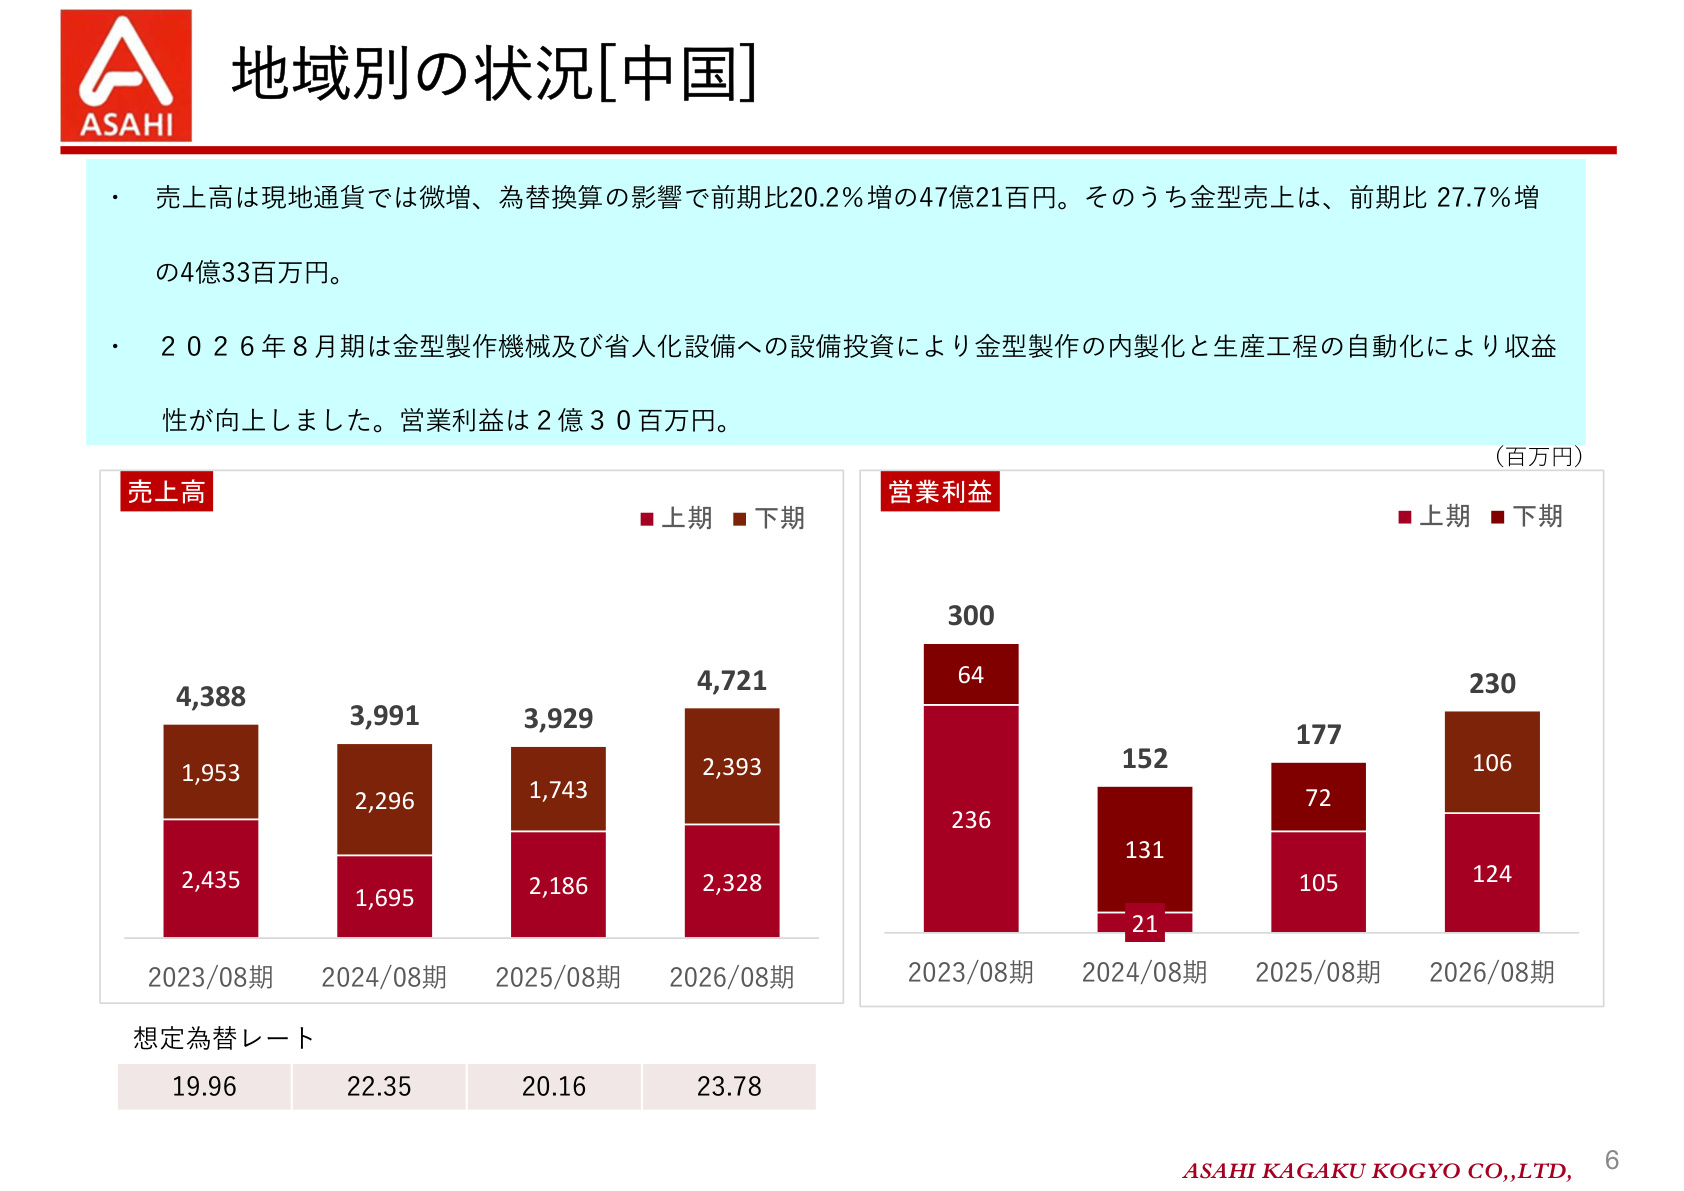
The following slide shows the performance trend of the Chinese base, which strongly supports the consolidated earnings.
Importance and Background of the China Slide
The Chinese base (Asahi Plastic (Kunshan) Co., Ltd.) is the core engine for profit generation for the entire group. It achieved significant growth in both sales and profit, with net sales of 4.721 billion yen (up 20.2% YoY) and an operating profit of 230 million yen (up 29.9% YoY) . The shift in the assumed exchange rate from 20.16 yen per yuan in the previous year to 23.78 yen also boosted yen-denominated sales, but the company also secured a slight increase in local currency terms.
Of particular note is the growth in mold sales , which reached 433 million yen (up 27.7% YoY) . By actively investing in mold manufacturing machinery and labor-saving equipment, the company has advanced the in-house production of molds and the automation of production processes, leading to a dramatic improvement in profitability. The structure where the significant profits from the Chinese business compensate for the losses in the domestic business has become clear.
Thailand Business: Maintaining High Utilization and Path to Profitability
- Net Sales : 944 million yen (up 3.5% YoY)
- Operating Profit : Operating loss of 12 million yen (compared to an operating profit of 6 million yen in the previous year)
Although sales decreased in local currency terms, the impact of exchange rate conversion (assumed rate changed from 4.44 yen to 4.88 yen per baht) resulted in an increase in yen terms. The current factory utilization rate remains high at 90% . Although the full-year result turned into a loss, the operating loss for the second half alone narrowed to 4 million yen (compared to an 8 million yen loss in the first half), and the company is promoting new order acquisition through active sales activities while maintaining high utilization.
5. Progress of the Medium-Term Management Plan (FY2026–FY2028)
The company is pursuing a medium-term management plan themed " Strengthening Global Competitiveness and Human Resource Development ." In the first year, FY2026, progress was made in the following four priority areas:
- Technician Development :
- Acquisition of injection molding technician certifications in Japan (one person acquired Grade 2, and plant tours for clients were conducted).
- Trial of an internal qualification system in China and participation in external seminars in Thailand.
- Productivity Improvement :
- Promotion of automated equipment introduction in production processes.
- Achieved a gross profit margin of 10.4% and an ordinary profit margin of 1.1% .
- Continued consideration of M&A for overall group optimization.
- Profit Margin Improvement :
- Launched sales of the new construction material product "Gokubi Komachi" in April 2026.
- Developed and sold proprietary products, updated aging equipment for higher value-added production, and implemented inventory reduction measures.
- Sustainability Promotion :
- Achieved a 100% childcare leave acquisition rate in Japan .
- The number of female managers across the group is 6 (progressing toward the target of 7).
- Initiated studies on installing solar power generation equipment in Japan and aiming for zero carbon dioxide emissions.
6. Shareholder Return Policy: Stable Dividends and Minimum Dividend Setting
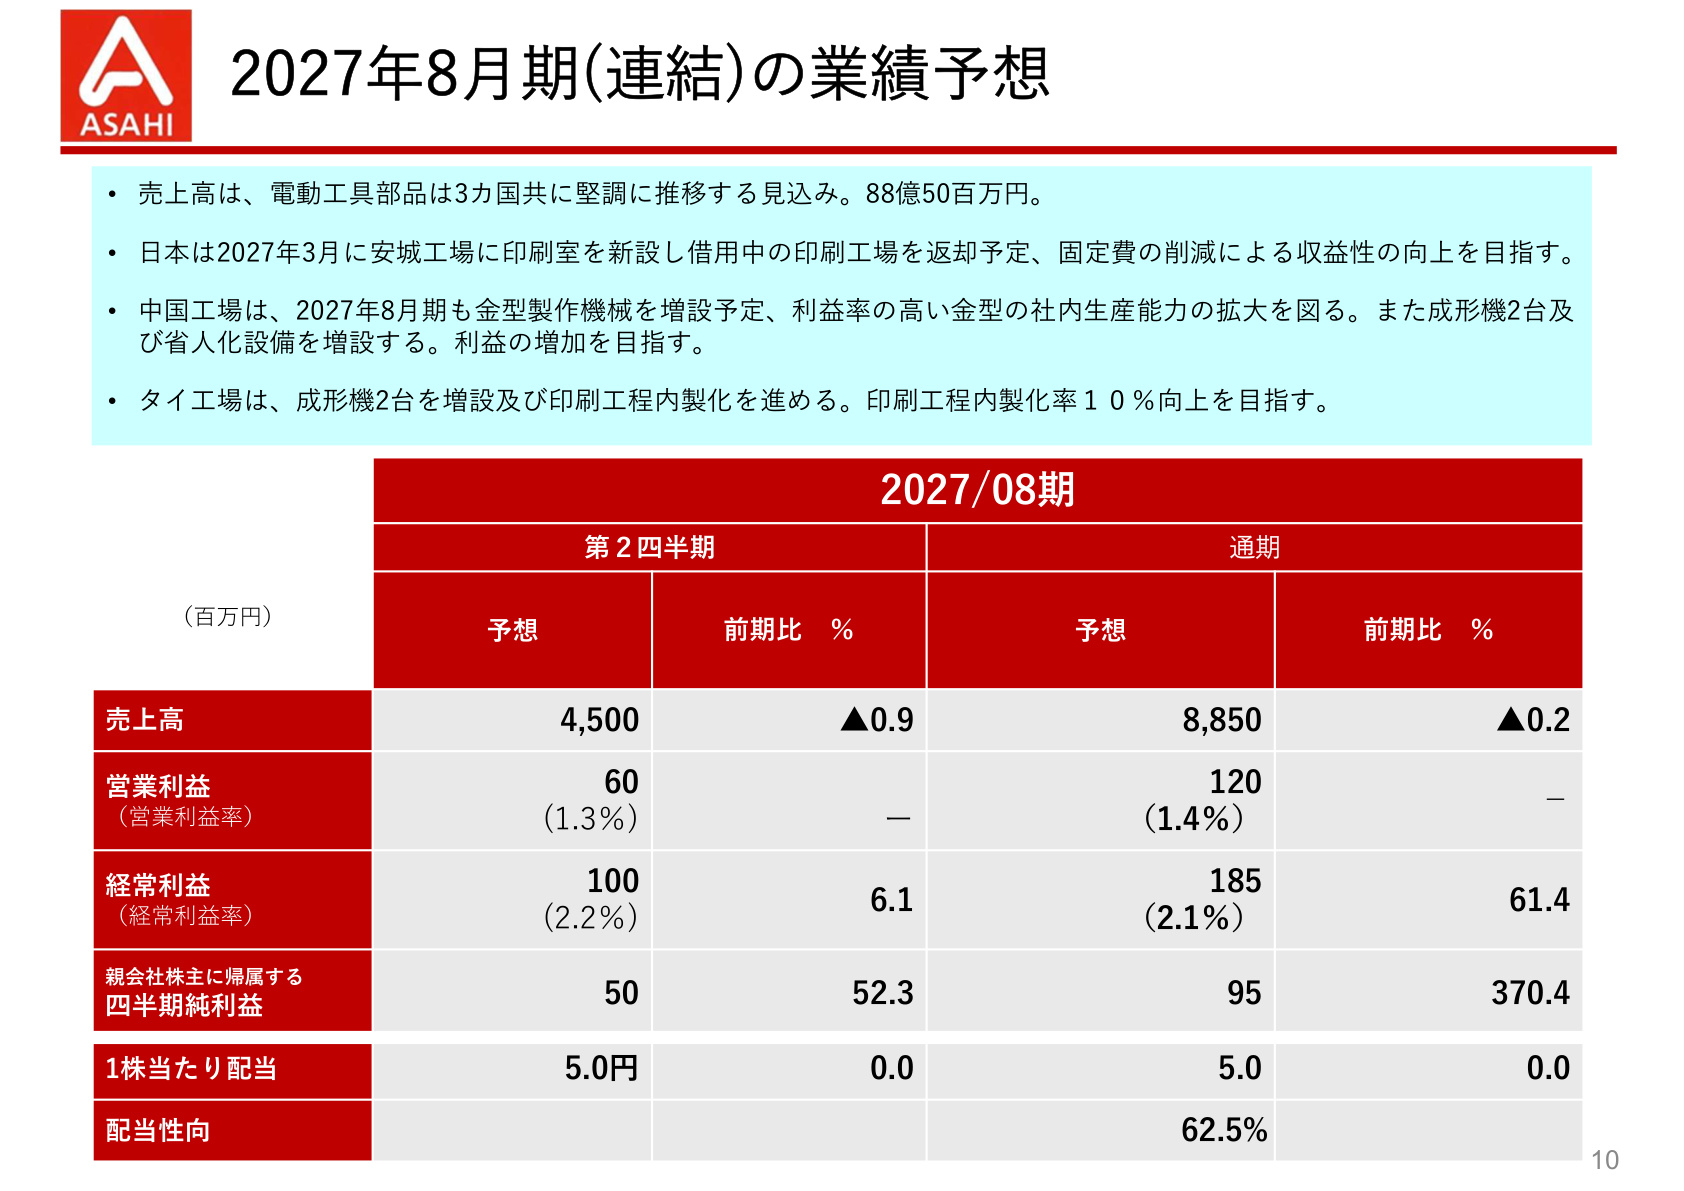
While maintaining a solid financial base and considering the balance between future growth investments and shareholder returns, the company has a basic policy of a 30% dividend payout ratio . Furthermore, starting from FY2024, the company has set a minimum annual dividend of 10.0 yen , clarifying its stance on providing stable returns regardless of performance fluctuations. The actual dividend for FY2026 was 10.0 yen per share (5.0 yen interim, 5.0 yen year-end) , maintaining the minimum dividend. For the next fiscal year (FY2027), the company has disclosed a dividend forecast of 10.0 yen per year (payout ratio of 62.5%).
7. FY2027 Performance Outlook and Priority Strategies
The following slide shows the consolidated performance forecast for Asahi Kagaku Kogyo for FY2027.
Outlook and Strategic Measures
As this slide shows, for FY2027, the company expects net sales to remain flat at 8.85 billion yen (down 0.2% YoY) , while planning significant improvements in each profit item:
- Operating Profit : 120 million yen (up 172.7% YoY / approx. 2.7x)
- Ordinary Profit : 185 million yen (up 61.4% YoY)
- Full-year Forecast for Net Profit Attributable to Owners of the Parent : 95 million yen (up 370.4% YoY / approx. 4.7x)
The background to the significant profit growth despite the assumption of a slight decrease in sales lies in the thorough reduction of fixed costs at each base and the expansion of in-house production .
Priority Measures by Base
- Japan Base : Plans to establish a new printing room at the Anjo Plant in March 2027 and return the currently leased printing factory. This aims for a fundamental reduction in fixed costs and a turnaround in the profitability of the domestic business.
- China Base : Plans to increase mold manufacturing machinery to expand in-house production capacity for high-margin molds . In addition, two molding machines and labor-saving equipment will be added to further accumulate profits.
- Thailand Base : Plans to add two molding machines and promote the in-house production of the printing process, aiming for a 10% improvement in the in-house printing process ratio .
8. Summary and Future Monitoring Points
FY2026 was a year in which Asahi Kagaku Kogyo laid the groundwork for structural improvement, recovering consolidated operating profitability as automation and in-house mold production bore fruit at the Chinese base. The solid financial foundation backed by a 77.7% equity ratio and the 10-yen minimum dividend policy support management stability.
Key points to monitor moving forward include how much the fixed cost reduction from the new printing room (scheduled for March 2027) and the return of the warehouse in Japan will contribute to narrowing the deficit , and whether the addition of molding machines and in-house production measures in China and Thailand will lead to the achievement of the planned 120 million yen in operating profit .
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.