

Ringer Hut Q2 FY2027 Earnings Analysis: 41.6% Operating Profit Growth Driven by Successful Price Revisions and Cost Optimization; Progress Toward Mid-Term Plan
Sentiment Analysis
Introduction
Based on the Supplementary Materials for the Q2 FY2027 (Interim) Financial Results released by Ringer Hut Co., Ltd., this report outlines the company's financial performance, store trends, progress in cost structure reform, and future growth strategies.
During the first half of the fiscal year, despite facing a challenging business environment characterized by persistently high raw material and energy costs, the company achieved significant growth in operating profit . This was driven by the successful penetration of price revisions implemented in the previous fiscal year, strong sales of core products, and disciplined cost management. This report provides a multi-faceted analysis of the key indicators and long-term management policies presented in the materials.
1. Q2 FY2027 Earnings Highlights
Consolidated performance for the first half exceeded both the previous year's results and the company's initial internal plans in terms of both revenue and profit.
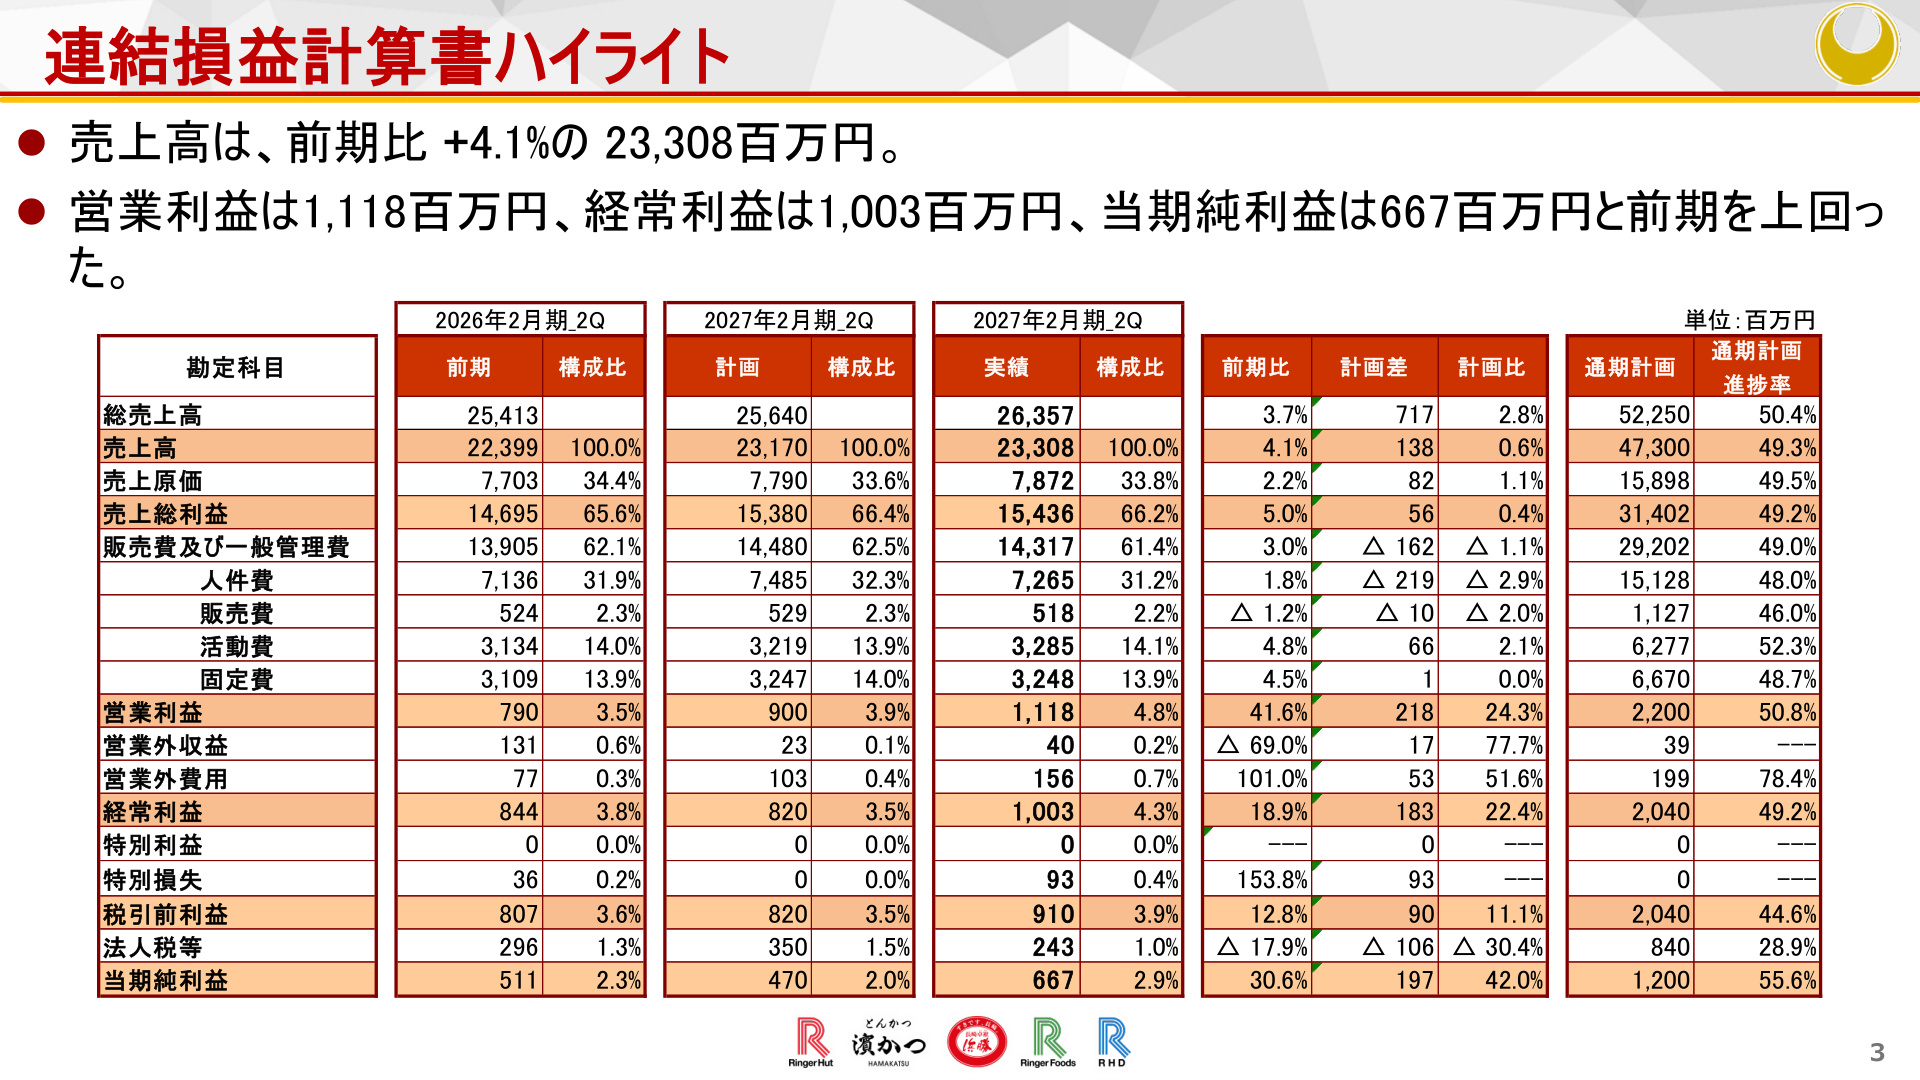
As shown in the slide above, both revenue and profit at each stage have outperformed the previous year's results and the initial forecasts. Key highlights are as follows:
- Net Sales : ¥23,308 million (+4.1% YoY, +¥138 million / +0.6% vs. plan)
- Operating Profit : ¥1,118 million (+41.6% YoY, +¥218 million / +24.3% vs. plan)
- Ordinary Profit : ¥1,003 million (+18.9% YoY, +¥183 million / +22.4% vs. plan)
- Interim Net Profit : ¥667 million (+30.6% YoY, +¥197 million / +42.0% vs. plan)
Progress toward the full-year forecast (operating profit of ¥2,200 million) is steady, with net sales at 49.3% , operating profit at 50.8% , and net profit at 55.6% , all reaching or exceeding the halfway mark by the end of the interim period.
2. Sales Trends and Existing Store KPI Analysis
Group-wide store sales, including franchise (FC) stores, increased by 3.6% YoY (¥24,753 million). This growth was primarily driven by the expansion of existing store sales (+¥920 million, +3.9% YoY) .
Existing Store Trends by Core Segment (H1)
- Ringer Hut (Champon Business) : Sales +4.5% YoY
- Customer Traffic: +0.4%
- Average Spend per Customer: +4.1%
- Hamakatsu (Tonkatsu Business) : Sales +0.9% YoY
- Customer Traffic: -0.2%
- Average Spend per Customer: +1.2%
Average spend per customer has continued to rise following the price revisions implemented in February 2026. While price hikes often raise concerns about customer attrition, the Ringer Hut segment successfully increased unit prices while maintaining customer traffic at or above previous year levels (+0.4%) through the introduction of seasonal and strategic products and effective promotional campaigns. In the "Hamakatsu" segment, although traffic dipped in August due to the reactionary impact of the "Summer Value Bag" promotion from the previous year, the segment maintained positive growth overall due to higher unit prices.
3. Cost Structure and Profit Improvement Mechanism
The significant increase in operating profit from ¥790 million in the previous year to ¥1,118 million (+¥328 million) was driven not only by revenue growth but also by the containment of both the cost of sales ratio and the SG&A expense ratio.
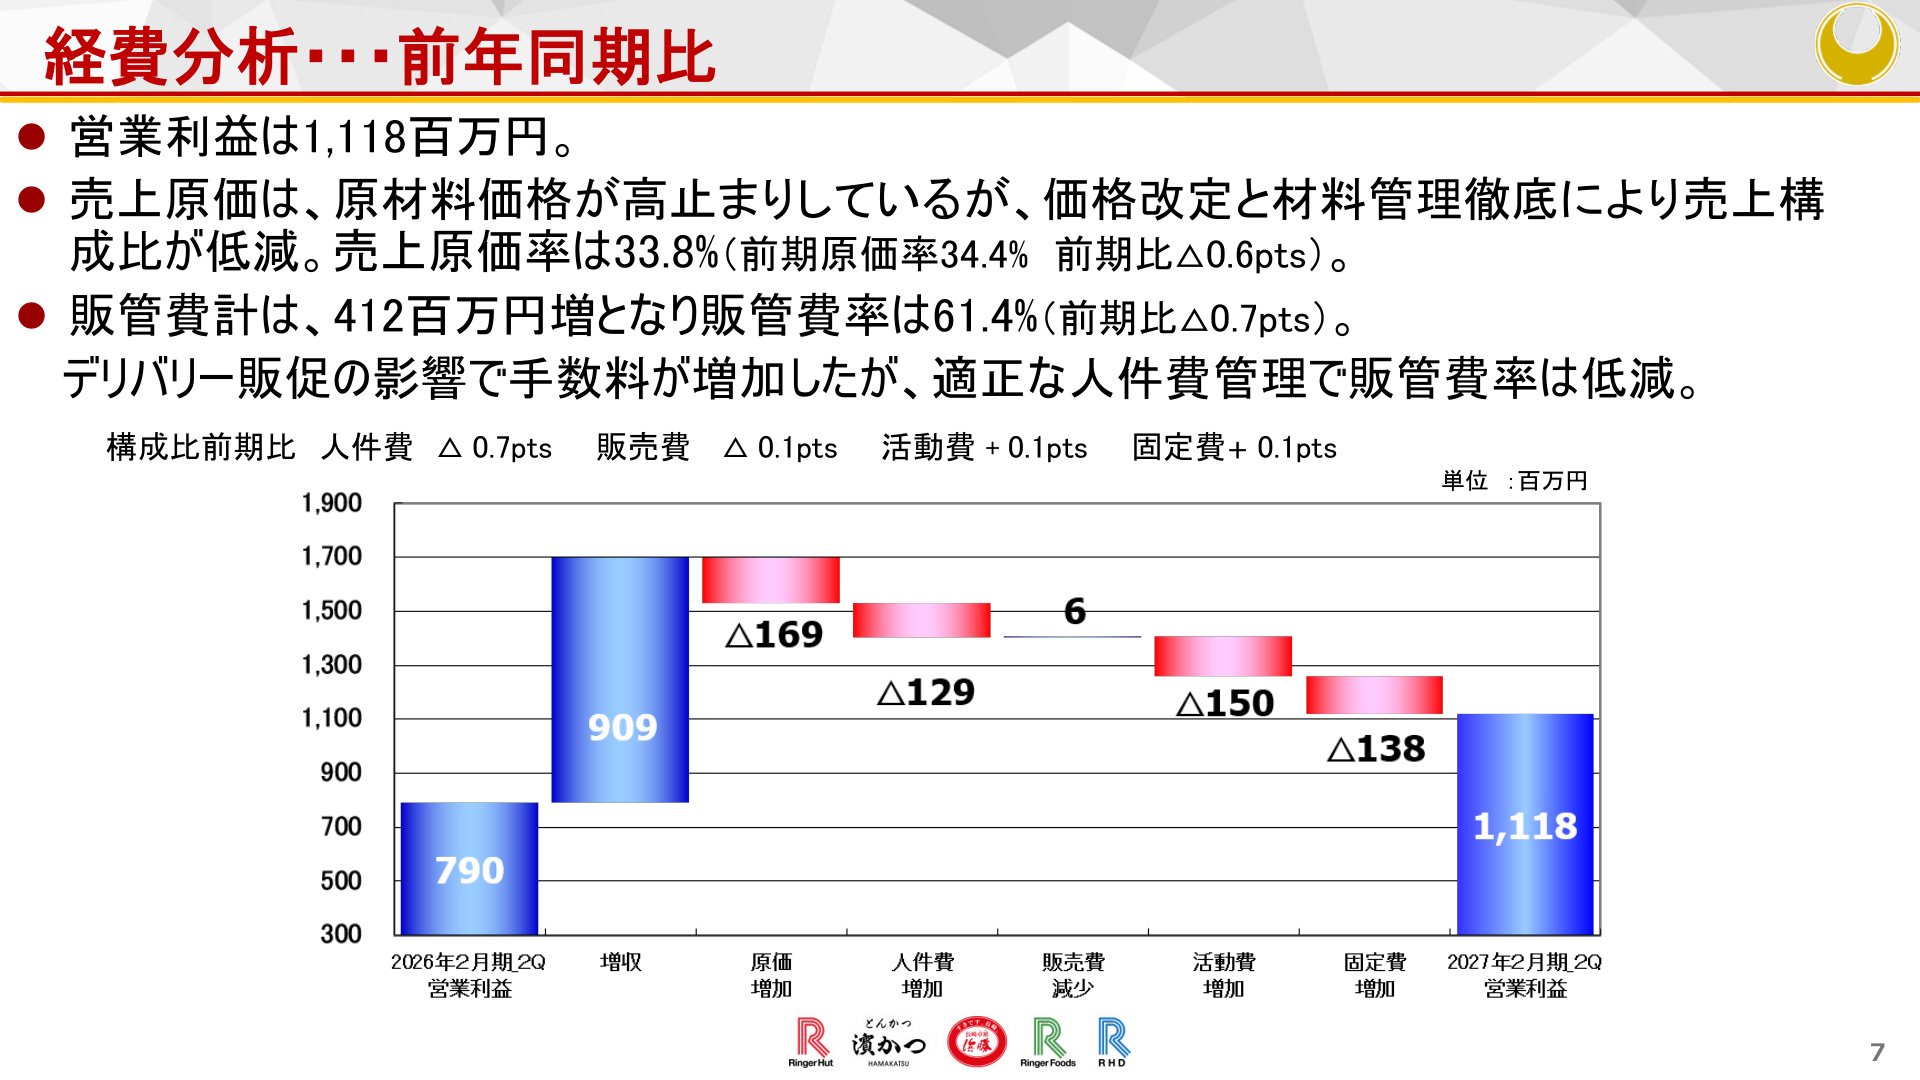
The slide above visually breaks down the factors contributing to the change in operating profit. The key structural changes are summarized in the following three points:
- Improvement in Gross Profit Margin : Despite the environment of high raw material prices, the effect of price revisions and thorough material management at the store level reduced the cost of sales ratio to 33.8%, a 0.6 percentage point improvement from the previous year (34.4%) .
- Rigorous Labor Cost Management : While delivery-related commissions and activity expenses increased (+¥150 million), optimized staffing and store operation management led to a 0.7 percentage point reduction in the labor cost ratio (31.2%) . Consequently, the overall SG&A ratio improved to 61.4% (down 0.7 percentage points YoY) .
- Leverage Effect from Revenue Growth : The revenue growth primarily from existing stores (+¥909 million) was sufficient to absorb various cost increases (raw materials +¥169 million, labor +¥129 million, activity expenses +¥150 million, fixed costs +¥138 million), resulting in a net expansion of operating profit.
4. Segment Performance and Financial Position
Both the Champon and Tonkatsu businesses recorded increases in both revenue and profit.
- Champon Business (Ringer Hut) :
- Net Sales: ¥19,093 million (+¥827 million YoY)
- Operating Profit: ¥940 million (+¥346 million YoY)
- Operating Profit Margin: 4.9% (+1.7 percentage points from 3.3% YoY)
- Tonkatsu Business (Hamakatsu/Takufuku Hamakatsu) :
- Net Sales: ¥4,088 million (+¥48 million YoY)
- Operating Profit: ¥169 million (+¥9 million YoY)
- Operating Profit Margin: 4.1% (+0.2 percentage points from 4.0% YoY)
The recovery in the profit margin of the core Champon business serves as the pillar supporting the group's overall performance improvement.
Cash Flow and Balance Sheet
In terms of cash flow, reflecting the effects of price revisions and increased profits, operating cash flow grew strongly to ¥1,574 million (+¥447 million YoY) . While investing cash flow was -¥1,137 million due to capital expenditures such as new store openings (¥1,025 million), the company secured a positive free cash flow of ¥437 million (+¥269 million YoY) . On the balance sheet, cash and deposits increased to ¥3,255 million, and the equity ratio remained at a healthy level of 48.6% (down 0.3 percentage points from the end of the previous fiscal year).
5. Full-Year Forecast and Shareholder Returns
Given the uncertainty in the external environment, such as rising raw material and utility costs, the company has maintained its full-year consolidated earnings forecast for FY2027 .
- Net Sales : ¥47,300 million (+4.9% YoY)
- Operating Profit : ¥2,200 million (+55.1% YoY)
- Ordinary Profit : ¥2,040 million (+27.6% YoY)
- Net Profit : ¥1,200 million (-30.5% YoY)
The year-on-year decrease in net profit is due to the reactionary impact of one-time factors from the previous year. Operating profit, which indicates the core earning power of the business, is projected to grow by a high 55.1%.
Regarding shareholder returns, reflecting the strong interim performance, the company has decided to increase the interim dividend by ¥1 from the initial forecast of ¥6 to ¥7 per share . Combined with the projected year-end dividend of ¥7, the annual dividend forecast is ¥14 (compared to ¥13 in the previous year), representing a planned dividend increase.
6. Mid-Term Management Plan and Growth Strategy Outlook
To achieve sustainable growth, the company has established long-term management goals and specific measures.
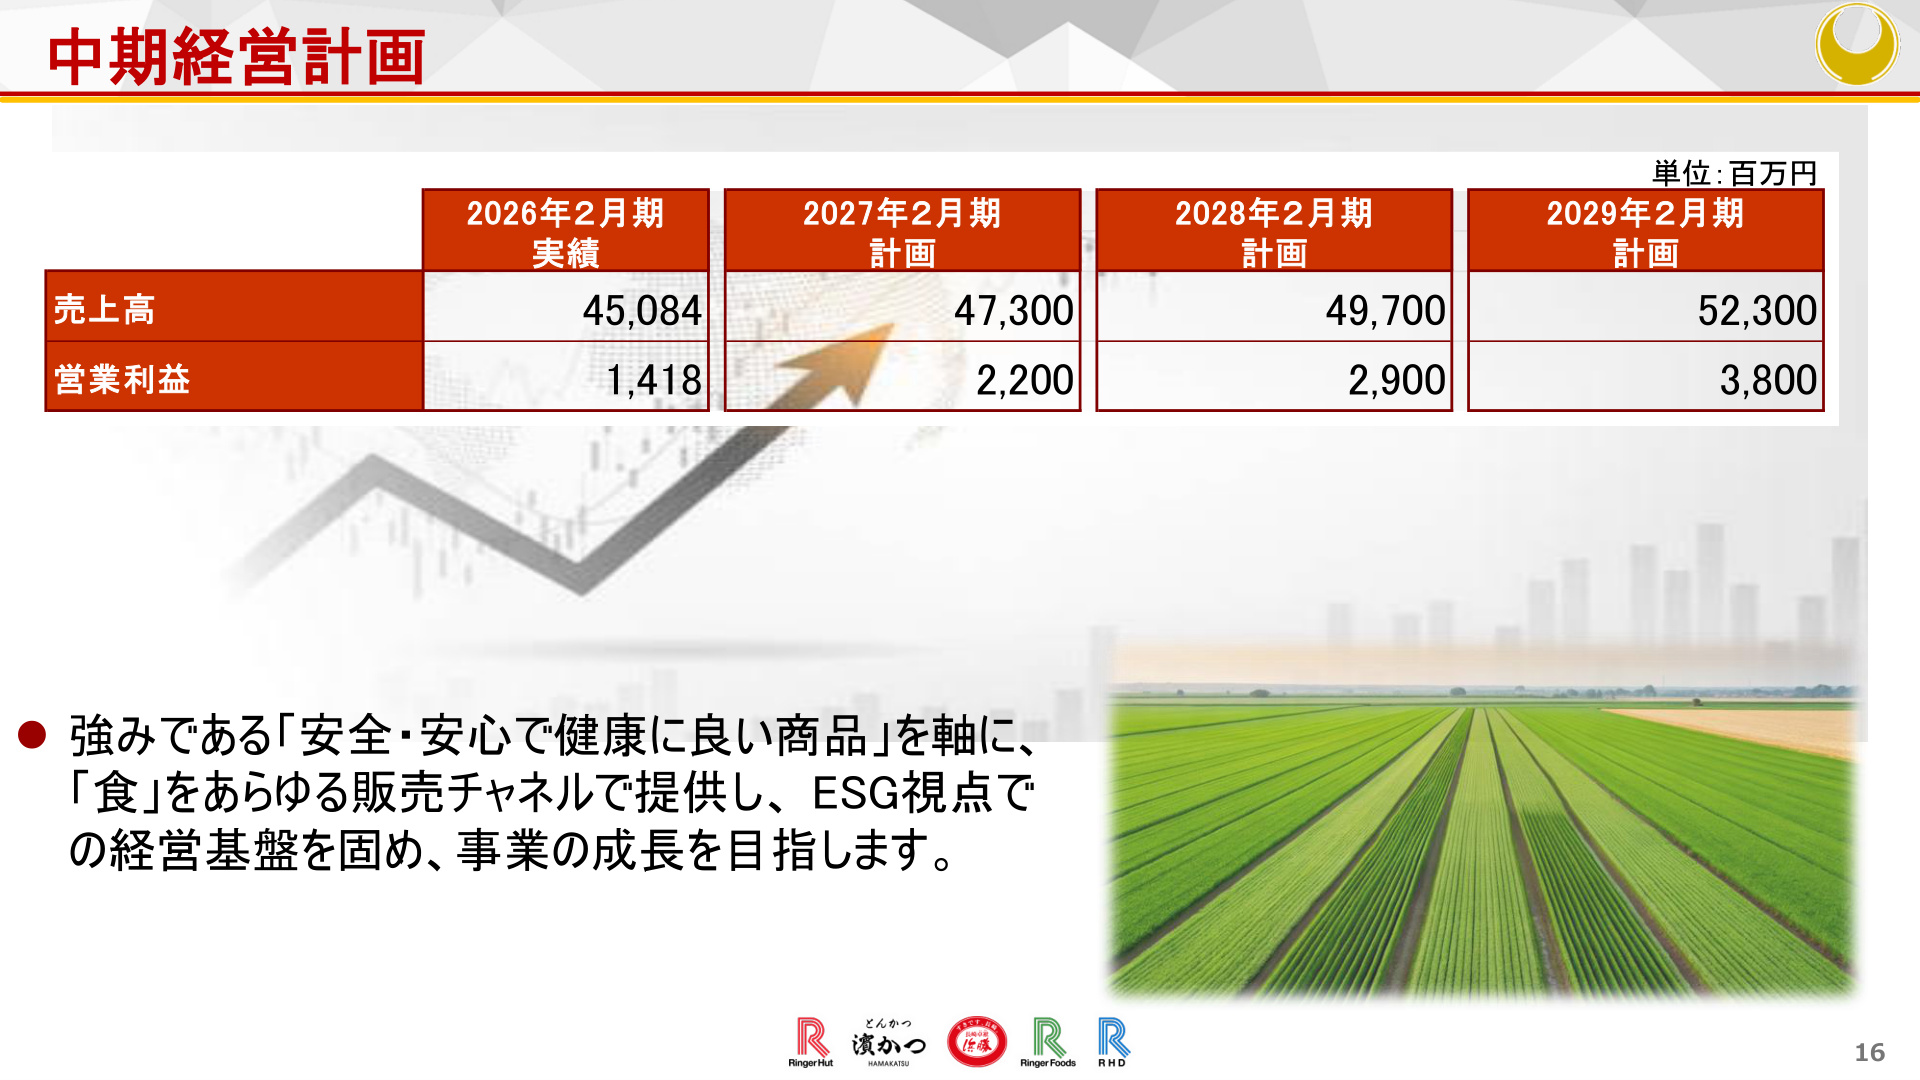
As shown in the slide above, the mid-term management plan outlines a trajectory for revenue and profit expansion through FY2029.
- FY2026 (Actual) : Sales ¥45,084 million / Operating Profit ¥1,418 million
- FY2027 (Plan) : Sales ¥47,300 million / Operating Profit ¥2,200 million
- FY2028 (Plan) : Sales ¥49,700 million / Operating Profit ¥2,900 million
- FY2029 (Plan) : Sales ¥52,300 million / Operating Profit ¥3,800 million
To achieve these targets, the company has outlined the following six specific measures :
- Establishment of Store Formats : Strengthening product development, re-entering the Kanto region with the Tonkatsu format, enhancing the delicatessen format, and promoting existing store renovations.
- Strengthening External Sales Business : Improving product quality to replicate store flavors, expanding the lineup, and strengthening production systems.
- Global Market Expansion : Increasing overseas store openings (5 stores planned for this fiscal year) and prioritizing investment in human resources and capital.
- Operational Efficiency and Human Resource Development : Streamlining store operations and administrative tasks, and promoting recruitment and training.
- Strengthening Procurement, Production, and Distribution : Stable procurement of domestic vegetables, increasing the in-house production ratio to reduce costs, and building efficient distribution networks.
- Promoting Sustainability : Food education activities, reducing environmental impact, and promoting diversity.
Regarding the store opening plan, 10 stores (7 domestic, 3 overseas) have already been opened in the first half, and the company plans to open another 10 (8 domestic, 2 overseas) in the second half, for a total of 20 store openings for the full year . The company is shifting toward a net increase phase while continuing "scrap and build" efforts, primarily in shopping center food courts.
Conclusion
In the first half of FY2027, Ringer Hut demonstrated a clear recovery in operating profit margin (from 3.5% to 4.8%) as the effects of price revisions manifested in higher average spend per customer, while maintaining customer traffic and managing costs effectively. Moving forward, attention will be focused on the second-half performance toward achieving the ¥2.2 billion operating profit target, as well as whether structural reforms—such as the re-entry into the Kanto region and the expansion of external and overseas businesses outlined in the mid-term management plan—can further drive earnings growth.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.