

Iriso Electronics FY2025 Results and FY2026 Outlook: Structural Transformation Amidst Radical Governance Reform and Record-High Sales
Sentiment Analysis
Iriso Electronics Co., Ltd. (Securities Code: 6908) disclosed its FY2025 Full-Year Financial Results on October 9, 2026. This disclosure is of critical importance, as it encompasses the findings of a third-party committee investigation into improper conduct, quality control issues, and accounting irregularities at overseas subsidiaries, the subsequent announcement of recurrence prevention measures and management restructuring, as well as the company's FY2025 performance and FY2026 full-year earnings forecast.
This report provides a detailed summary based on the disclosed materials, covering the overhaul of the governance structure, factors behind FY2025 performance, market-specific sales trends, and the growth strategy and profit outlook for FY2026.
1. Third-Party Committee Investigation Findings and Root Causes
The company established a third-party committee in April 2026 following allegations of improper payments at an overseas subsidiary (potential bribery of a judge regarding legal fees and cash payments to customs officials, etc.). During the investigation, which spanned approximately five months, issues related to "financial reporting and accounting (delayed closing, premature revenue recognition)" and "quality control and assurance (unapproved 4M changes, diversion/falsification of test data, and failure to conduct sampling inspections)" were also uncovered.
The root causes were identified as the following organizational issues:
- A corporate culture that prioritizes sales and delivery schedules over compliance, safety, and quality.
- A culture where it is difficult to speak up due to reliance on and deference to superiors.
- Lack of compliance awareness and training.
- Shortage of resources, including personnel, equipment, and skills, due to rapid business expansion.
- Weakness in governance and audit functions where checks and balances are insufficient.
2. Recurrence Prevention Measures and Clarification of Management Responsibility
To restore trust, the company has embarked on radical reforms that go beyond temporary corrective actions. It has codified "compliance, safety, and quality" as the highest standards of conduct and aims to instill a "Bad News First" culture to ensure the prompt sharing of unfavorable facts. Furthermore, the company is increasing personnel in under-resourced departments, reinforcing inspection equipment, and establishing a new Governance Promotion Department.
To clarify management responsibility, the replacement of the Representative Director and President and the abolition of the Honorary Chairman position were decided. Additionally, voluntary return of executive compensation was announced (the Representative Director and President will return 30% of their compensation for six months, while other directors will return 10% for three months).
3. FY2025 Consolidated Financial Summary: Record-High Sales
In FY2025, net sales reached 61.961 billion yen (up 9.9% YoY) , exceeding the initial forecast of 58 billion yen and marking a record high for full-year sales . Conversely, operating profit was 5.436 billion yen (down 0.2% YoY) , and net profit was 2.553 billion yen (up 1.6% YoY) , impacted by approximately 1.3 billion yen in extraordinary losses related to the third-party committee investigation.
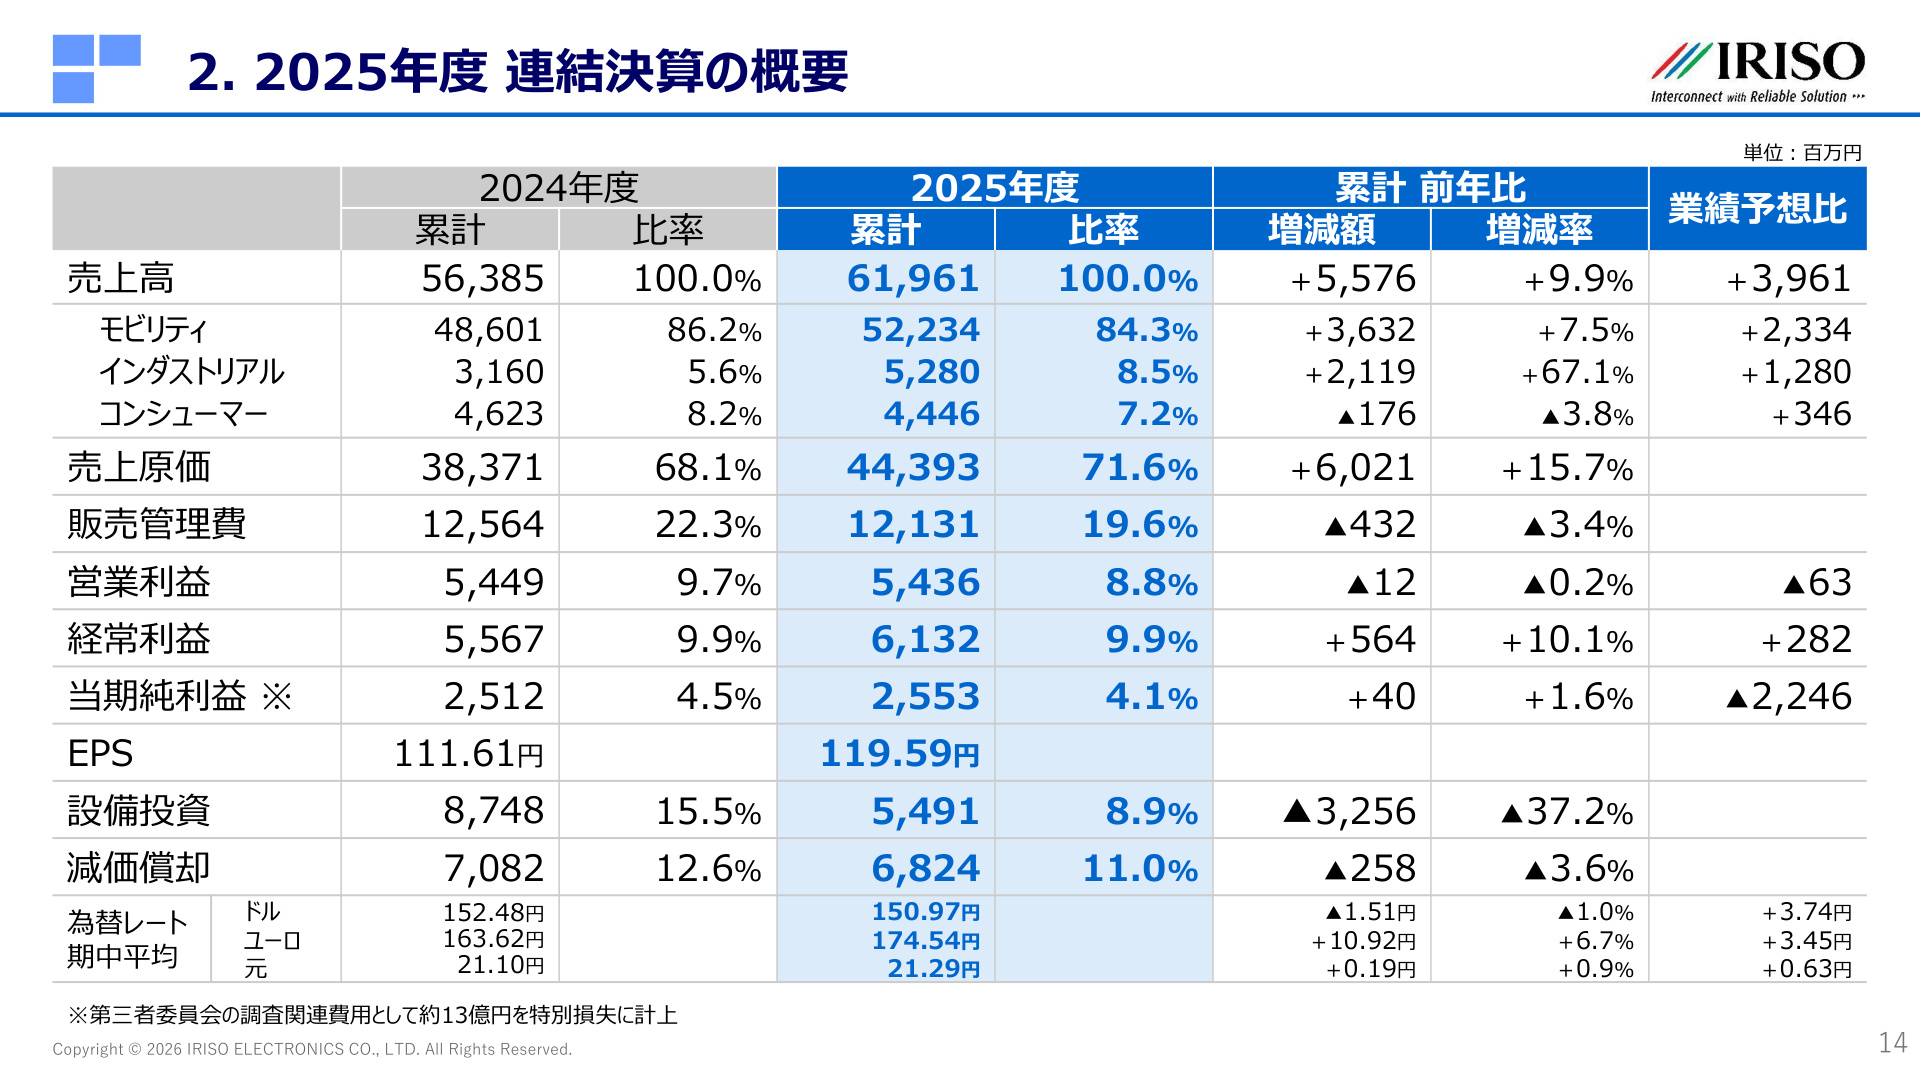
The slide above summarizes the FY2025 consolidated results and business segment breakdown. While sales were strong due to the expansion of the mobility and industrial markets, the cost of sales ratio rose to 71.6% (up 3.5 percentage points YoY) , reflecting a structure that is impacting profit margins.
4. Analysis of FY2025 Operating Profit Fluctuations
The factors behind the nearly flat operating profit (a decrease of 12 million yen) are as follows:
- Negative Factors :
- Increase in raw material costs (-2.2 billion yen) : Primarily driven by a 53% increase in gold prices compared to the previous year.
- Increase in expenses (-1.8 billion yen) : Including startup costs for the new Akita plant.
- Increase in labor costs (-500 million yen) and depreciation expenses (-500 million yen) .
- Positive Factors :
- Profit boost from sales volume changes (+2.4 billion yen) .
- Cost reduction and structural reform effects (+2.587 billion yen) .
Despite the burden of high raw material costs and upfront investments in the new plant, the company maintained an operating profit level comparable to the previous year through proactive cost-reduction activities and top-line growth.
5. Sales Trends by Market (FY2025)
Performance trends by market are as follows:
- Mobility Market (Sales: 52.234 billion yen, up 7.5% YoY) : This is the core segment, accounting for 84.3% of total sales. In the infotainment sector (22.505 billion yen, +6.0%), sales of high-speed transmission-compatible floating BtoB connectors for LCD panels, IVI, and ECUs remained solid. In the powertrain sector (14.546 billion yen, +12.9%), demand in the Chinese market remained firm, with increased sales of BMS connectors and "Z-Move™" vibration-resistant connectors for inverters.
- Industrial Market (Sales: 5.28 billion yen, up 67.1% YoY) : Achieved significant revenue growth due to a surge in demand for energy management equipment, alongside a partial recovery in FA-related equipment for Japanese customers.
- Consumer Market (Sales: 4.446 billion yen, down 3.8% YoY) : Experienced a decline in revenue compared to the previous year due to reduced demand, primarily for game consoles.
6. FY2026 Earnings Forecast: Revenue Growth Expected, but Profit to Decline Due to Compliance and Quality Normalization Investments
In the FY2026 full-year consolidated earnings forecast, the company expects net sales to reach 67 billion yen (up 8.1% YoY) , marking a record high for the second consecutive year. However, it projects a significant decline in profits, with operating profit at 3.5 billion yen (down 35.6% YoY) and net profit at 1.6 billion yen (down 37.3% YoY) .
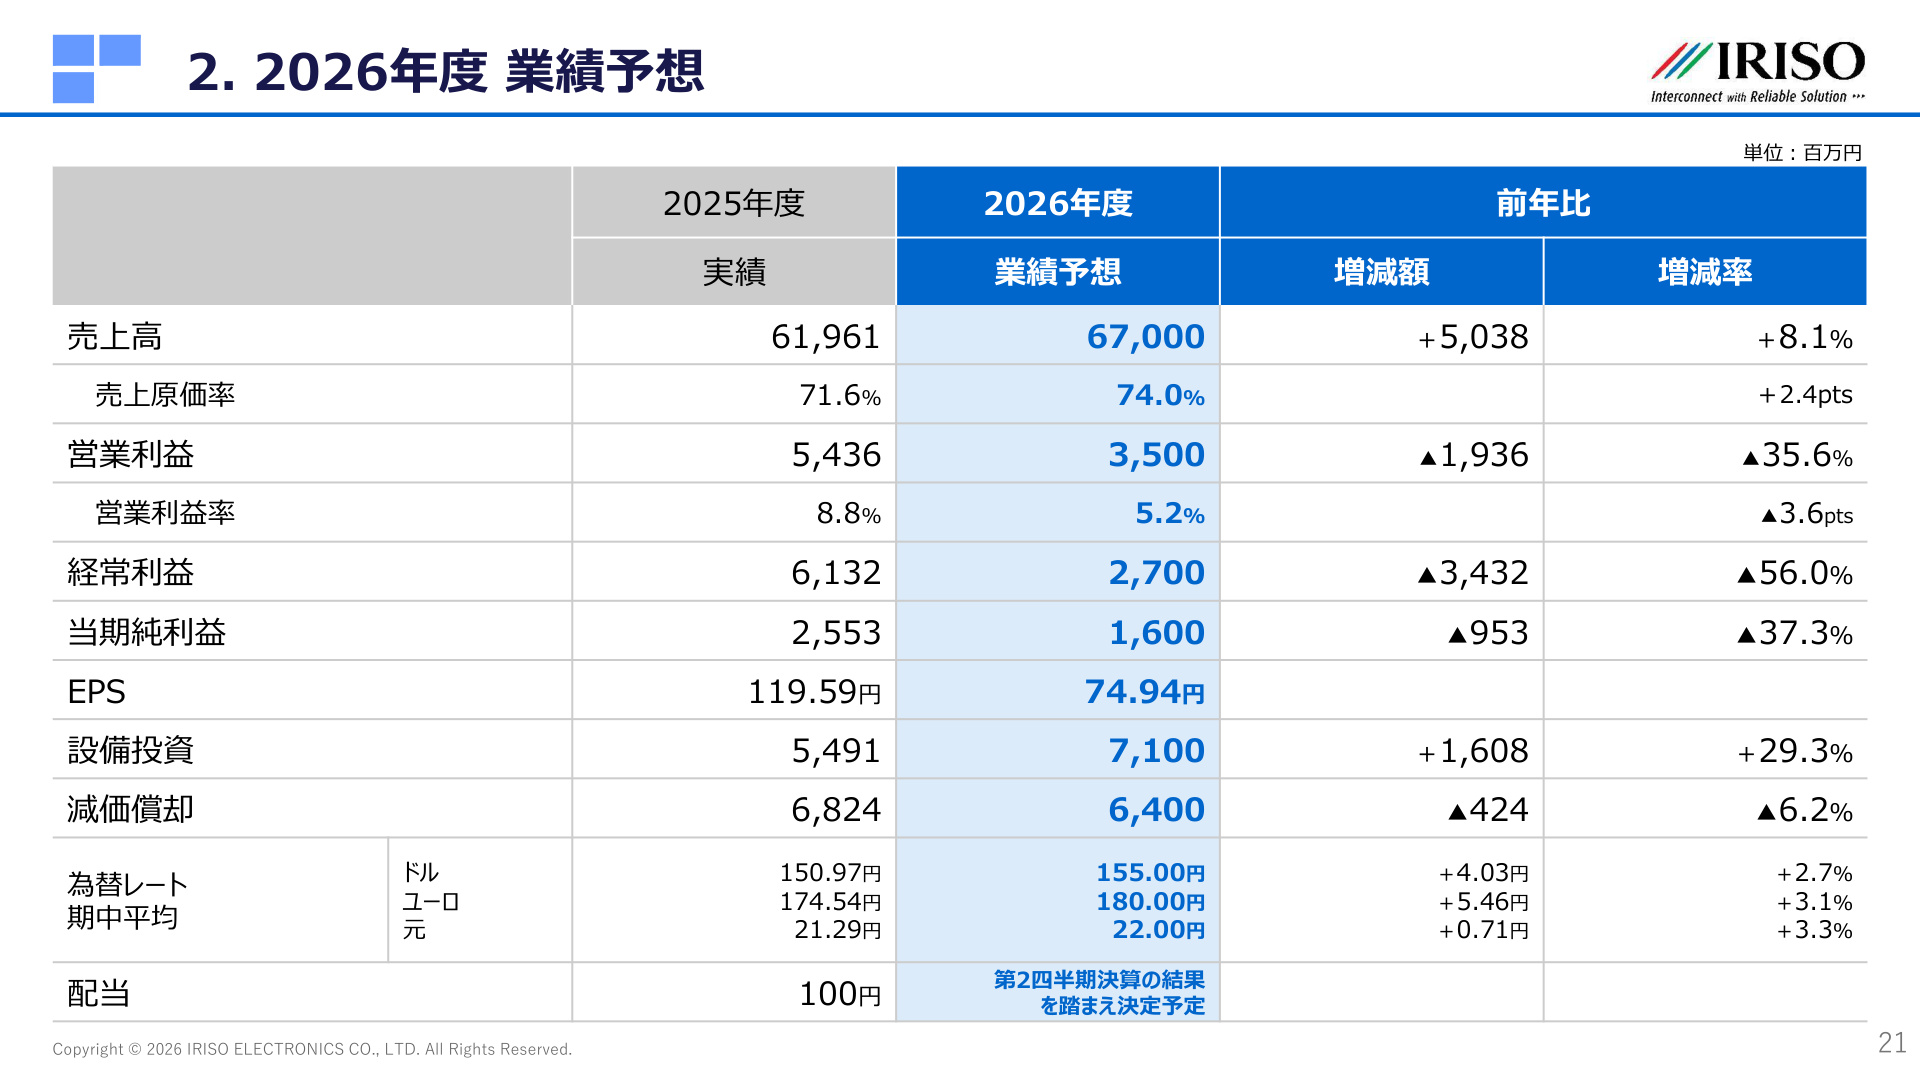
This plan indicates that the company has designated FY2026 as an "investment priority period to normalize compliance, safety, and quality." While top-line growth will be maintained, the profit plan incorporates temporary structural reform costs and risk factors.
7. Factors for FY2026 Operating Profit Decline
The breakdown of the main factors for the decrease in operating profit in FY2026 (a decrease of 1.936 billion yen YoY) is as follows:
- Further rise in raw material costs (-2.5 billion yen) : Assuming a +23% increase in gold prices and a +33% increase in copper prices.
- Increase in expenses (-1.05 billion yen) and increase in labor costs (-550 million yen) : Costs associated with implementing recurrence prevention measures, building a governance structure, and reinforcing quality testing equipment.
- Offset by sales growth (+1.2 billion yen) and cost reductions (+964 million yen) .
Despite pursuing top-line growth and cost-reduction activities, the company anticipates an operating profit margin of 5.2% (down 3.6 percentage points YoY) , factoring in high metal market prices and upfront costs for governance normalization. Dividend forecasts will be determined based on the results of the second-quarter financial results.
8. FY2026 Key Initiatives and New Market Development
Key initiatives for the second half of FY2026 and beyond have been clarified to restore corporate value and drive business growth over the medium to long term.
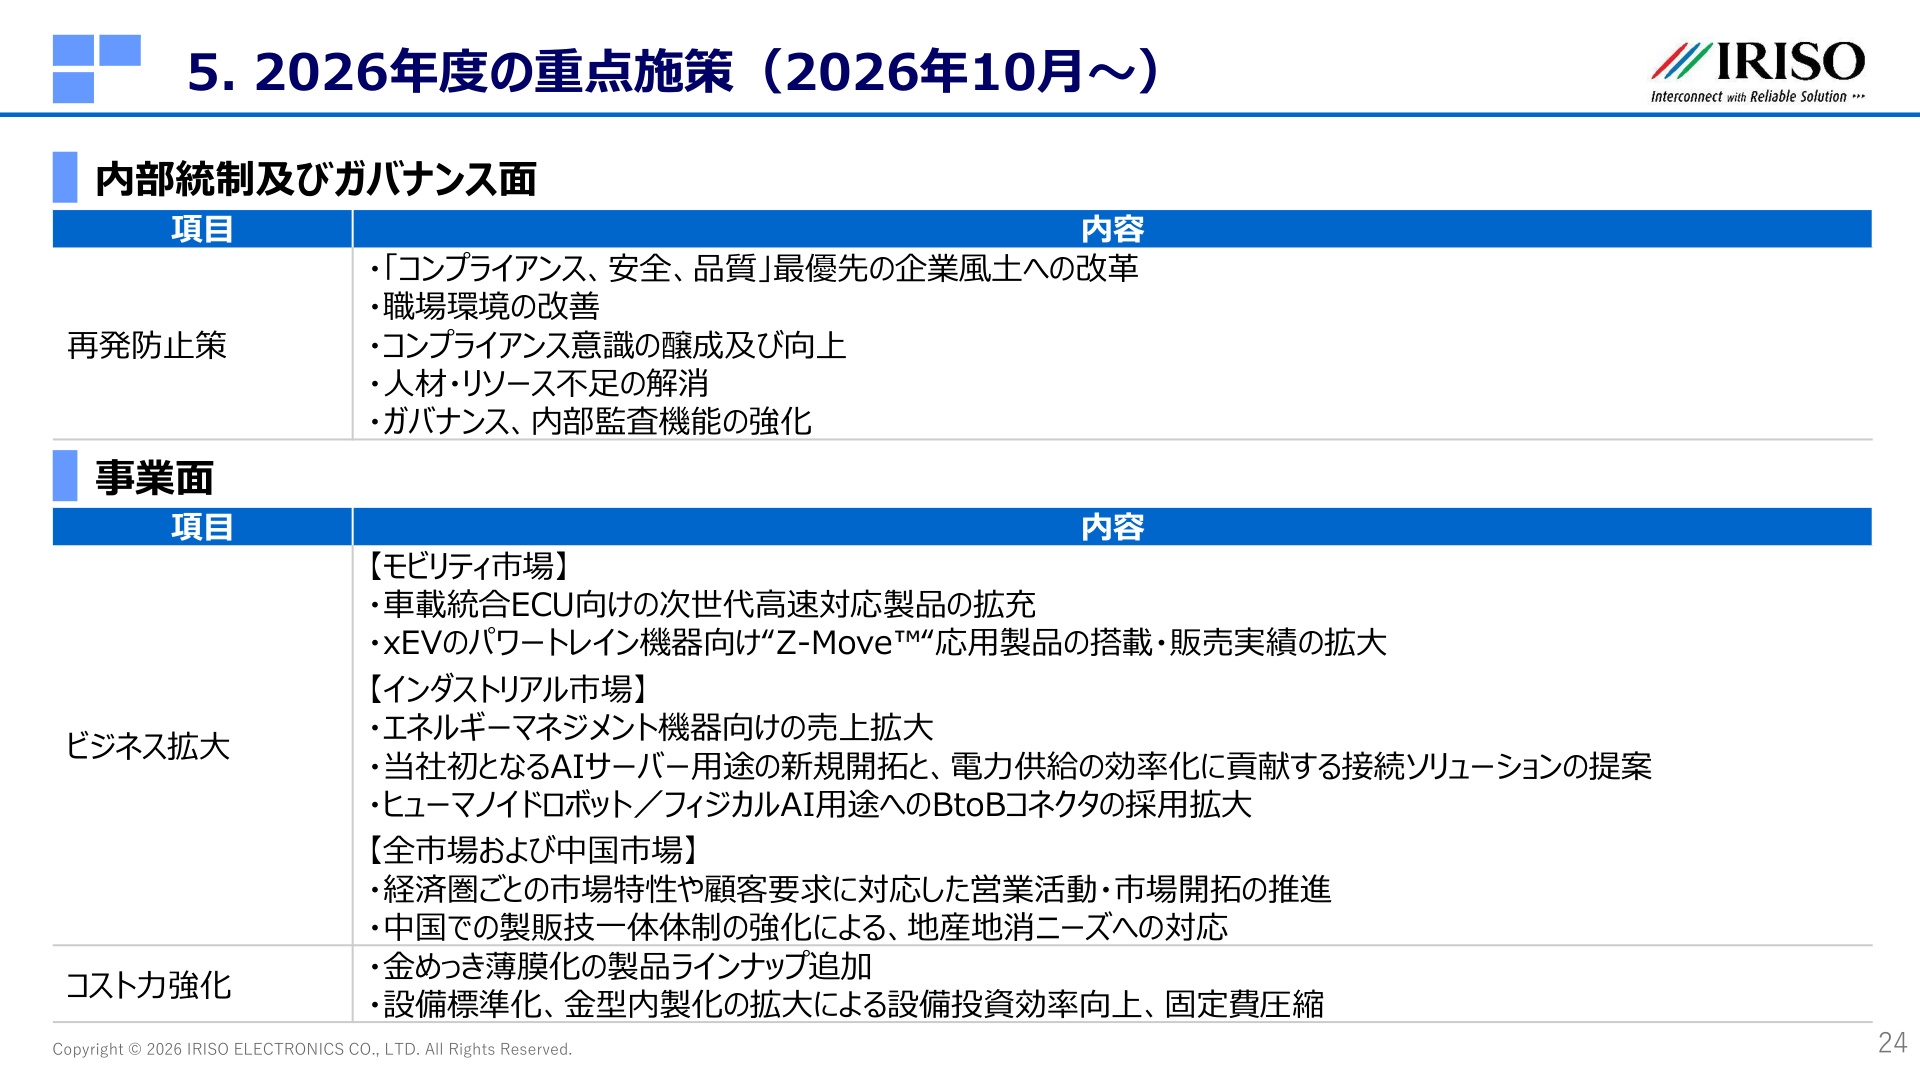
This slide is significant as it presents the completion of internal control reforms and growth strategies in next-generation markets as two sides of the same coin. Specific business focus areas are as follows:
- Deepening the Mobility Market : Expanding next-generation high-speed products for integrated automotive ECUs and increasing the adoption of "Z-Move™" vibration-resistant connectors for xEV powertrain equipment.
- Expanding the Industrial Market : In addition to strong demand for energy management equipment, the company will enter the AI server market for the first time , proposing power supply efficiency solutions. Furthermore, it will promote the adoption of BtoB connectors for humanoid robots and physical AI applications .
- Strengthening Global Structure and Cost Competitiveness : Responding to local production and consumption needs by strengthening the "integrated manufacturing, sales, and engineering system" in the Chinese market, adding thin-film gold plating products to the lineup, and improving investment efficiency through equipment standardization and increased in-house mold production.
Conclusion
While Iriso Electronics achieved record-high sales in FY2025 by capturing demand in the automotive and energy management equipment sectors, it has reached a major turning point in addressing issues related to governance and quality assurance. In FY2026, the company will concentrate management resources on recurrence prevention and organizational reform. While anticipating a temporary decline in profits, the company remains committed to expanding into cutting-edge fields such as AI servers and robotics.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.