

NPC Incorporated FY2026 Earnings Analysis & New Mid-Term Management Plan: A Deep Dive into the Rebound Scenario Driven by Perovskite and Recycling Technologies
Sentiment Analysis
Executive Summary
NPC Incorporated (TSE: 6255) reported FY2026 results where, despite revenue falling short of both initial forecasts and the previous year's figures, operating profit exceeded initial expectations due to rigorous cost-reduction efforts. The revenue shortfall was not caused by a loss of demand, but primarily by "timing mismatches in inspection/acceptance" for large-scale domestic projects and key orders from First Solar. Consequently, the order backlog has accumulated to 7.421 billion yen (up 10.4% YoY) , which will be carried over into the next fiscal year.
Concurrent with these results, the company unveiled its new Mid-Term Management Plan covering FY2027 through FY2031. The central theme is to overcome the historical challenge of "high earnings volatility due to reliance on specific customers" and establish a foundation for sustainable growth. The roadmap targets 15.55 billion yen in revenue and 3.295 billion yen in operating profit (a new record high) by FY2031, driven by three pillars: mass-production readiness for perovskite solar cell manufacturing equipment , horizontal expansion of solar panel recycling equipment ahead of impending legislation, and the rapid scaling of FA (Factory Automation) equipment to capture semiconductor and electronic component markets.
1. Analysis of FY2026 Financial Results
Performance Highlights and P&L Structure
Consolidated results for FY2026 were as follows:
- Revenue : 5.811 billion yen (down 37.3% YoY, 27.5% below initial forecast)
- Gross Profit : 2.025 billion yen (down 34.7% YoY, 3.7% above initial forecast)
- Operating Profit : 846 million yen (down 55.9% YoY, 11.3% above initial forecast)
- Ordinary Profit : 880 million yen (down 54.2% YoY, 14.9% above initial forecast)
- Extraordinary Loss : 177 million yen (valuation loss on unlisted shares of equity-method affiliate Gosan)
- Net Income Attributable to Owners of Parent : 481 million yen (down 63.7% YoY, 9.4% below initial forecast)
Background of Revenue Shortfall: "Timing Mismatches," Not Demand Loss
There are three clear factors behind the revenue decline from the initial forecast of 8.014 billion yen to 5.811 billion yen:
- Delays in Large Domestic Projects : Schedule slippage resulted in approximately 1.2 billion yen in revenue being pushed into FY2027.
- Postponement of First Solar Projects : Implementation of modification projects, conducted in parallel with large-scale equipment relocation, was delayed.
- Delays in Recycling Equipment Orders/Deliveries : Domestic orders were pushed back due to subsidy application schedules, shifting revenue to the next fiscal year.
Management emphasizes that these are not lost orders but rather physical execution and inspection timing shifts, posing no threat to the business foundation.
Significant Improvement in Profitability (34.8% Gross Margin)
While revenue fell short, operating profit exceeded the initial forecast by 11.3% due to a dramatic improvement in gross profit margin . Against an initial forecast of 24.4%, the actual result was 34.8% (a 10.4 percentage point improvement) . This was driven by:
- Favorable Product Mix : A higher ratio of high-margin projects such as relocations and modifications.
- Rigorous Cost Reduction : Expansion of global procurement for processed parts, leveraging economies of scale through bulk ordering of common components (control systems, inspection systems, etc.), and design optimization for materials, which account for roughly 70% of manufacturing costs.
The 177 million yen extraordinary loss relates to a valuation loss on shares of Gosan Tech, a venture partner in perovskite front-end technology. However, NPC has already secured orders exceeding the investment amount through this collaboration, limiting the actual negative impact on business operations.
2. Order Environment and Balance Sheet Health
Order Backlog Exceeds 7.4 Billion Yen
Although new orders in FY2026 were 6.509 billion yen (down 17.8% YoY) , the accumulation of delayed projects increased the year-end order backlog to 7.421 billion yen (up 10.4% YoY) .
- Solar Cell Manufacturing Equipment : First Solar relocation/modification, perovskite development equipment, front-end inkjet coating equipment, and domestic satellite solar cell manufacturing equipment.
- Solar Panel Recycling Equipment : Approximately 500 million yen in backlog (15 units including frame/J-Box separation, glass separation, EVA scrapers, and broken glass separation equipment).
- FA Equipment : Repeat orders for large-scale projects from major domestic electronic component manufacturers.
Financial Foundation and Share Buybacks
Total assets increased by 970 million yen year-on-year to 13.881 billion yen. Cash and deposits decreased to 3.597 billion yen due to upfront procurement for large domestic projects, while trade receivables and work-in-progress increased. On the liability side, advances received rose to 1.56 billion yen, securing cash flow for future revenue recognition. Additionally, as a capital efficiency measure, the company executed a share buyback of approximately 500 million yen (approx. 3.2% of total shares outstanding) .
3. Core of the New Mid-Term Management Plan: Overcoming Volatility and Shifting to High Growth
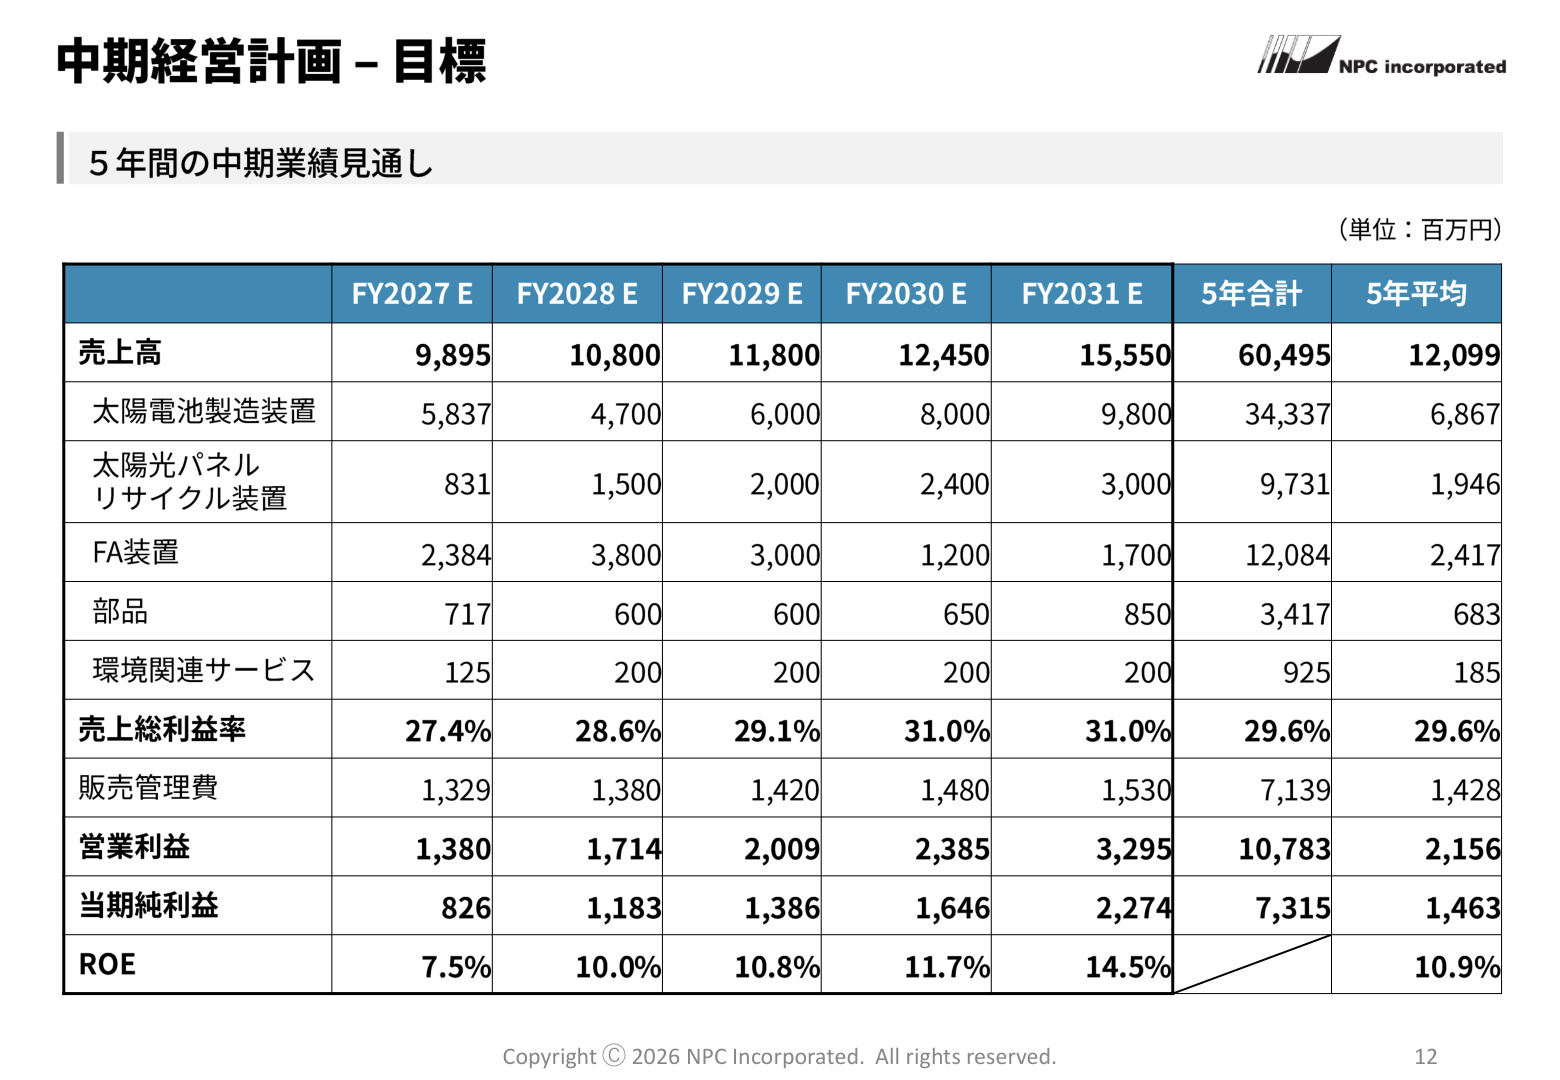
The following performance forecast data illustrates the overall picture of the new Mid-Term Management Plan.
Why This Slide Is Important
The slide above quantitatively and concretely outlines the roadmap for business portfolio transformation and profit expansion over the next five years. Historically, NPC’s performance was heavily influenced by the capital investment cycle of a single major customer (First Solar). This plan aims to grow total revenue to over 15.5 billion yen by expanding solar panel recycling equipment (from 830 million yen in FY2027 to 3 billion yen in FY2031) and FA equipment (from 2.38 billion yen to a peak of 3.8 billion yen) , alongside the sustainable growth of solar cell manufacturing equipment. It sets a path toward record-high levels of 3.29 billion yen in operating profit and an ROE of 14.5% .
Five Key Management KPIs
- Average Annual Revenue Growth Rate : 10% or higher (projected at 12.0% )
- Revenue Ratio Excluding First Solar : 60% or higher (projected at 70–75% )
- Gross Profit Margin : Maintain around 30% (5-year average projected at 29.6%)
- Investment Amount : Approx. 4 billion yen over 5 years
- Shareholder Return Policy : 25% Payout Ratio (Floor: 2% DOE)
This clearly demonstrates the intent to reduce reliance on specific customers—the primary cause of past earnings volatility—and build diverse growth engines.
4. Deep Dive into the Three Major Growth Areas
① Explosive Growth in Perovskite Solar Cell Manufacturing Equipment
NPC is establishing a unique position in "perovskite solar cells," the next-generation technology considered the key to decarbonization.
Why This Slide Is Important
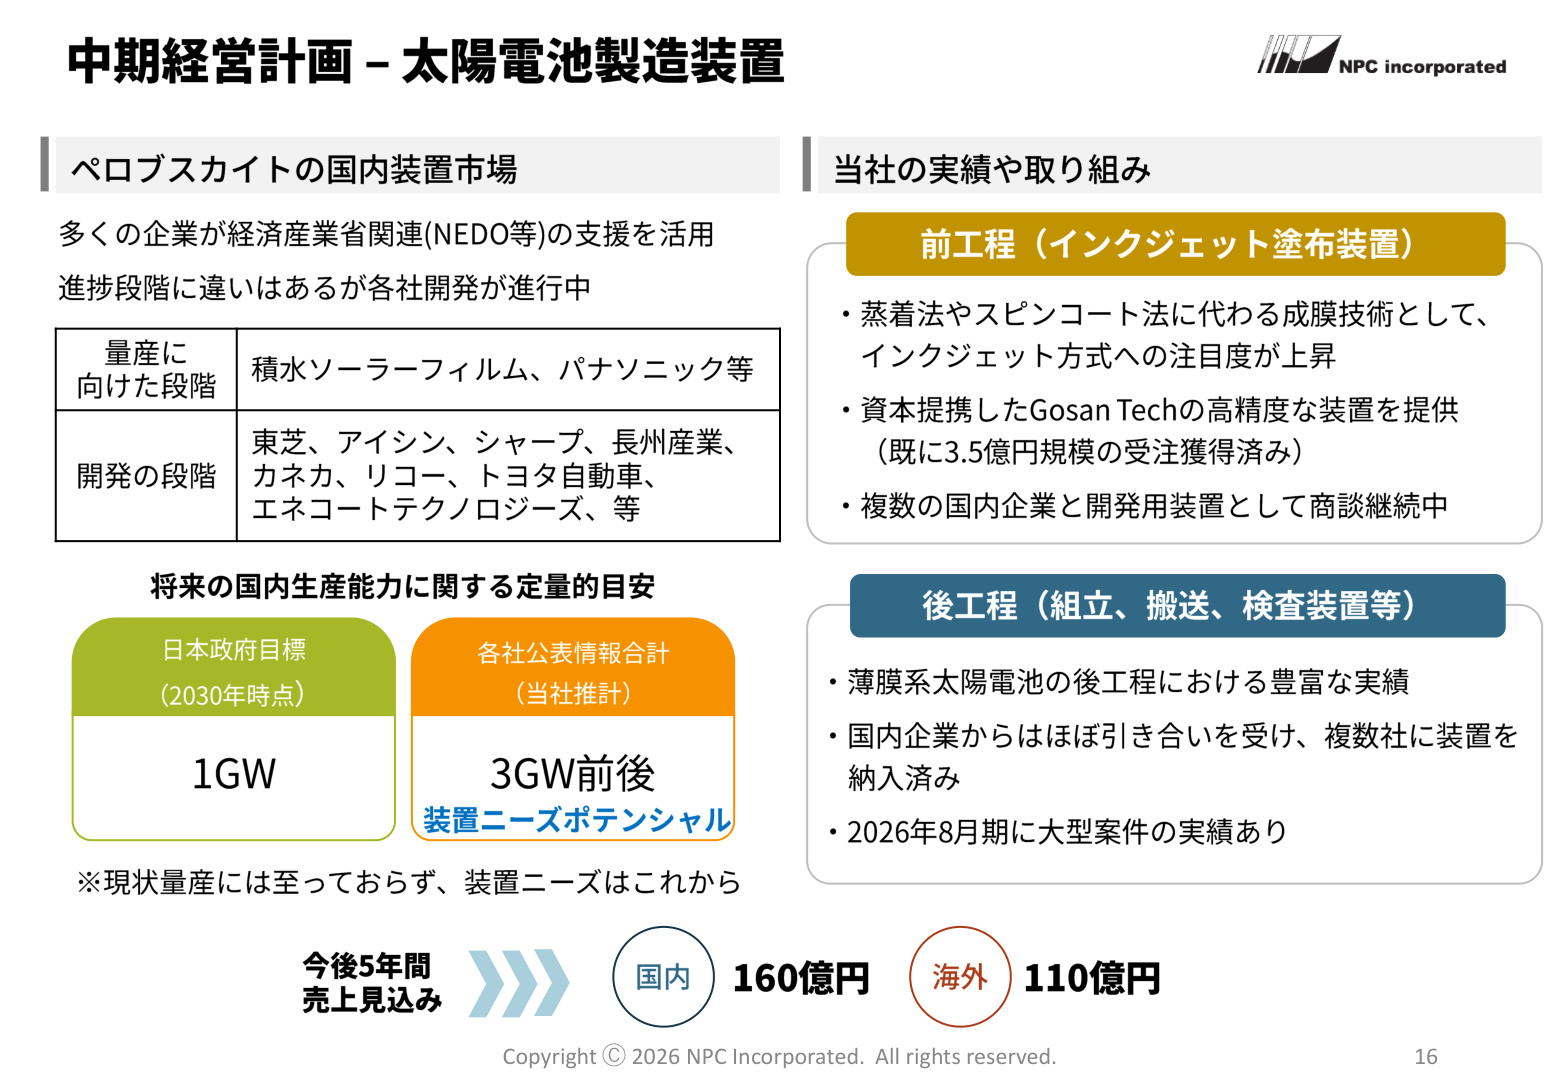
This slide specifies the market size the company expects to capture as the Japanese government targets 1GW of capacity by 2030, with domestic firms aiming for a total of around 3GW. The company expects 27 billion yen in total revenue over the next five years (16 billion yen domestic, 11 billion yen overseas) .
Notably, NPC has entered the front-end "inkjet coating equipment" market through collaboration with South Korean partner Gosan Tech, moving beyond its traditional strength in back-end processes (assembly, transport, inspection). This strengthens its approach to major domestic players like Sekisui Solar Film and Panasonic, enabling a full-lineup strategy. The company is also securing repeat orders from domestic customers supplying space-grade solar cells to Western satellite manufacturers, demonstrating its strength in high-end segments.
② Solar Panel Recycling Equipment: "Inevitable Demand" Driven by Legislation
NPC has established a solid first-mover advantage in the solar panel recycling market, which is entering an era of mass disposal.
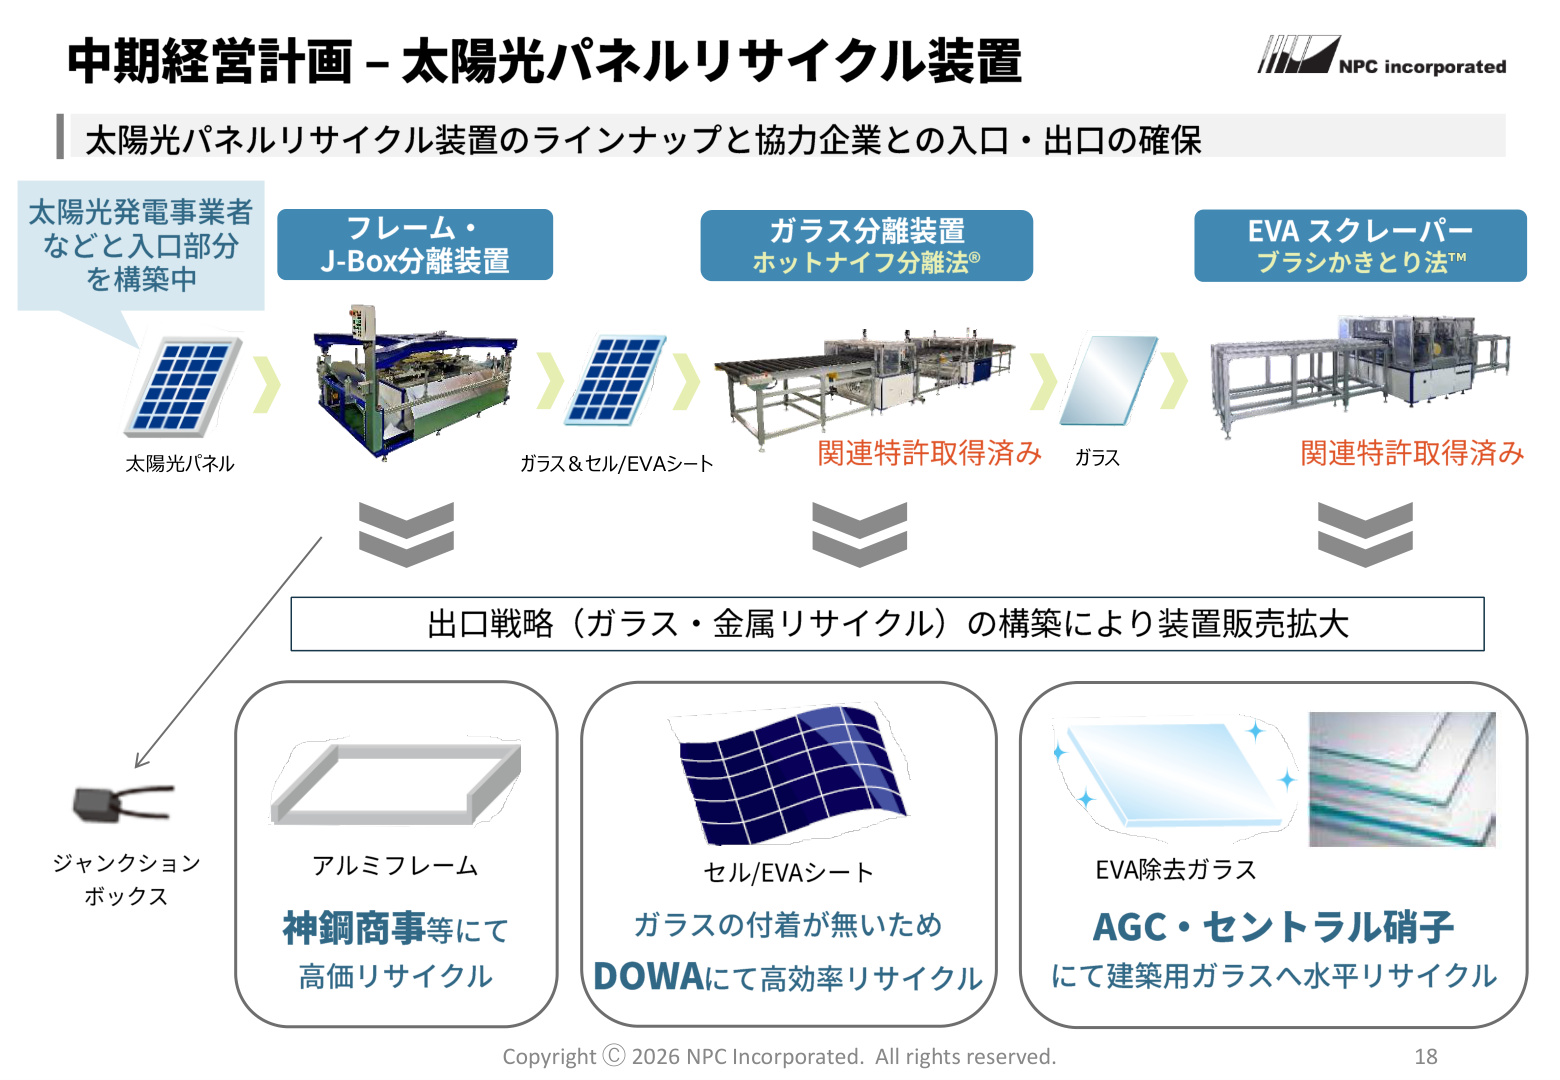
Why This Slide Is Important
This slide visualizes how NPC is not just selling equipment but has established an "exit strategy that circulates dismantled materials to recycling companies." Legislation regarding solar panel recycling is scheduled by the end of 2027, and panel disposal volumes will surge.
NPC’s proprietary patented technologies, "Hot Knife Separation Method®" and "Brush Scraping Method™ (EVA scraper)," allow for high-quality peeling and separation without crushing the cover glass. This enables aluminum frames to be sent to Shinko Shoji, cells/EVA sheets to DOWA, and EVA-removed glass to be "horizontally recycled into architectural flat glass" via companies like AGC and Central Glass . As equipment capable of horizontal recycling, it is highly likely to be certified under the Act on the Promotion of Resource Circulation, solidifying its position as the industry standard. The company expects 8.5 billion yen in domestic and 1.5 billion yen in overseas revenue from recycling equipment over the next five years.
③ Expansion of FA Equipment Portfolio
The FA equipment business plans to expand revenue over the next five years to approximately three times that of the past five years . Driven by the boom in AI and semiconductors, major domestic electronic component manufacturers are resuming investments, leading to expectations of multi-year continuous orders. The company is also accelerating expansion into new areas, such as applying vacuum laminators to other industries and developing automated waste sorting equipment for glass bottles using AI.
5. Cash Allocation and Dividend Policy
Balancing Growth Investment and Returns
The company expects to generate approximately 7.3 billion yen in operating cash flow over the next five years. The allocation policy, combined with the year-end cash balance of approx. 3.6 billion yen, is as follows:
- Growth Investment (approx. 4 billion yen) :
- R&D, marketing, and in-house production of core equipment (1–1.5 billion yen)
- Capacity expansion, M&A of automated machinery/metal processing firms, and strengthening partner factories (2–2.5 billion yen)
- Human resources and IT infrastructure (0.5–1 billion yen)
- Shareholder Returns (approx. 2 billion yen) :
- While maintaining a 25% payout ratio as the base policy, a new progressive rule has been established: "a floor of 2% DOE (Dividend on Equity)" to ensure stable dividends even during earnings fluctuations.
- Cash on Hand (approx. 4.9 billion yen) : Ensuring liquidity for working capital fluctuations and revenue expansion.
6. FY2027 Earnings Forecast
As the first year of the new Mid-Term Management Plan, FY2027 is expected to see significant revenue and profit growth as projects delayed from FY2026 are inspected and the order backlog is processed.
| Item | FY2026 (Actual) | FY2027 (Forecast) | YoY Change |
|---|---|---|---|
| Revenue | 5,811 million yen | 9,895 million yen | +70.3% |
| Operating Profit | 846 million yen | 1,380 million yen | +63.1% |
| Ordinary Profit | 880 million yen | 1,417 million yen | +61.0% |
| Net Income | 481 million yen | 826 million yen | +71.7% |
Regarding the annual dividend forecast, since the amount based on the 25% payout ratio is lower than the DOE-based amount, an increase to "11.0 yen per share" is expected, up from the previous year's 10.0 yen, based on the newly established floor (DOE 2%) .
Conclusion
Although NPC experienced a temporary decline in revenue and profit in FY2026 due to the timing of large-scale projects, its fundamental earning power has been strengthened by maintaining high gross margins and accumulating a robust order backlog. The newly formulated Mid-Term Management Plan logically aims to "resolve customer concentration risk" and "achieve record-high profits" through a full lineup of perovskite solar cell manufacturing equipment, an ecosystem for recycling equipment capturing the 2027 legislation, and the diversification of the FA equipment business.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.