

Zojirushi Corporation Q3 FY2026 Financial Results: Revenue and Operating Profit Growth Driven by High-Value Strategy and Price Pass-Through; Commitment to Aggressive Capital Investment and Shareholder Returns Maintained
Sentiment Analysis
Executive Summary
Zojirushi Corporation's consolidated financial results for the first nine months of the fiscal year ending November 2026 (November 21, 2025, to August 20, 2026) were as follows: net sales of 69.987 billion yen (up 3.4% YoY) , operating profit of 5.856 billion yen (up 5.3% YoY) , ordinary profit of 6.348 billion yen (up 3.9% YoY) , and net profit attributable to owners of the parent of 4.015 billion yen (down 2.9% YoY) .
In the domestic market, strong performance from the flagship "Enbu-daki" pressure IH rice cooker and steam-type humidifiers, combined with successful price pass-throughs to offset rising import costs and improved gross profit margins , bolstered earnings. While the overseas market faced a continued slowdown in Chinese consumer spending, growth in kitchen appliance sales in North America and expanded humidifier sales in South Korea offset these headwinds, resulting in overall revenue and operating profit growth.
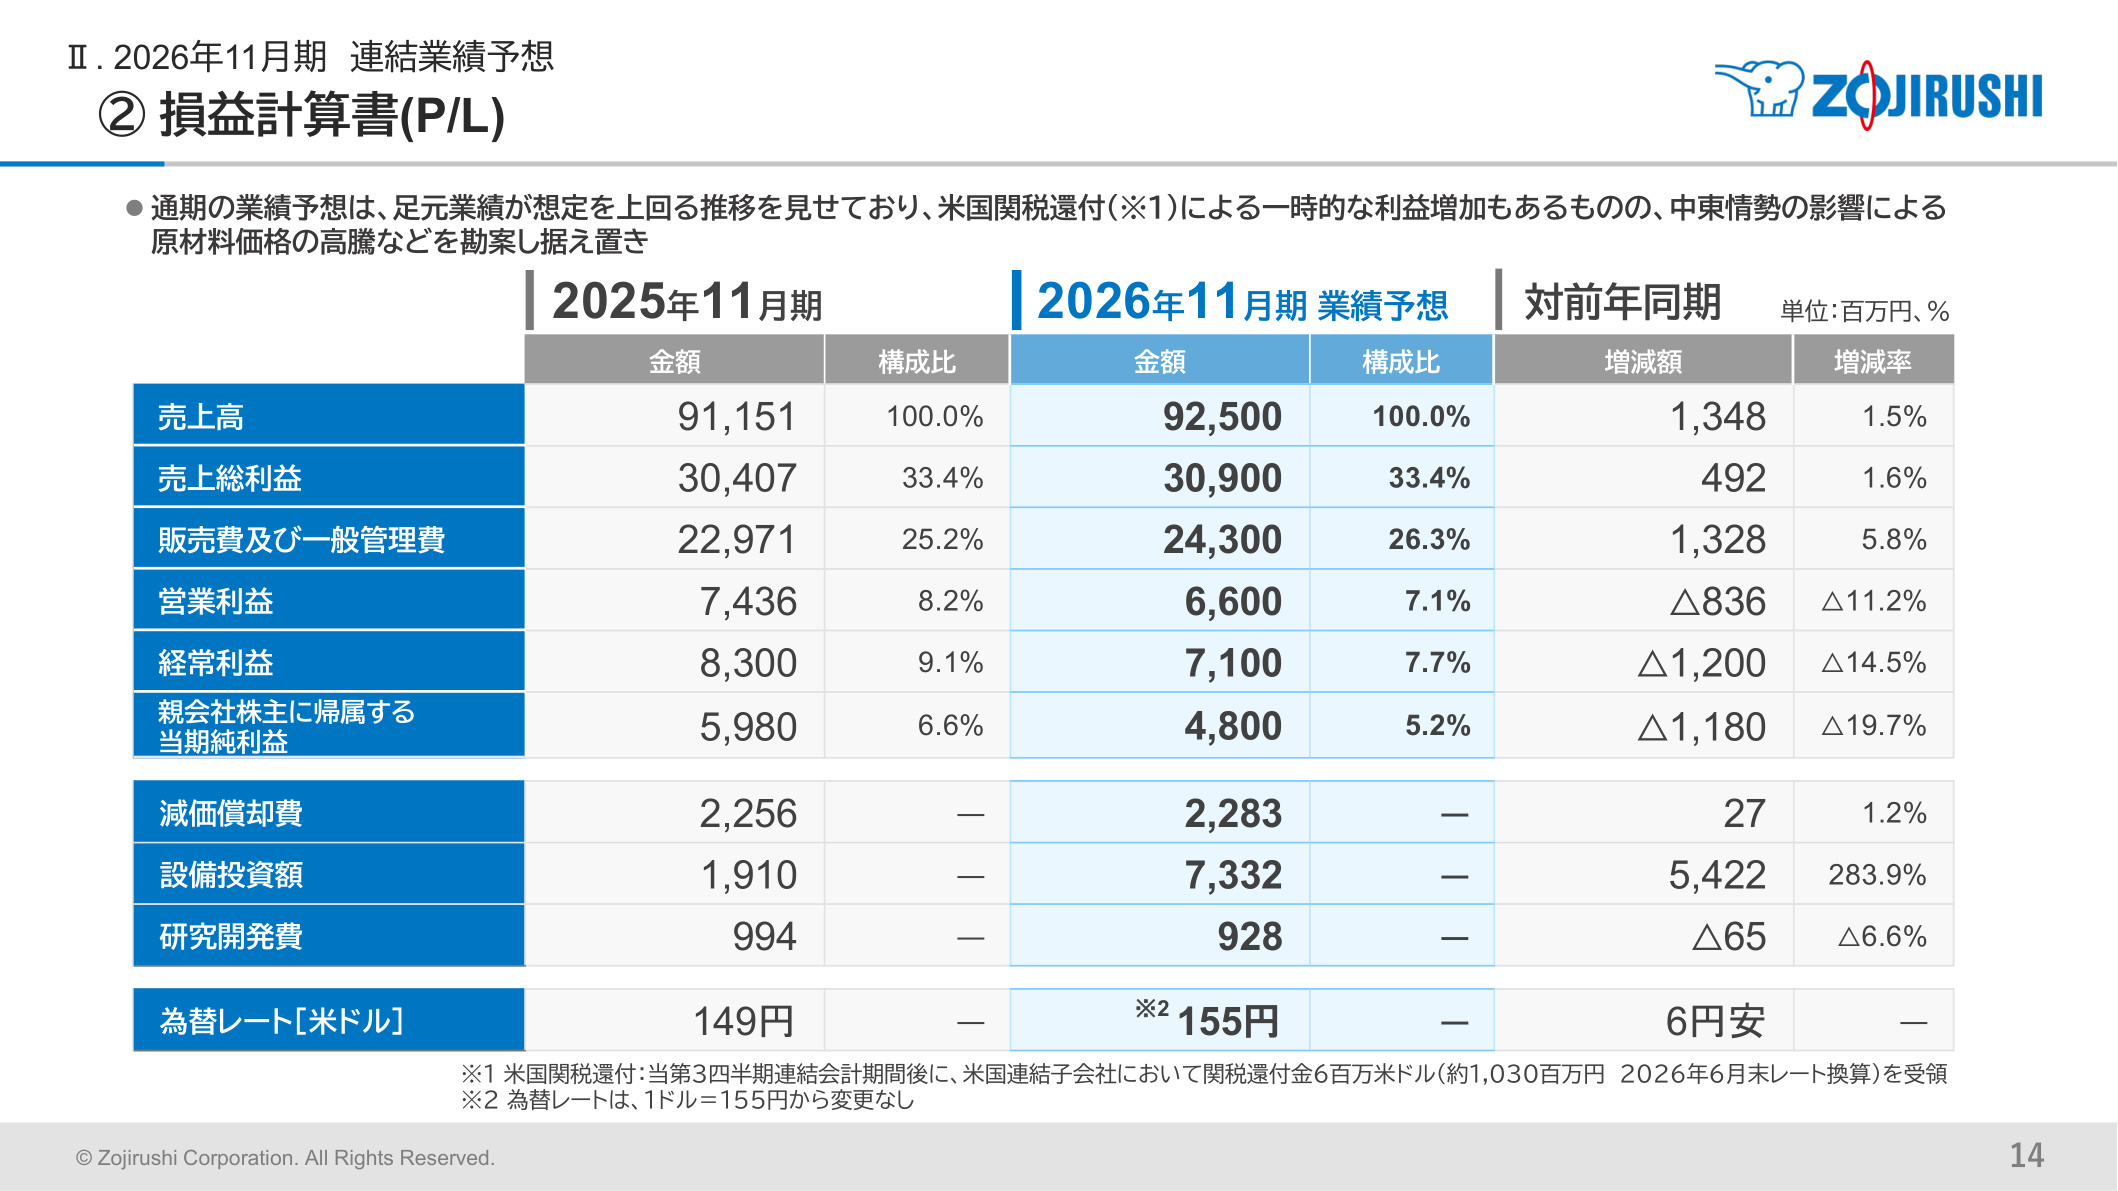
Regarding the full-year consolidated earnings forecast, the company maintains its initial projections of 92.5 billion yen in net sales and 6.6 billion yen in operating profit. While there are positive factors such as steady current performance and a one-time gain from U.S. tariff refunds, the company has opted to keep its initial forecast unchanged, cautiously accounting for risks such as rising raw material costs stemming from the situation in the Middle East. Furthermore, the company continues its generous shareholder return policy with an annual dividend of 46 yen (consolidated payout ratio of 62.1%), while significantly expanding capital investment (full-year plan of 7.332 billion yen, +283.9% YoY) to drive future growth.
1. Q3 FY2026 Financial Highlights and Profit Structure
The overall performance and details of profit fluctuation factors for the first nine months are as follows.
Key Takeaways and Background of Profit Changes
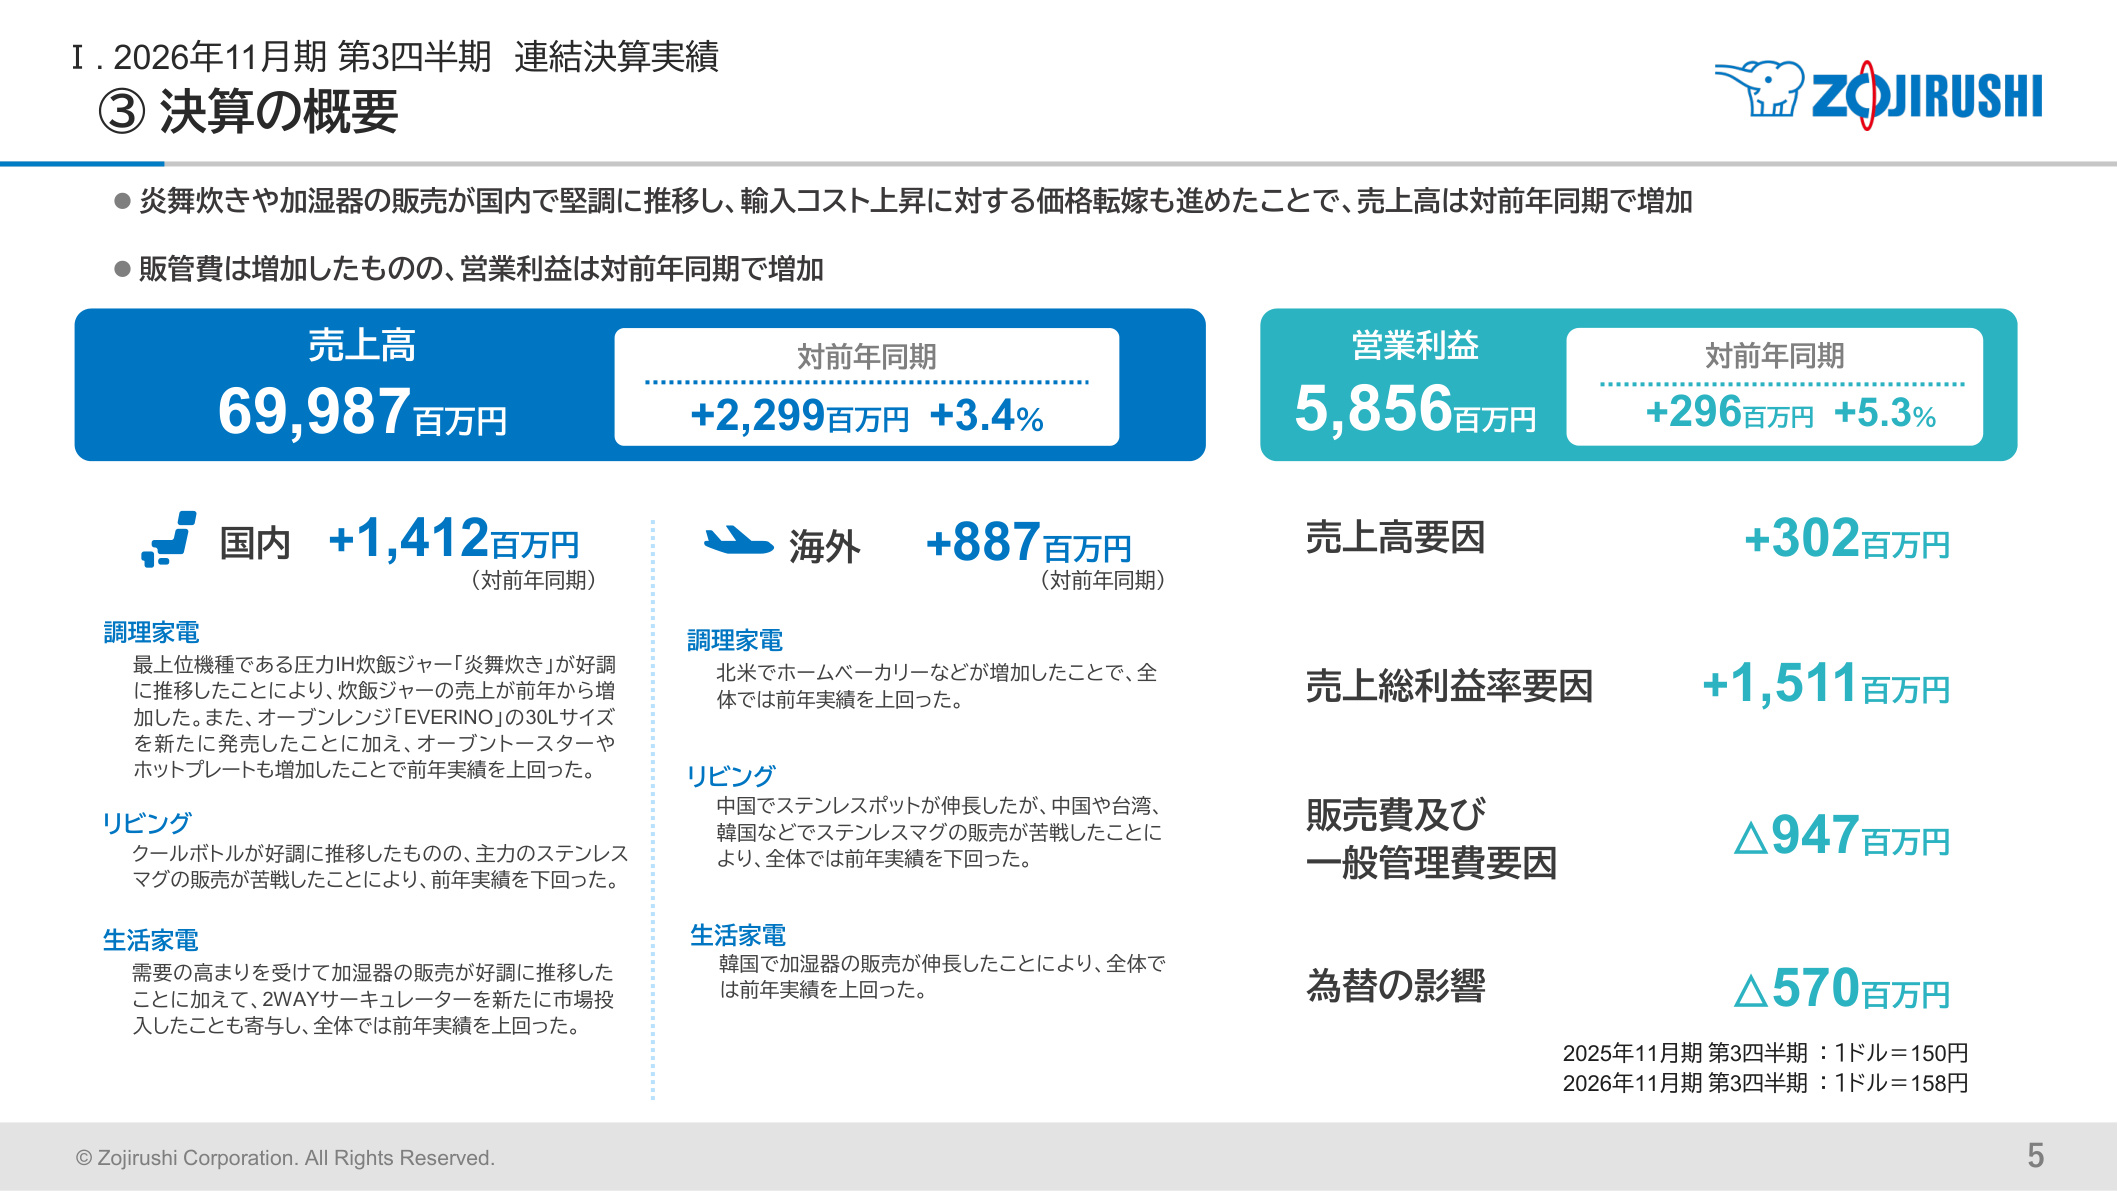
As shown in the slide above, the primary driver of the revenue and profit growth for the first nine months was the improvement in the gross profit margin (+1.511 billion yen) . Despite headwinds such as high raw material and logistics costs and the depreciation of the yen (from 150 yen to 158 yen per dollar YoY, resulting in a negative impact of 570 million yen), the penetration of price revisions, primarily in Japan, and an increased sales mix of high-value-added products contributed to the rise in the gross margin.
- Net Sales : 69,987 million yen (+2,299 million yen / +3.4% YoY)
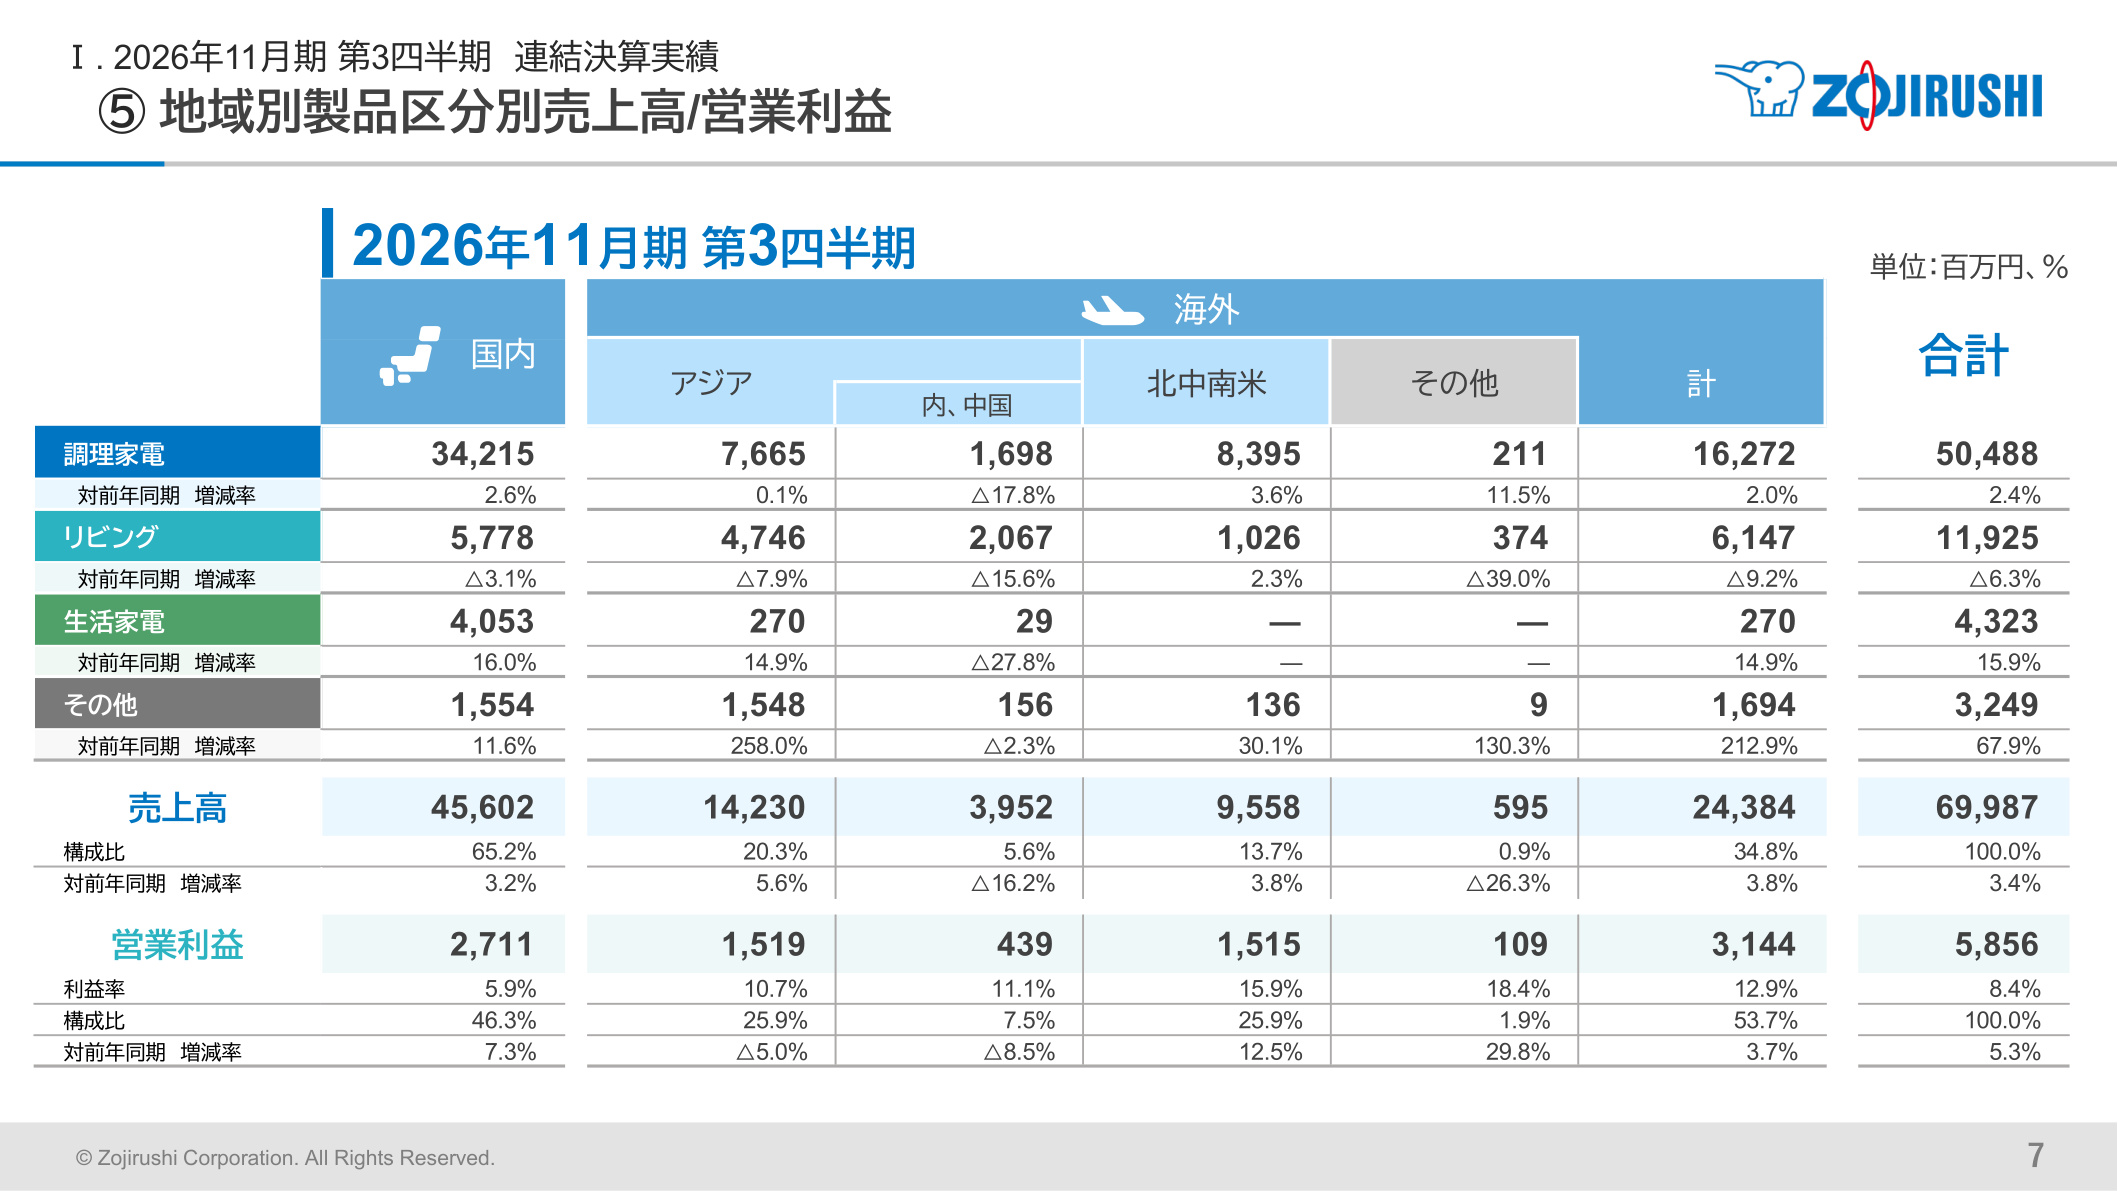
- Domestic Sales: 45,602 million yen (+1,412 million yen / +3.2% YoY)
- Overseas Sales: 24,384 million yen (+887 million yen / +3.8% YoY)
- Operating Profit : 5,856 million yen (+296 million yen / +5.3% YoY)
- Ordinary Profit : 6,348 million yen (+240 million yen / +3.9% YoY)
- Net Profit Attributable to Owners of the Parent : 4,015 million yen (-121 million yen / -2.9% YoY)
Selling, general and administrative (SG&A) expenses rose to 18.207 billion yen (up 8.0% YoY, a negative impact of 947 million yen) due to increased sales promotion activities and personnel costs. However, the expansion of gross profit (24.064 billion yen, up 7.3% YoY) outweighed these costs, leading to an increase in operating profit. The slight decline in net profit is attributable to factors such as tax expenses.
2. Detailed Trends by Product Category and Region
The market environment and performance of the product portfolio showed a clear divergence between domestic and international regions.
(1) Kitchen Appliances (Sales: 50.488 billion yen, up 2.4% YoY)
This is the core business, accounting for 72.1% of total company sales .
- Rice Cookers : 33.979 billion yen (up 4.2% YoY). Demand for the flagship "Enbu-daki" series remained extremely robust in Japan, driving both higher unit prices and increased sales.
- Electric Cooking/Microwave Appliances : The newly introduced 30L large-capacity "EVERINO" oven range performed well. Additionally, increased sales of bread makers in the North American market and growth in hot plates in Japan contributed to the results.
(2) Living Products (Sales: 11.925 billion yen, down 6.3% YoY)
- The living division, which accounts for 17.0% of total sales, saw demand for cool bottles in Japan due to the extreme heat. However, the struggle of the core stainless steel mugs in Asian markets, including China, Taiwan, and South Korea , weighed on the division, resulting in a year-on-year decline. Glass vacuum bottles also continued to shrink, totaling 863 million yen (down 21.8% YoY).
(3) Home Appliances (Sales: 4.323 billion yen, up 15.9% YoY)
- Although accounting for 6.2% of the total, this segment recorded high growth. Steam-type humidifiers , which capture hygiene and comfort-oriented demand, saw significant growth both domestically and internationally (particularly in Japan and South Korea). Additionally, the "2-WAY Circulator" introduced to new markets contributed to sales, leading to strong growth in the air conditioning and heating/cooling product group, which reached 3.517 billion yen (up 22.4% YoY).
(4) Profitability Analysis by Region
- Japan (Sales 45.602 billion yen / Operating Profit 2.711 billion yen, Margin 5.9%) : Operating profit is on a recovery trend, up 7.3% YoY.
- North, Central, and South America (Sales 9.558 billion yen / Operating Profit 1.515 billion yen, Margin 15.9%) : Maintains a high level of profitability, with operating profit up 12.5% YoY.
- Asia (Sales 14.230 billion yen / Operating Profit 1.519 billion yen, Margin 10.7%) : While sales in China were sluggish at 3.952 billion yen (down 16.2% YoY, operating profit down 8.5%), growth in other regions helped maintain an operating profit margin in the 10% range for Asia as a whole.
3. Financial Foundation and Balance Sheet Status
As of August 20, 2026, the financial position remains robust and secure.
- Total Assets : 116.572 billion yen (down 1.759 billion yen from the end of the previous fiscal year)
- Current Assets : 78.295 billion yen (including 28.131 billion yen in cash and deposits, and 26.950 billion yen in merchandise and finished goods)
- Non-current Assets : 38.276 billion yen (tangible fixed assets at 17.588 billion yen, an increase of 3.790 billion yen from the end of the previous fiscal year)
- Net Assets : 92.014 billion yen (up 2.424 billion yen from the end of the previous fiscal year)
- Equity Ratio : Maintained at an extremely healthy level of 78.1% .
The increase in tangible fixed assets reflects the execution of capital investments for production facilities and facility renewals aimed at future growth, as described below.
4. Full-Year FY2026 Earnings Forecast and Investment/Return Strategy
The key points of the full-year consolidated earnings outlook and capital policy are as follows.
Unchanged Full-Year Forecast and Assumptions
The full-year earnings forecast remains unchanged from the initial plan.
- Net Sales : 92.5 billion yen (+1.5% YoY)
- Operating Profit : 6.6 billion yen (-11.2% YoY)
- Ordinary Profit : 7.1 billion yen (-14.5% YoY)
- Net Profit : 4.8 billion yen (-19.7% YoY)
- Assumed Exchange Rate : 1 USD = 155 JPY (unchanged)
Following the third quarter, the U.S. consolidated subsidiary received a tariff refund of approximately 6 million USD (approx. 1.03 billion yen) due to a court ruling invalidating certain tariffs. While this is a positive factor, with a portion treated as a reduction in cost of sales, the company has maintained a cautious stance on the full-year outlook, factoring in concerns over further spikes in raw material costs due to geopolitical risks (such as the situation in the Middle East).
Capital Investment for Growth and Shareholder Returns
- Significant Expansion of Capital Investment : The full-year capital investment is planned at 7.332 billion yen (+283.9% YoY) . The company is accelerating investments in updating aging equipment, improving production efficiency, and expanding into new categories.
- Shareholder Return Policy : The company maintains a policy of "striving to maintain stable dividends with a consolidated dividend payout ratio of 50% or more as a guideline." The annual dividend for the fiscal year ending November 2026 is projected at 46 yen , with an expected consolidated payout ratio of 62.1% (the previous fiscal year included a special dividend of 42 yen for a total of 82 yen, with a payout ratio of 88.8%).
5. Summary and Future Outlook
Zojirushi's Q3 results demonstrate that the company can maintain its core earning power despite the weak yen and high costs, thanks to the appeal of high-value-added products such as "Enbu-daki" and steam-type humidifiers, and agile price pass-throughs .
Looking ahead, the following points are of interest:
- Timing of Recovery in the Chinese Market and Expansion in Emerging Countries : Recovery in demand for mug products and kitchen appliances in Asia, as well as further growth in the North American market.
- Development of New Products and Categories : Establishing new profit pillars beyond rice cookers, pots, and bottles, such as the "EVERINO" oven range and circulators.
- Transition to the Recovery Phase of Aggressive Investment : How the 7 billion yen scale of capital investment will contribute to long-term productivity improvements and profit margin expansion.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.