

Smilemen (9237) Q3 FY2026 Earnings Deep Dive: A High-Growth Scenario Driven by Organizational Strengthening, M&A, and New Business Schemes

StockClub
Published: Sep 14, 2026, 10:17 AM
Sentiment Analysis
1. Earnings Overview: 40% YoY Revenue Growth and Return to Operating Profit Mark a Turning Point in Business Structure
Smilemen (9237), a provider of senior home referral services and consulting for nursing care operators, reported its Q3 FY2026 results (three-month period: May–July 2026). The company achieved operating revenue of 616 million yen, up 40.0% year-on-year , and a significant turnaround to an operating profit of 57 million yen (compared to an 11 million yen loss in the same period last year). Ordinary profit stood at 54 million yen, with quarterly net profit reaching 22 million yen, signaling a recovery in profitability alongside business expansion.
In its core "Senior Life Support" service, the coordinators hired in the previous fiscal year and Q1 of this year have become fully operational. Consequently, the number of successful placements, or "Smile Count," surged by 35.6% YoY to 1,601 . Conversely, in the senior home consulting sector, owner appetite for new developments has softened due to rising construction costs and interest rates, leading to weaker-than-planned performance in traditional new facility opening support. However, demand is rapidly shifting toward the company’s "Partner Lease" master-lease scheme, indicating a clear qualitative shift in the company's mid-to-long-term revenue base.
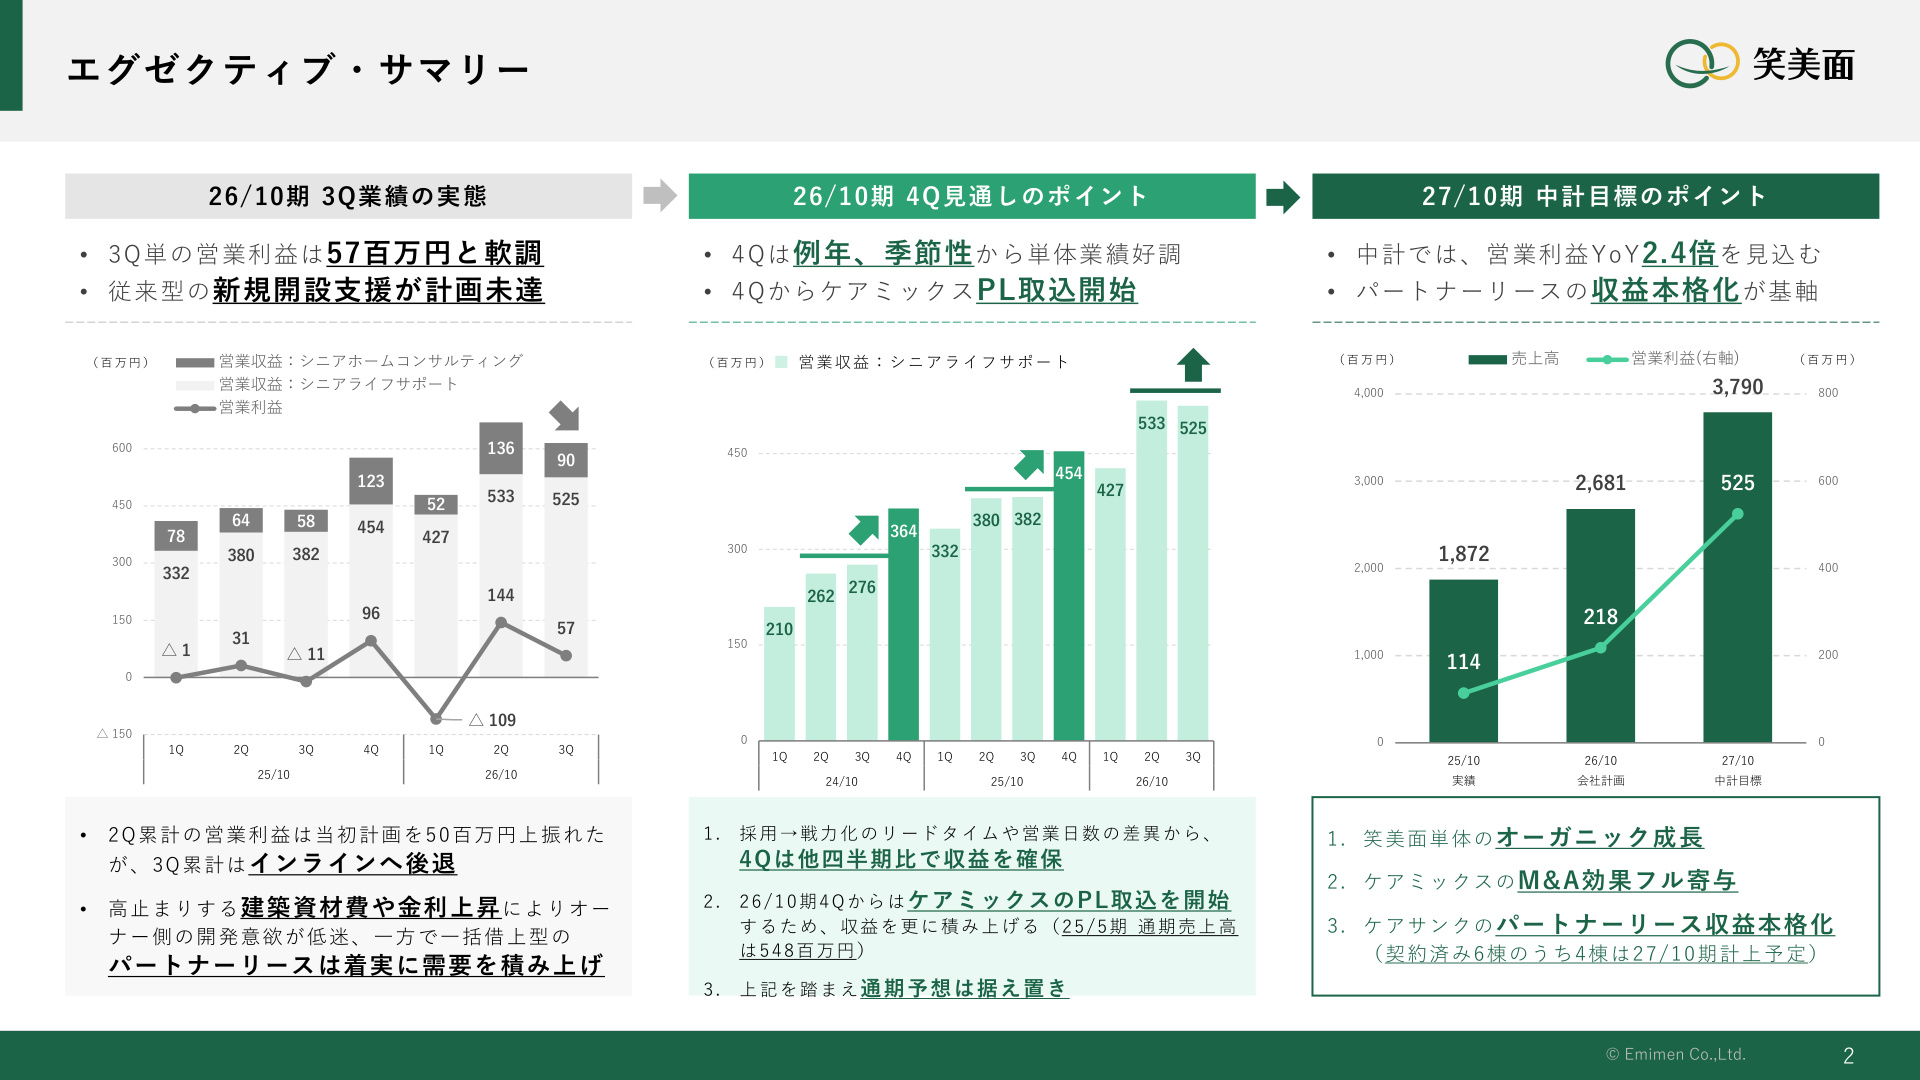
As indicated in the executive summary above, cumulative operating profit through Q3 is tracking in line with the plan, and the full-year earnings forecast (2.681 billion yen in revenue, 218 million yen in operating profit) remains unchanged. The company typically experiences seasonal revenue concentration in Q4 due to the lead time required for new hires to become productive and the number of business days. Furthermore, with the consolidation of Care Mix Co., Ltd. —now a wholly-owned subsidiary—beginning in Q4, the company expects a significant ramp-up in revenue accumulation to meet its full-year targets.
2. Segment Trends and KPI Analysis: Resilience in Core Business and Adaptation to Challenges
① Senior Life Support Business (Operating Revenue: 525 million yen, +37.6% YoY)
This core business matches prospective residents with optimal facilities from a neutral standpoint, primarily through referrals from medical social workers (MSWs) and home-visit nursing care support offices nationwide.
- Number of Family Meetings : 2,861, up 26.5% YoY . This is a critical step in ensuring satisfaction for both the prospective resident and their family, directly correlating with higher conversion rates.
- Smile Count (Successful Placements) : 1,601, up 35.6% YoY . Placements are growing at a faster pace than family meetings, quantitatively demonstrating improved coordinator skills and matching precision.
- Normalization of Organizational Pyramid : To address organizational challenges from the previous year—such as insufficient training for new hires and the burden on management due to rapid expansion—the company concentrated hiring in Q1 and focused on training, development, and operational excellence in Q2 and Q3. As a result, the proficiency of coordinators with over six months of tenure has improved, confirming gains in productivity.
② Senior Home Consulting Business (Operating Revenue: 90 million yen, +55.2% YoY)
This business provides comprehensive support for the opening and operation of senior homes. While affected by the external environment, structural reforms are underway.
- New Facility Rooms Opened : 376 rooms were added in Q3 alone, bringing the cumulative total to 3,451 rooms.
- External Environment and Business Model Shift : Due to rising material costs and interest rates, traditional development support projects where owners bear direct risk are declining. In response, there is a rapid increase in inquiries for the "Partner Lease" scheme , where Smilemen master-leases the senior home and subleases it to operators.
3. Strategic Investments Accelerating Growth: Care Mix M&A and Partner Lease
To achieve non-linear growth, Smilemen is actively utilizing two levers: "scale expansion through M&A" and "establishment of high-margin new schemes."
① Acquisition of Care Mix Co., Ltd.
On June 1, 2026, the company acquired all shares of Care Mix Co., Ltd. (acquisition cost: 345 million yen), which operates senior home referral services primarily in the Kanto region.
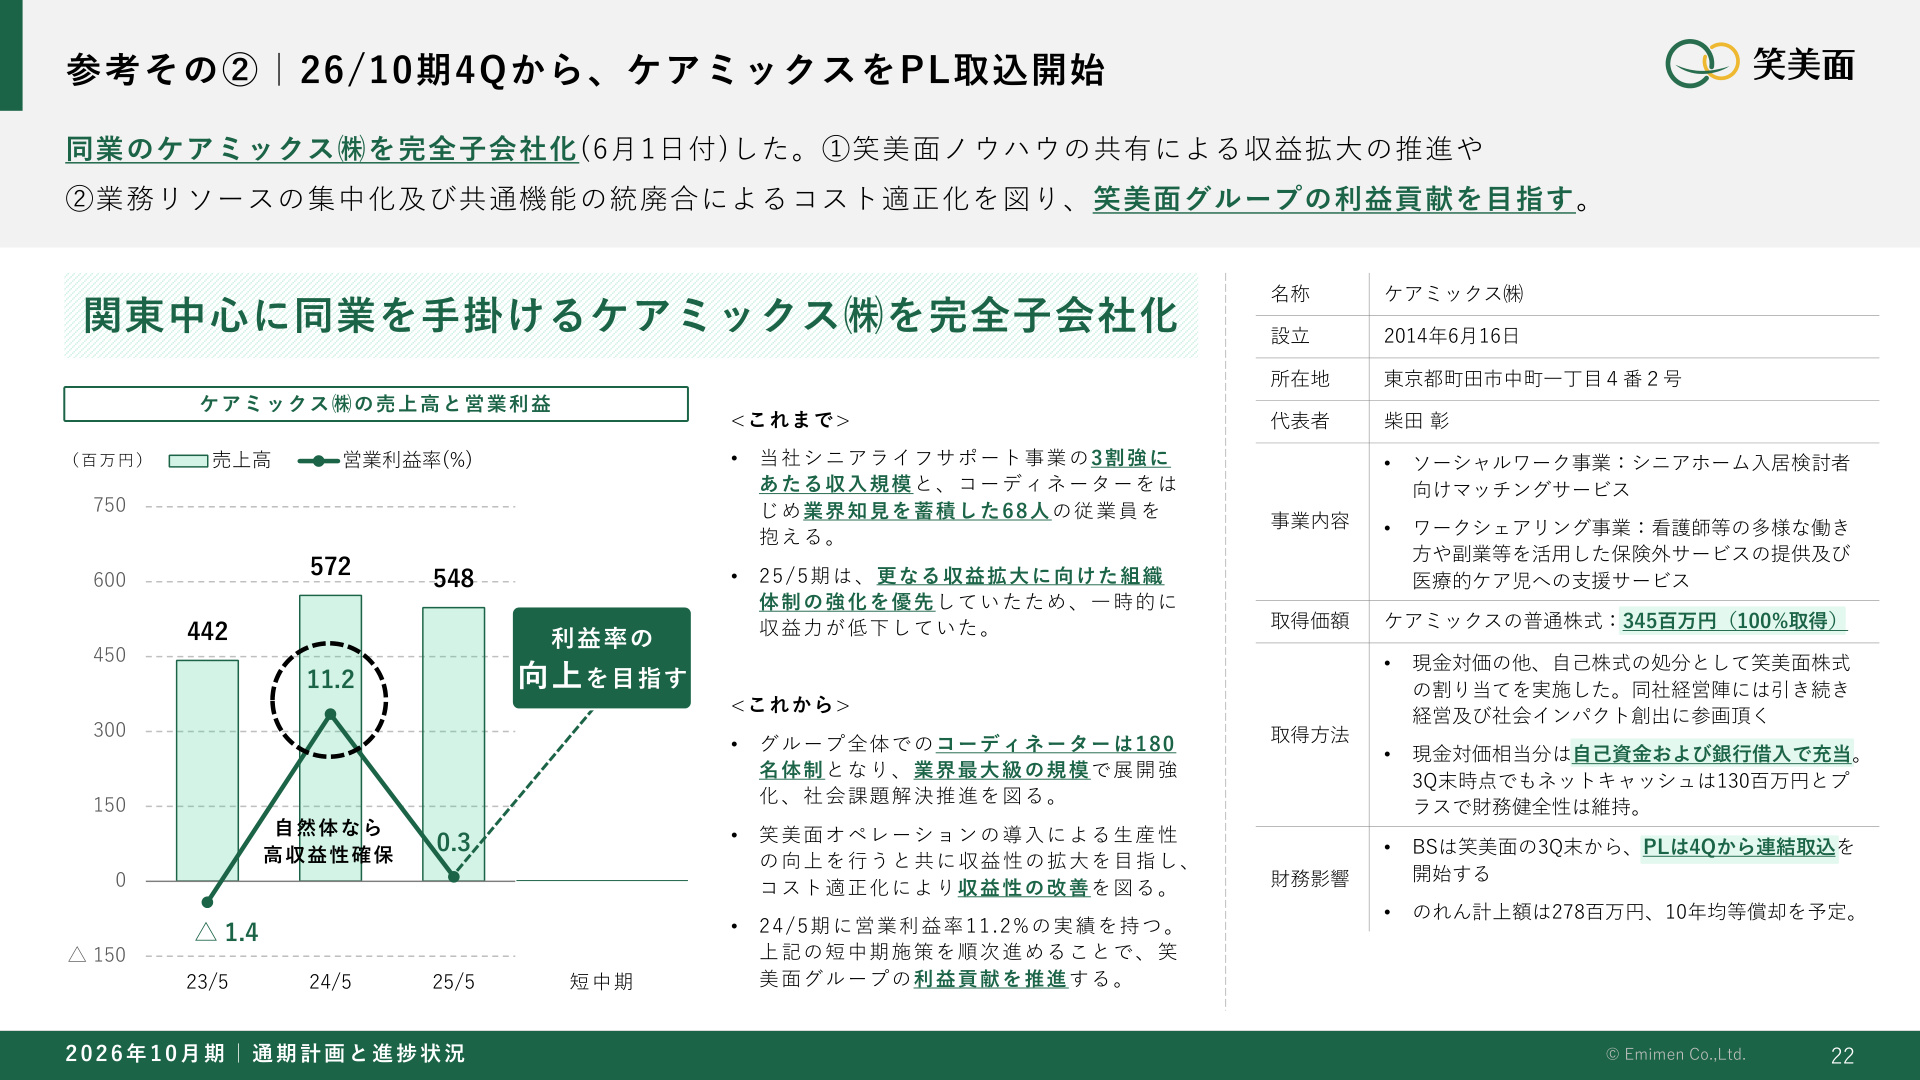
Care Mix represents a business scale equivalent to over 30% of Smilemen's Senior Life Support business (FY2025 revenue: 548 million yen) and brings 68 employees to the group. This M&A brings the total number of group coordinators to approximately 180 , creating one of the industry's largest networks. Financially, the company was consolidated onto the balance sheet at the end of Q3 FY2026, and P/L integration begins in Q4 . While total goodwill is expected to be 278 million yen (amortized over 10 years at approximately 28 million yen annually), the company aims for early profit contribution and margin improvement through the introduction of Smilemen’s operational know-how and optimization of indirect costs.
② Revenue Mechanism of "Partner Lease"
"Partner Lease" minimizes vacancy and development risks for owners by master-leasing buildings and subleasing them to operators. Because this scheme is accounted for similarly to financial lease transactions, the present value of future rental margin profits is recognized as revenue and profit in a lump sum in the first year of handover . Currently, four out of the six contracted properties (over 300 rooms) are scheduled for handover and revenue recognition in FY2027 , serving as a powerful driver for performance in the coming fiscal years.
4. New Demand Frontier: Supporting Business Caregivers
In addition to hospital and MSW referral channels, the company has launched a support service for "Business Caregivers" (employees balancing work and caregiving) , targeting corporate HR departments.
- Smilemen Caregiver Mental Care Room : A one-stop consultation and placement support window for corporate employees. Adoption is progressing at major companies such as Resona Holdings and Duskin.
- Kaigo QQ Method Survey Plus : Launched in July 2026, this service visualizes the risk of "caregiving resignation" and economic losses due to productivity decline through internal surveys, supporting management decision-making in human capital management.
With the enforcement of the revised Child Care and Family Care Leave Act (April 2025) acting as a tailwind, the company is leveraging its unique strength in providing end-to-end support—from early consultation to facility matching—in the increasingly critical area of business caregivers.
5. Mid-Term Management Plan (FY26/10–FY28/10): Roadmap and Overview
Smilemen has formulated an ambitious mid-term management plan for FY2028, centered on the two pillars of nationwide expansion of the referral business and facility opening support via Partner Lease.
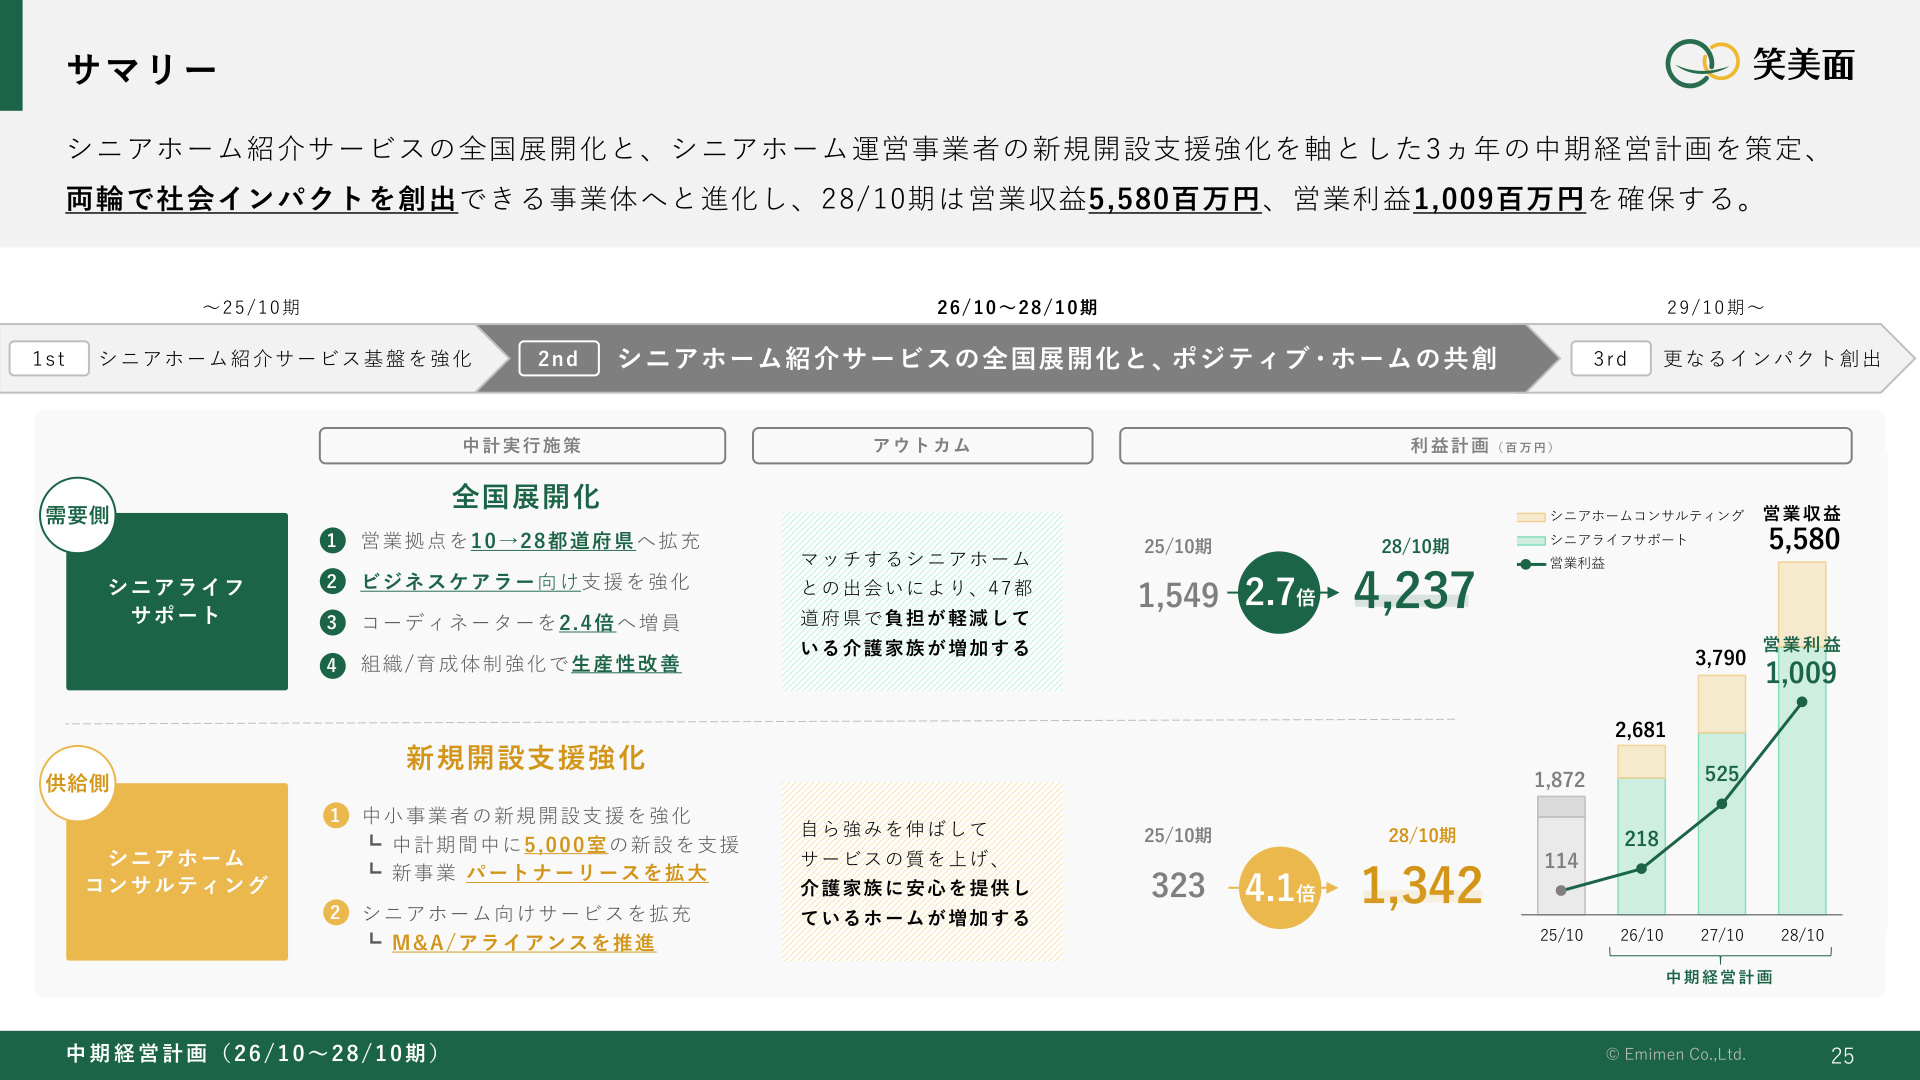
Key Targets for Mid-Term Management Plan (FY2028)
- Operating Revenue : 5.58 billion yen (2.98x compared to FY2025 results)
- Senior Life Support: 4.237 billion yen (maintaining ~40% annual growth as seen in the past three years)
- Senior Home Consulting: 1.342 billion yen (4.1x compared to FY2025)
- Operating Profit : 1.009 billion yen (8.85x compared to FY2025, Operating Margin: 18.1% )
- Key Impact KPIs :
- Family Meetings: 25,710
- Smile Count (Successful Placements): 12,741
- New Rooms Opened: 2,000 rooms/year (5,000 rooms cumulative over the plan period)
Four Priority Strategies to Achieve the Plan
- Accelerate Nationwide Expansion : Expand sales bases from the current 17 offices in 10 prefectures to 28 prefectures by the final year of the plan .
- Strengthen Business Caregiver Support : Establish consultation and acquisition channels outside of MSW referrals.
- Balance Personnel Scale and Productivity : Increase the number of coordinators to over 300 (approx. 2.4x) while ensuring early productivity through standardized training programs.
- Full-Scale Expansion of Partner Lease : Support new facility construction for small-to-medium operators and secure recurring, large-scale revenue.
6. Summary and Outlook
Smilemen's Q3 FY2026 results demonstrate that the company has overcome the temporary organizational friction caused by rapid hiring in the previous year, with productivity steadily recovering through the systematization of training and development processes . In the short term, the focus will be on the seasonal revenue expansion in Q4 and the full-year landing, including the consolidation of Care Mix.
In the mid-to-long term, key monitoring indicators for achieving the company's mid-term goal (1 billion yen in operating profit) include the progress of corporate business caregiver support, the completion and handover of "Partner Lease" projects (with lump-sum revenue recognition expected from FY2027 onwards), and the feasibility of expanding market share through nationwide coverage across 28 prefectures.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.