

tripla Q3 FY2026 Earnings Analysis: Upward Revision to Full-Year Guidance Driven by Surging Take Rates in 'tripla Book' and Robust Inbound Demand

StockClub
Published: Sep 14, 2026, 10:12 AM
Sentiment Analysis
Introduction
tripla Co., Ltd. (Securities Code: 5136), a comprehensive provider of solutions for the hospitality industry—including the accommodation booking engine " tripla Book ," the AI chatbot " tripla Bot ," and the CRM/marketing tool " tripla Connect "—has announced its financial results for the third quarter (Q3) of the fiscal year ending October 2026.
Driven by a significant increase in Gross Merchandise Value (GMV) supported by strong inbound travel demand and a rapid expansion in usage-based revenue resulting from higher take rates, the company achieved exponential growth, with both operating profit and ordinary profit more than doubling year-on-year . Following this strong performance, the company has announced its second upward revision to its full-year earnings forecast , with operating profit now expected to surpass the 1 billion yen milestone , significantly exceeding the initial plan.
This report provides a detailed analysis of the Q3 financial results, performance by region and segment, the background behind the upward revision, and the evolution of the company's revenue structure.
1. Q3 FY2026 Earnings Highlights
For the first nine months of the fiscal year (November 2025 – July 2026), the consolidated results demonstrated strong top-line growth and high operating leverage, with all profit metrics significantly outperforming the previous year.
- Operating Revenue : 2,613 million yen ( +43.2% YoY)
- Operating Profit : 758 million yen ( +133.7% YoY)
- Ordinary Profit : 874 million yen ( +139.3% YoY)
- Net Income Attributable to Owners of Parent : 574 million yen ( +86.2% YoY)
On a quarterly basis (Q3 standalone), operating revenue reached 852 million yen, with the quarterly operating profit margin reaching a high level of 34.5% .
2. Regional Performance: Japan Operations Driving Group-Wide Growth
Looking at the consolidated regional breakdown, the core Japan business is the primary driver of both revenue and profit for the entire group.
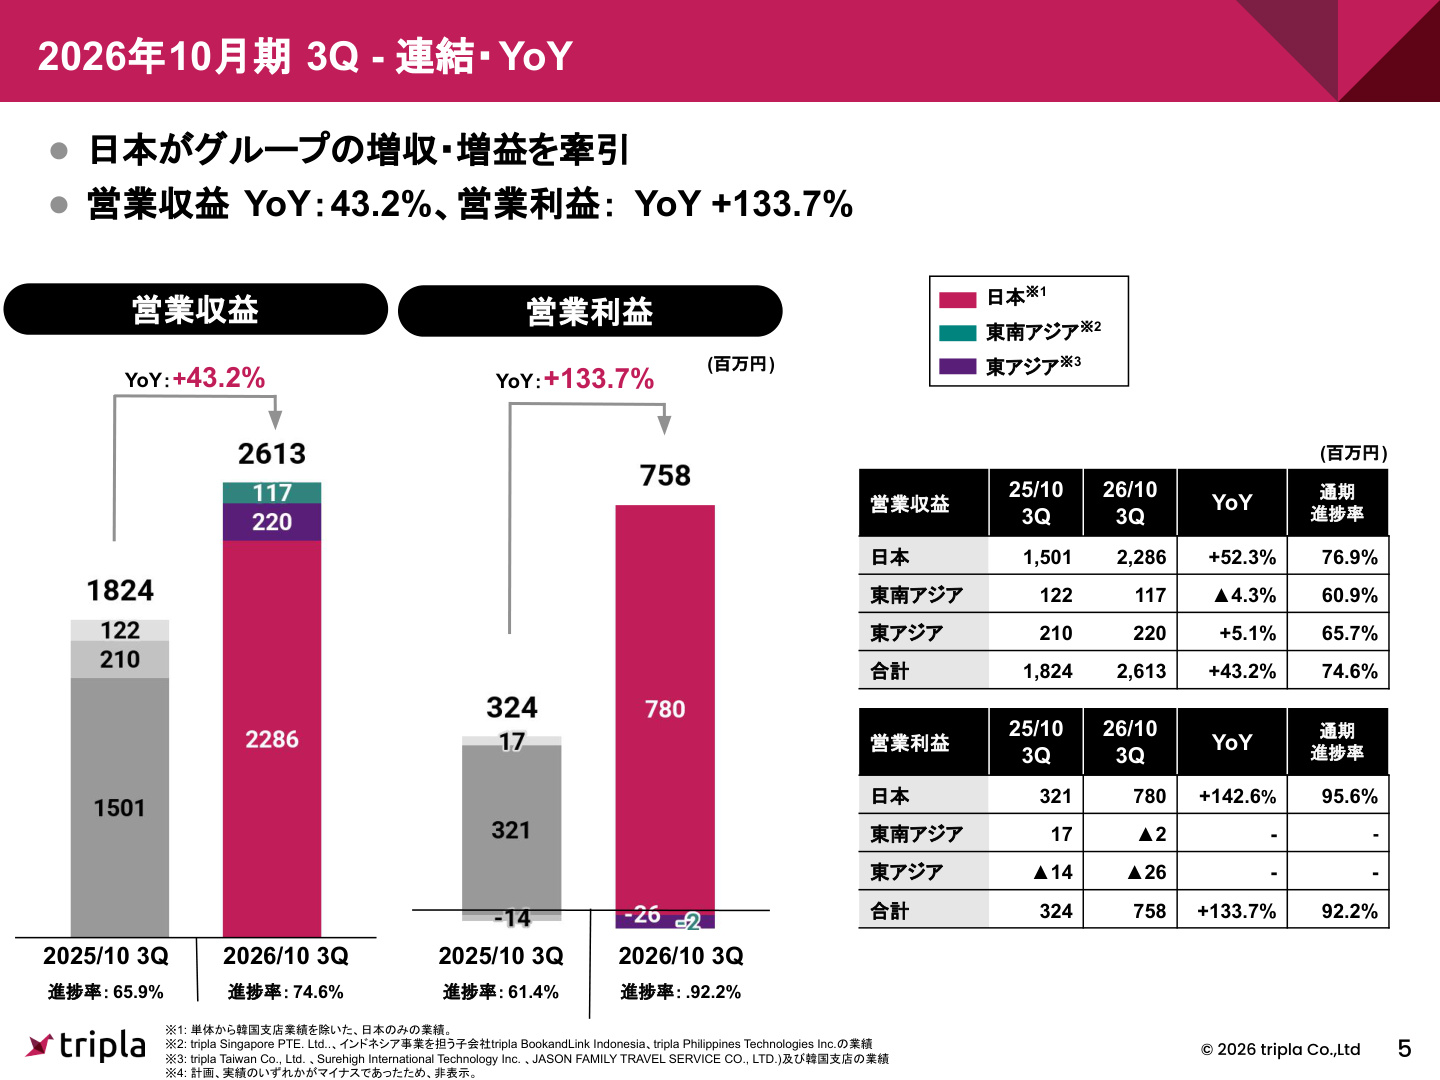
Slide Commentary: Regional Performance Composition and Significance
The slide above illustrates the regional breakdown (Japan, Southeast Asia, East Asia) of operating revenue and operating profit for Q3 FY2026. The following key structural insights can be drawn from this data:
- Dominant Growth in the Japanese Market : Japan's operating revenue reached 2,286 million yen ( +52.3% YoY), and operating profit reached 780 million yen ( +142.6% YoY), accounting for nearly all of the group's profit. This is directly attributable to the expansion of booking engine volume, which captured robust demand from individual inbound travelers.
- Progress in Southeast Asia : Operating revenue was 117 million yen (-4.3% YoY), and operating profit was -2 million yen (a profit of +35 million yen before goodwill amortization). While impacted by the absence of one-time development revenue (21 million yen) recorded in Q1 of the previous year and upfront investments in the new Philippine office established in FY2025, the Indonesian business alone achieved an operating profit of 10 million yen even after goodwill amortization .
- Status of East Asia : Operating revenue in East Asia, including Taiwan and South Korea, was 220 million yen (+5.1% YoY), with an operating loss of 26 million yen. Despite the reactionary decline from large-scale system integration (SI) projects in the previous period and sluggish domestic travel demand in Taiwan due to a focus on outbound travel, core SaaS products have performed steadily.
3. Second Upward Revision to Full-Year Forecast: Top-Line Strength and Cost Optimization
Based on the strong Q3 results and accelerating business momentum, the company has announced an upward revision to its full-year plan.
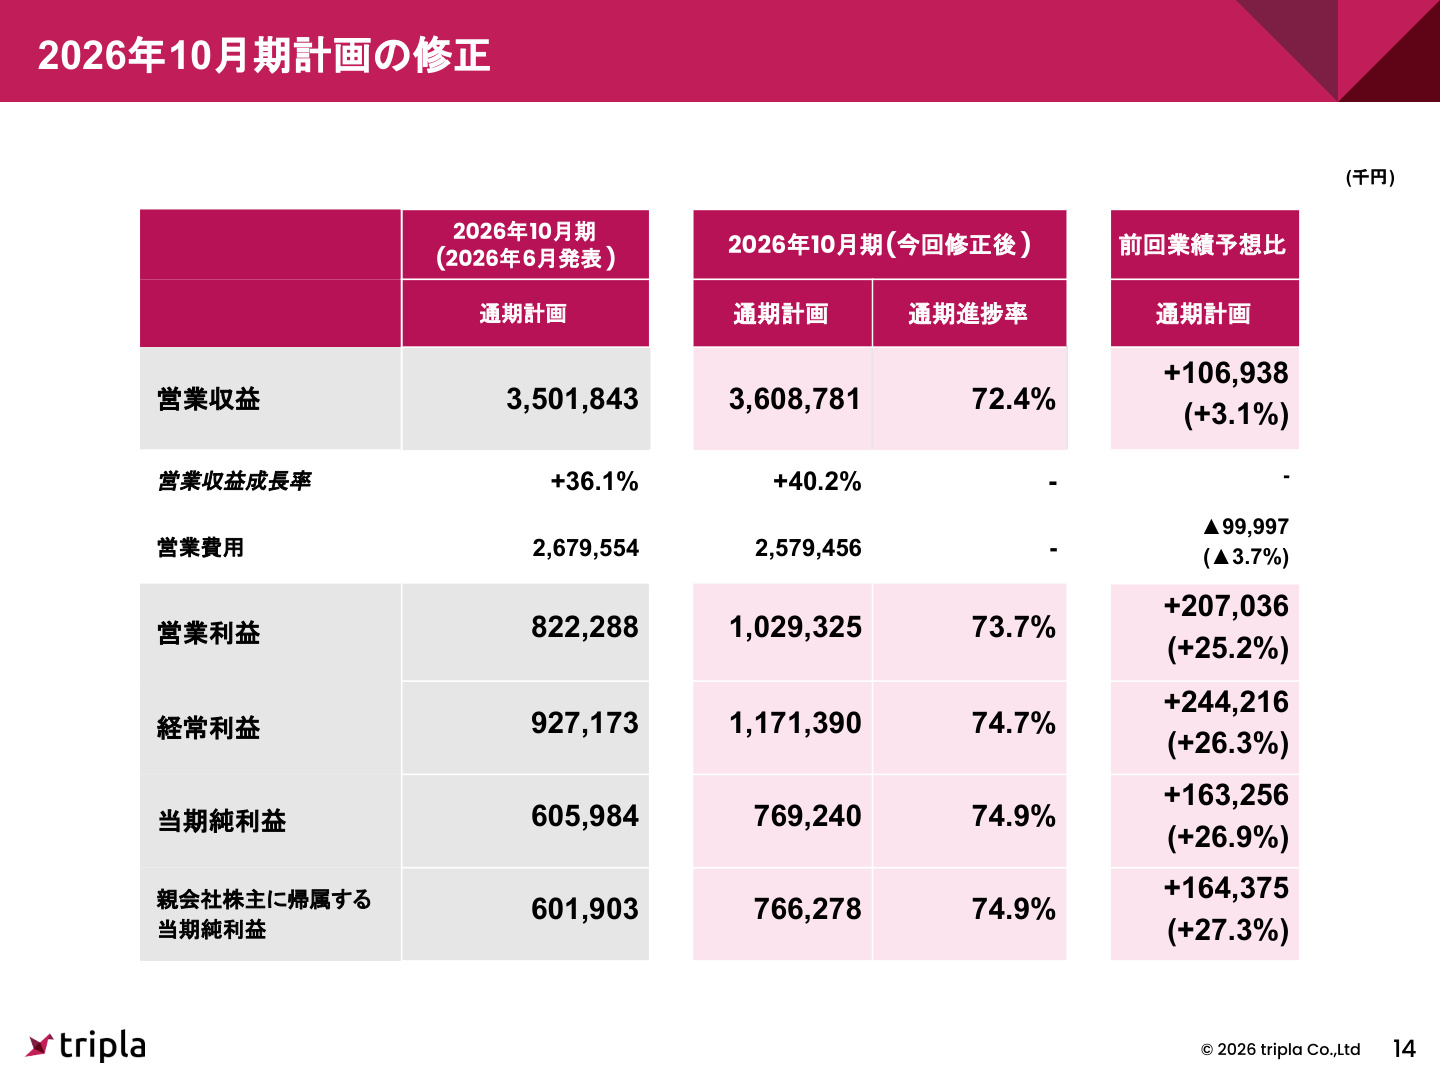
Slide Commentary: Details of the Upward Revision
This slide shows the breakdown of the revision from the previous forecast announced in June 2026. Key points are as follows:
- Operating Revenue : 3,501 million yen → 3,608 million yen (+3.1% vs. previous forecast, +40.2% YoY)
- Operating Expenses : 2,679 million yen → 2,579 million yen (-3.7% vs. previous forecast)
- Operating Profit : 822 million yen → 1,029 million yen (+25.2% vs. previous forecast, +98.0% YoY)
- Ordinary Profit : 927 million yen → 1,171 million yen (+26.3% vs. previous forecast, +100.6% YoY)
- Net Income Attributable to Owners of Parent : 601 million yen → 766 million yen (+27.3% vs. previous forecast, +52.7% YoY)
At the end of Q2, the company maintained a conservative outlook for the second half due to concerns over geopolitical risks, currency fluctuations, and a potential slowdown in traveler numbers. However, these concerns did not materialize, and business momentum accelerated further . In addition to the revenue growth effect from "tripla Book" (+106 million yen), cost optimization through the review of server expenses and the outsourcing of certain recruitment functions (+99 million yen) contributed significantly to the upward revision of operating profit. Furthermore, non-operating income (+29 million yen), including interest income from increased deposits and foreign exchange gains, is expected to bring ordinary profit to 1,171 million yen.
4. KPI Progress and Revenue Expansion Mechanism of "tripla Book"
"tripla Book," the core of the company's growth, continues to expand strongly in both "quantity" (number of facilities) and "quality" (take rate).
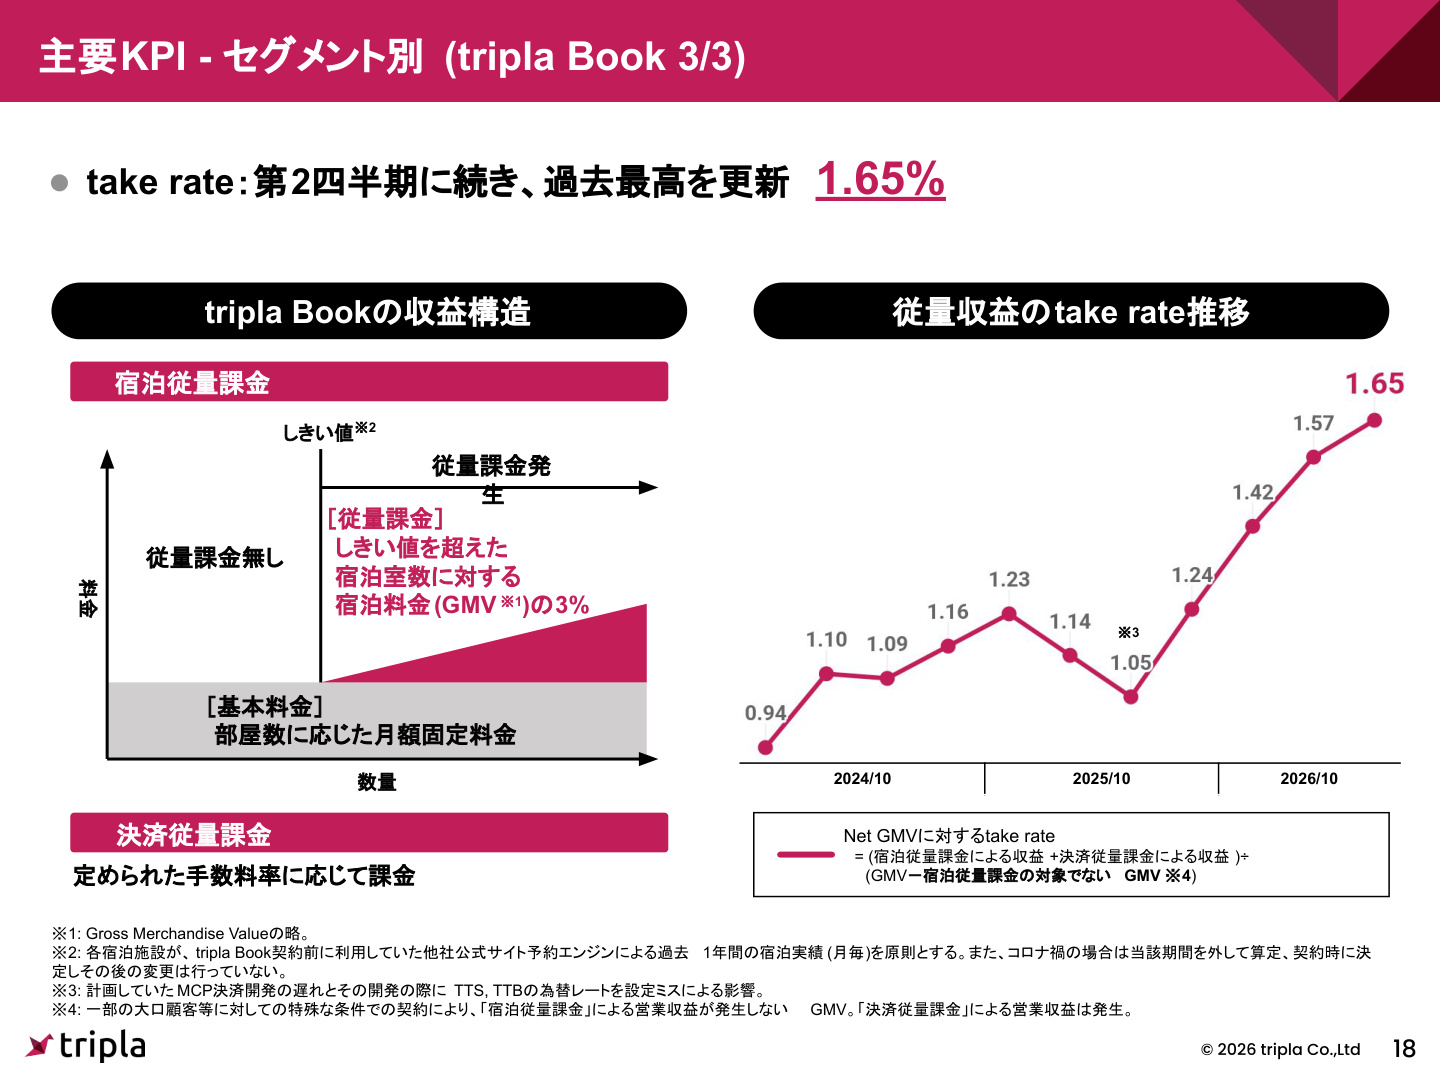
Slide Commentary: Surge in Take Rate and Superiority of the Revenue Model
The slide above shows the revenue structure of "tripla Book" and the quarterly trend of the take rate against Net GMV.
- Take Rate Reaches Record High of 1.65% : This is an increase from 1.57% in the previous quarter, marking a new record high and a significant improvement compared to 1.05% in Q3 FY2025.
- Hybrid Revenue Model :
- Base Fee (Fixed Revenue) : Monthly fixed fee based on the number of rooms (Q3 result: 121 million yen).
- Accommodation Usage Fee : 3% of GMV for bookings exceeding the threshold of non-tripla booking history.
- Payment Usage Fee : Commission based on the volume of advance payments processed.
Domestic GMV expanded to 56 billion yen in Q3 (+30.8% YoY), and the number of facilities grew steadily to 4,530 (+320 facilities QoQ). While the overall accommodation market shows some impact from fluctuations in the Chinese market, bookings from individual inbound travelers, primarily from Western and neighboring Asian countries, remain active. This has directly led to an explosive increase in accommodation and payment usage fees (Book usage revenue: 543 million yen, +77.2% YoY).
5. Progress of Each Product and Cross-Selling Expansion
Products other than "tripla Book" are also seeing progress in expanding their customer base and increasing value-added services.
-
tripla Bot (AI Chatbot)
- Operating Revenue : 322 million yen (+10.9% YoY)
- Number of Facilities : 2,289 (+232 from end of previous fiscal year)
- The shift to fixed-price plans is progressing, improving stability as recurring revenue.
-
tripla Connect (CRM/Marketing Support)
- Operating Revenue : 81 million yen (+51.0% YoY)
- Number of Facilities : 1,537 (+374 from end of previous fiscal year)
- Adoption of the high-function plan " tripla Connect+ " by major hotel chains is progressing, leading to higher Average Revenue Per User (ARPU).
-
Low and Stable Churn Rate
- The monthly average churn rate remains at an extremely low level, with "tripla Book" at 0.5% and "tripla Bot" at 0.4% , demonstrating strong customer engagement.
6. Analysis of Cost Structure and Profitability
Looking at the standalone operating expense trend, Q3 expenses were 558 million yen (compared to 415 million yen in the same period last year). Personnel costs increased to 335 million yen due to the strengthening of high-end engineer recruitment, and communication costs (server fees, etc.) rose to 97 million yen in line with the increase in customers and transaction volume.
On the other hand, because the company has established its positioning as a vertical SaaS provider, it has achieved efficient marketing with lower advertising expenses compared to typical SaaS companies (Q3 advertising expenses: 8 million yen). As a result, the rapid expansion of sales directly led to an improvement in profit margins, with the Q3 operating profit margin reaching 34.5% .
7. Summary and Future Growth Strategy
tripla's Q3 FY2026 earnings can be summarized in the following points:
- The flagship product " tripla Book " drove high growth, supported by inbound demand and an improved take rate ( 1.65% ).
- The full-year operating profit forecast was revised upward for the second time this fiscal year to 1,029 million yen (nearly double the previous year).
- In addition to a solid revenue base in Japan, the company is steadily expanding across all of Asia , including achieving profitability in Indonesia and growth in the Philippines, Taiwan, and South Korea.
With its unique "fixed + usage-based" hybrid billing model, the company's business structure—which converts the revitalization of the accommodation market into direct revenue growth—has successfully realized both high growth and profitability this fiscal year.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.