

Link-U Group FY2026 Full-Year Financial Results & Mid-Term Management Plan 2030: A Deep Dive Analysis

StockClub
Published: Sep 14, 2026, 10:08 AM
Sentiment Analysis
Link-U Group FY2026 Full-Year Financial Results & Mid-Term Management Plan 2030: A Deep Dive Analysis
Link-U Group (Securities Code: 4446) has released its financial results for the fiscal year ending July 2026 (FY2026), alongside its new "Mid-Term Management Plan 2030" and the business plan for the fiscal year ending July 2027 (FY2027).
While the current fiscal year saw a temporary accounting loss due to impairment charges in the marketing business, the core Manga Platform and Content Production businesses achieved record-high quarterly revenues, demonstrating a significant improvement in underlying profitability. This report provides a detailed analysis of the FY2026 financial performance, the progress of strategic partnerships accelerating global expansion, and the growth roadmap toward FY2030.
1. FY2026 Financial Highlights: Structural Reform and Improved Core Profitability
For the full fiscal year of FY2026, consolidated revenue was 4,800 million JPY (99% of the previous year) , with an operating loss of 383 million JPY (compared to a profit of 327 million JPY in the previous year) . The primary cause of the operating loss was the recognition of a 745 million JPY goodwill impairment loss related to the consolidated subsidiary Romanz, recorded under other expenses as part of the company's "selection and concentration" strategy toward growth areas.
Conversely, adjusted operating profit , which reflects the true earning power excluding one-time factors, reached 403 million JPY (a significant 43% increase year-on-year) , with the adjusted operating margin improving by 2.6pt from 5.8% to 8.4% .
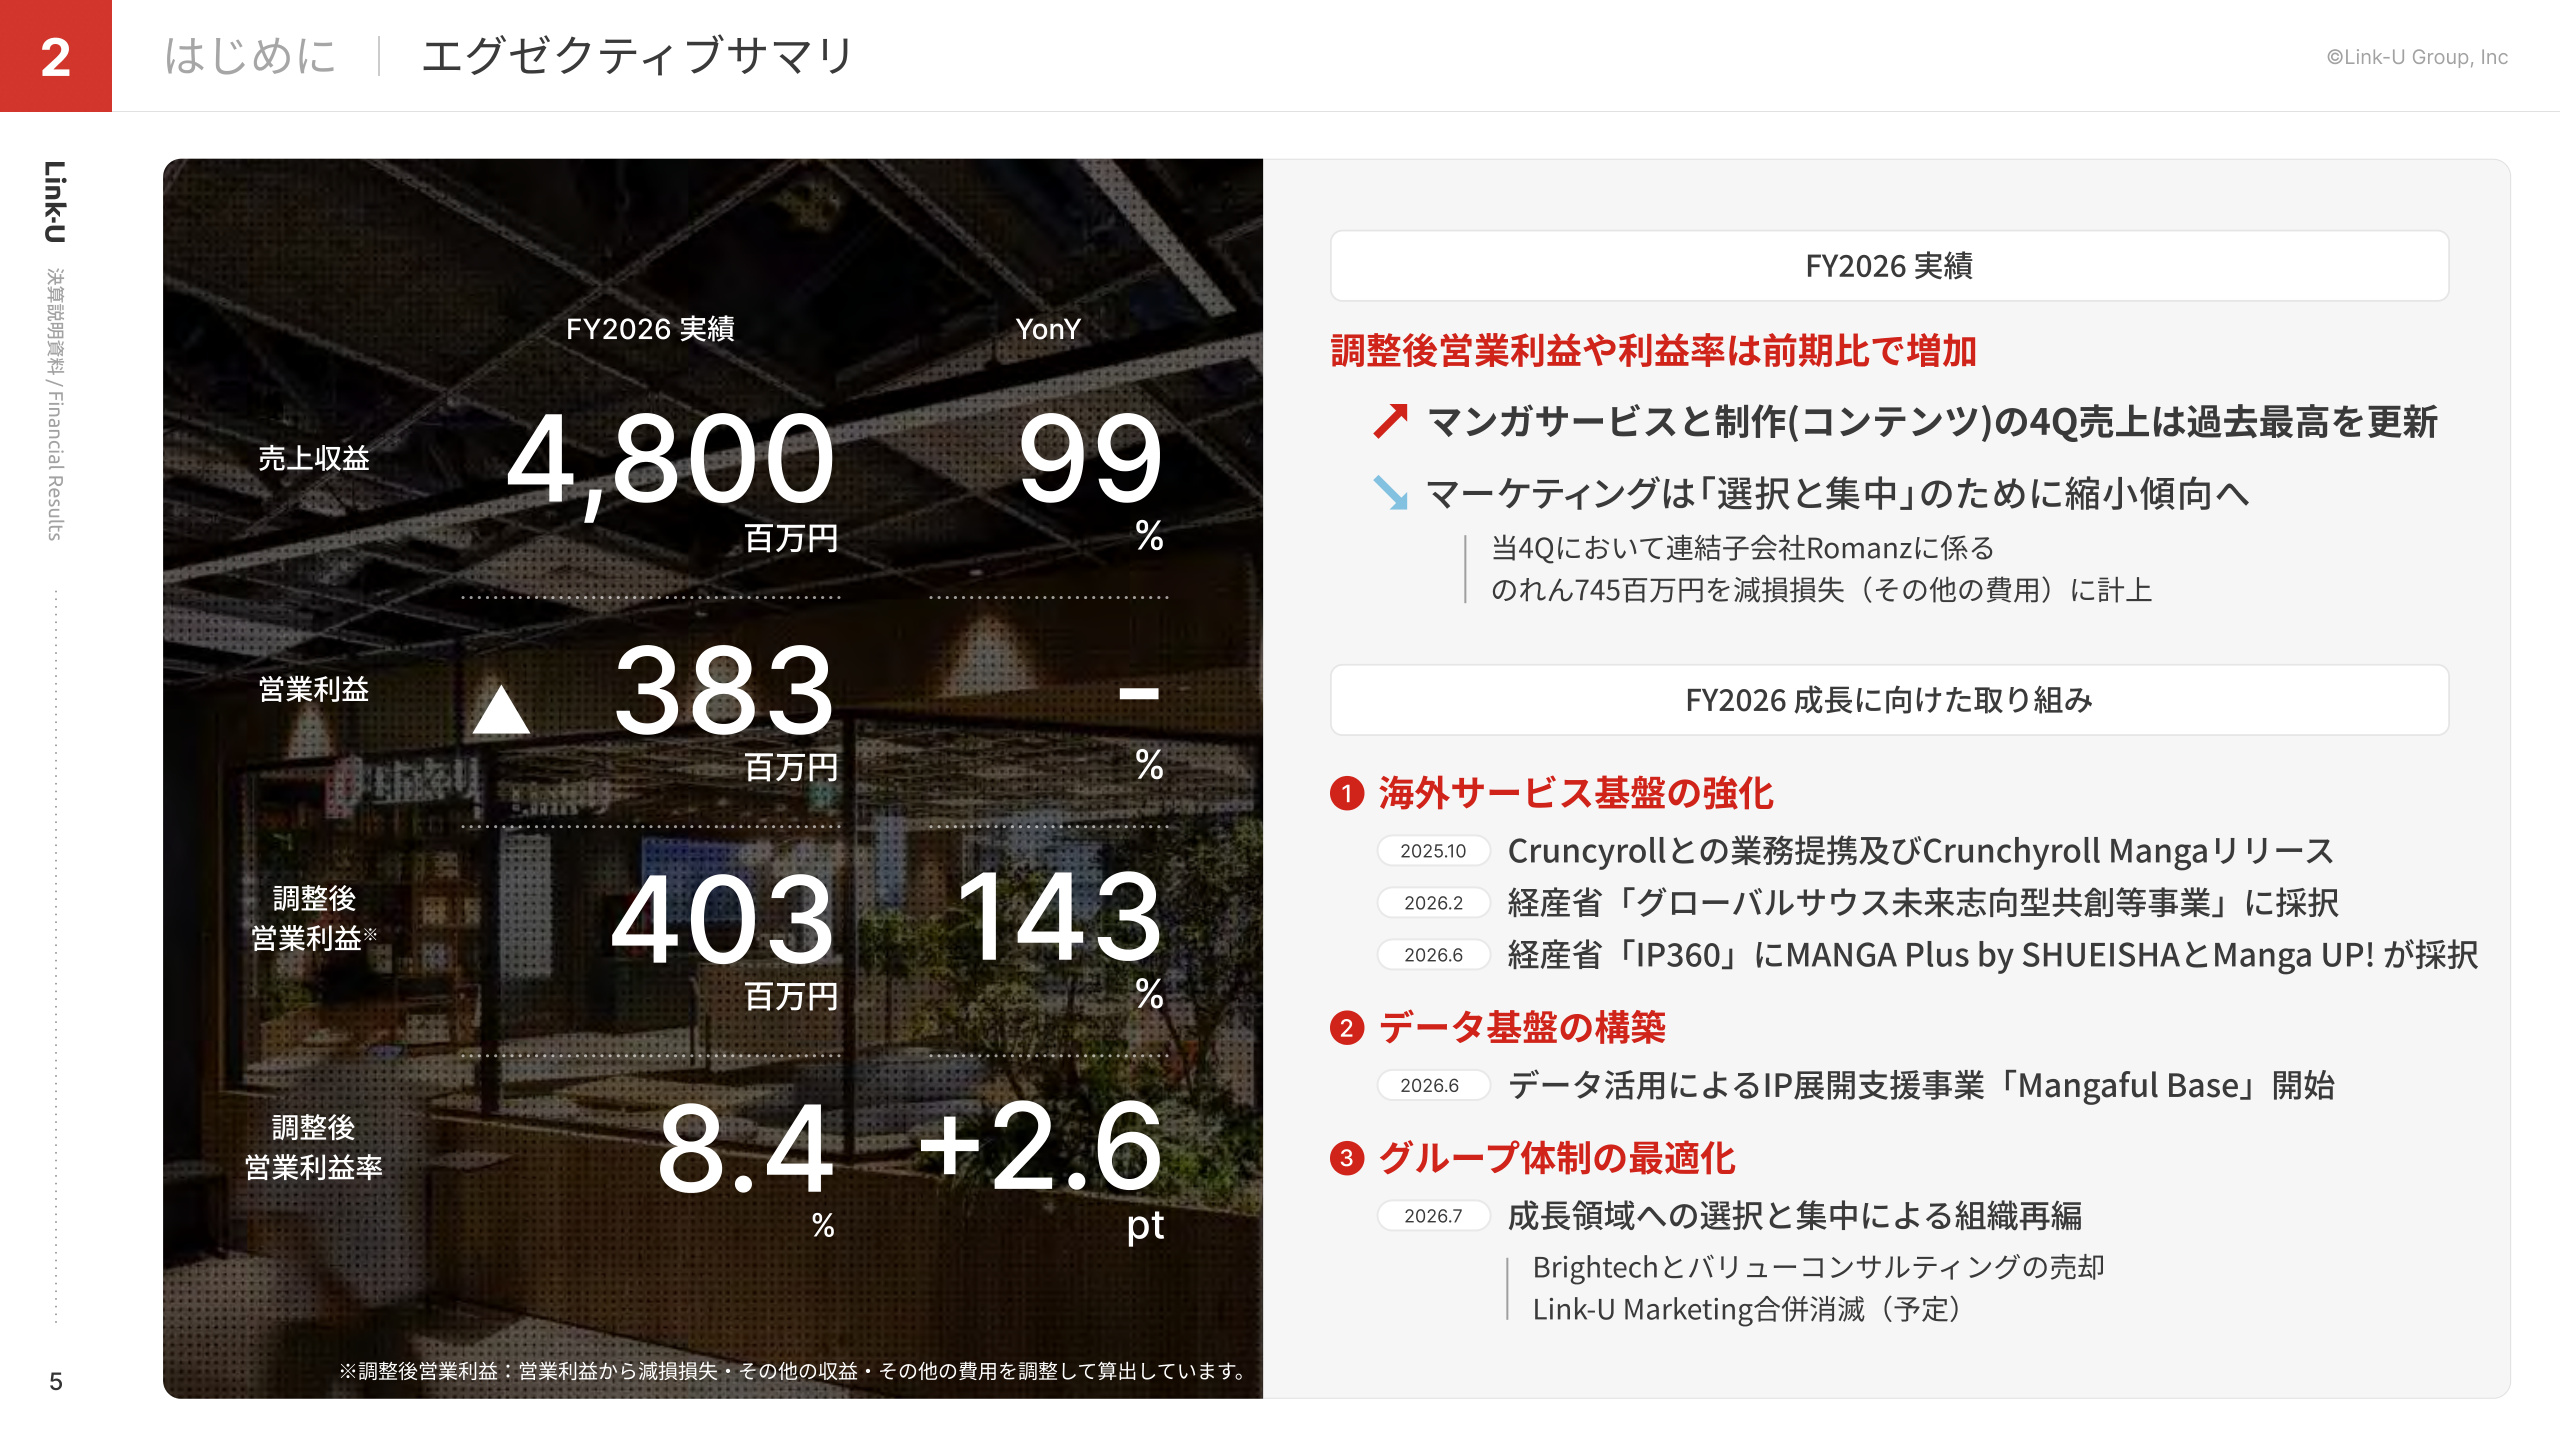
Slide Analysis: The Business Turning Point Indicated by the Executive Summary
The slide above provides a concise overview of FY2026. Although the headline operating profit shows a loss due to impairment charges, the core manga service and production businesses achieved record-high quarterly sales in Q4. Profitability has been strengthened through the optimization of sales-linked costs and advertising expenses, clearly reflecting the intent of structural reforms: shedding unprofitable and non-core areas while concentrating resources on global expansion.
2. Segment Trends and KPI Analysis
① Manga Service Business: Rapid Expansion of Overseas Ratio and Domestic Resilience
Sales in the Manga Service business grew quarter-over-quarter, reaching a record high of 739 million JPY in FY2026 Q4 . While maintaining resilience in the domestic market through advertising initiatives and operational efficiency, the overseas services have become the primary growth driver.
- Growth in Overseas Revenue : Overseas revenue saw a significant increase of 182% year-on-year .
- Overseas Revenue Composition : Increased by approximately 10pt from 7.9% in FY2025 Q1 to 17.5% in FY2026 Q4.
② Production Business (Technical Development + Content): Realization of IP Development Capabilities
Q4 sales for the Production business reached 401 million JPY (242 million JPY from technical development and 159 million JPY from content) , marking a record high. In addition to the strong performance of core titles in proprietary and co-developed content, the success of new titles contributed significantly to revenue growth.
③ Marketing Business: Intentional Contraction through Selection and Concentration
As a result of strategic reviews, quarterly sales in the Marketing business shrank from a peak of 362 million JPY in FY2025 Q1 to 111 million JPY in FY2026 Q4 . By processing the associated impairment losses within FY2026, the company has reduced the risk of future downward pressure on earnings.
3. Major Topics Accelerating Global Growth
Four key topics are driving the future growth of the Link-U Group:
- Capital and Business Alliance with Crunchyroll Through a partnership with the world's largest anime streaming platform, the company is promoting the expansion of "Crunchyroll Manga" and strengthening its localization framework.
- Selection for the Ministry of Economy, Trade and Industry (METI) "IP360 Subsidy" Shueisha's "MANGA Plus by SHUEISHA" and Square Enix's "Manga UP!," which the company develops and operates, were selected for METI's "Distribution Platform Expansion Support" (subsidy rate 1/2, cap of 3 billion JPY per company). With government backing, the company is accelerating the expansion of its overseas distribution infrastructure.
- Development of Shueisha's 100th Anniversary Project "MANGA MILLION" Contracted to develop "MANGA MILLION," a new global service by Shueisha. This involves building a large-scale infrastructure to deliver approximately 400 works (totaling 1 million pages) translated into over 100 languages to the world.
- Launch of New Data Business "Link-U Mangaful Base" Launched a foundational service that aggregates and analyzes domestic and international manga reading data to support global expansion and maximize IP value. The company is sequentially expanding collaborations with external partners, such as providing translation and distribution support for Bunkasha Publishing.
4. "Mid-Term Management Plan 2030": Targets and Growth Strategy
While the domestic manga market has entered a mature phase shifting toward profitability, the overseas market continues to grow at over 20% annually, driven by enthusiastic support for Japanese anime and manga. Capturing this market environment, the Link-U Group has formulated the "Mid-Term Management Plan 2030" with the core policy of "Maximizing IP Value."
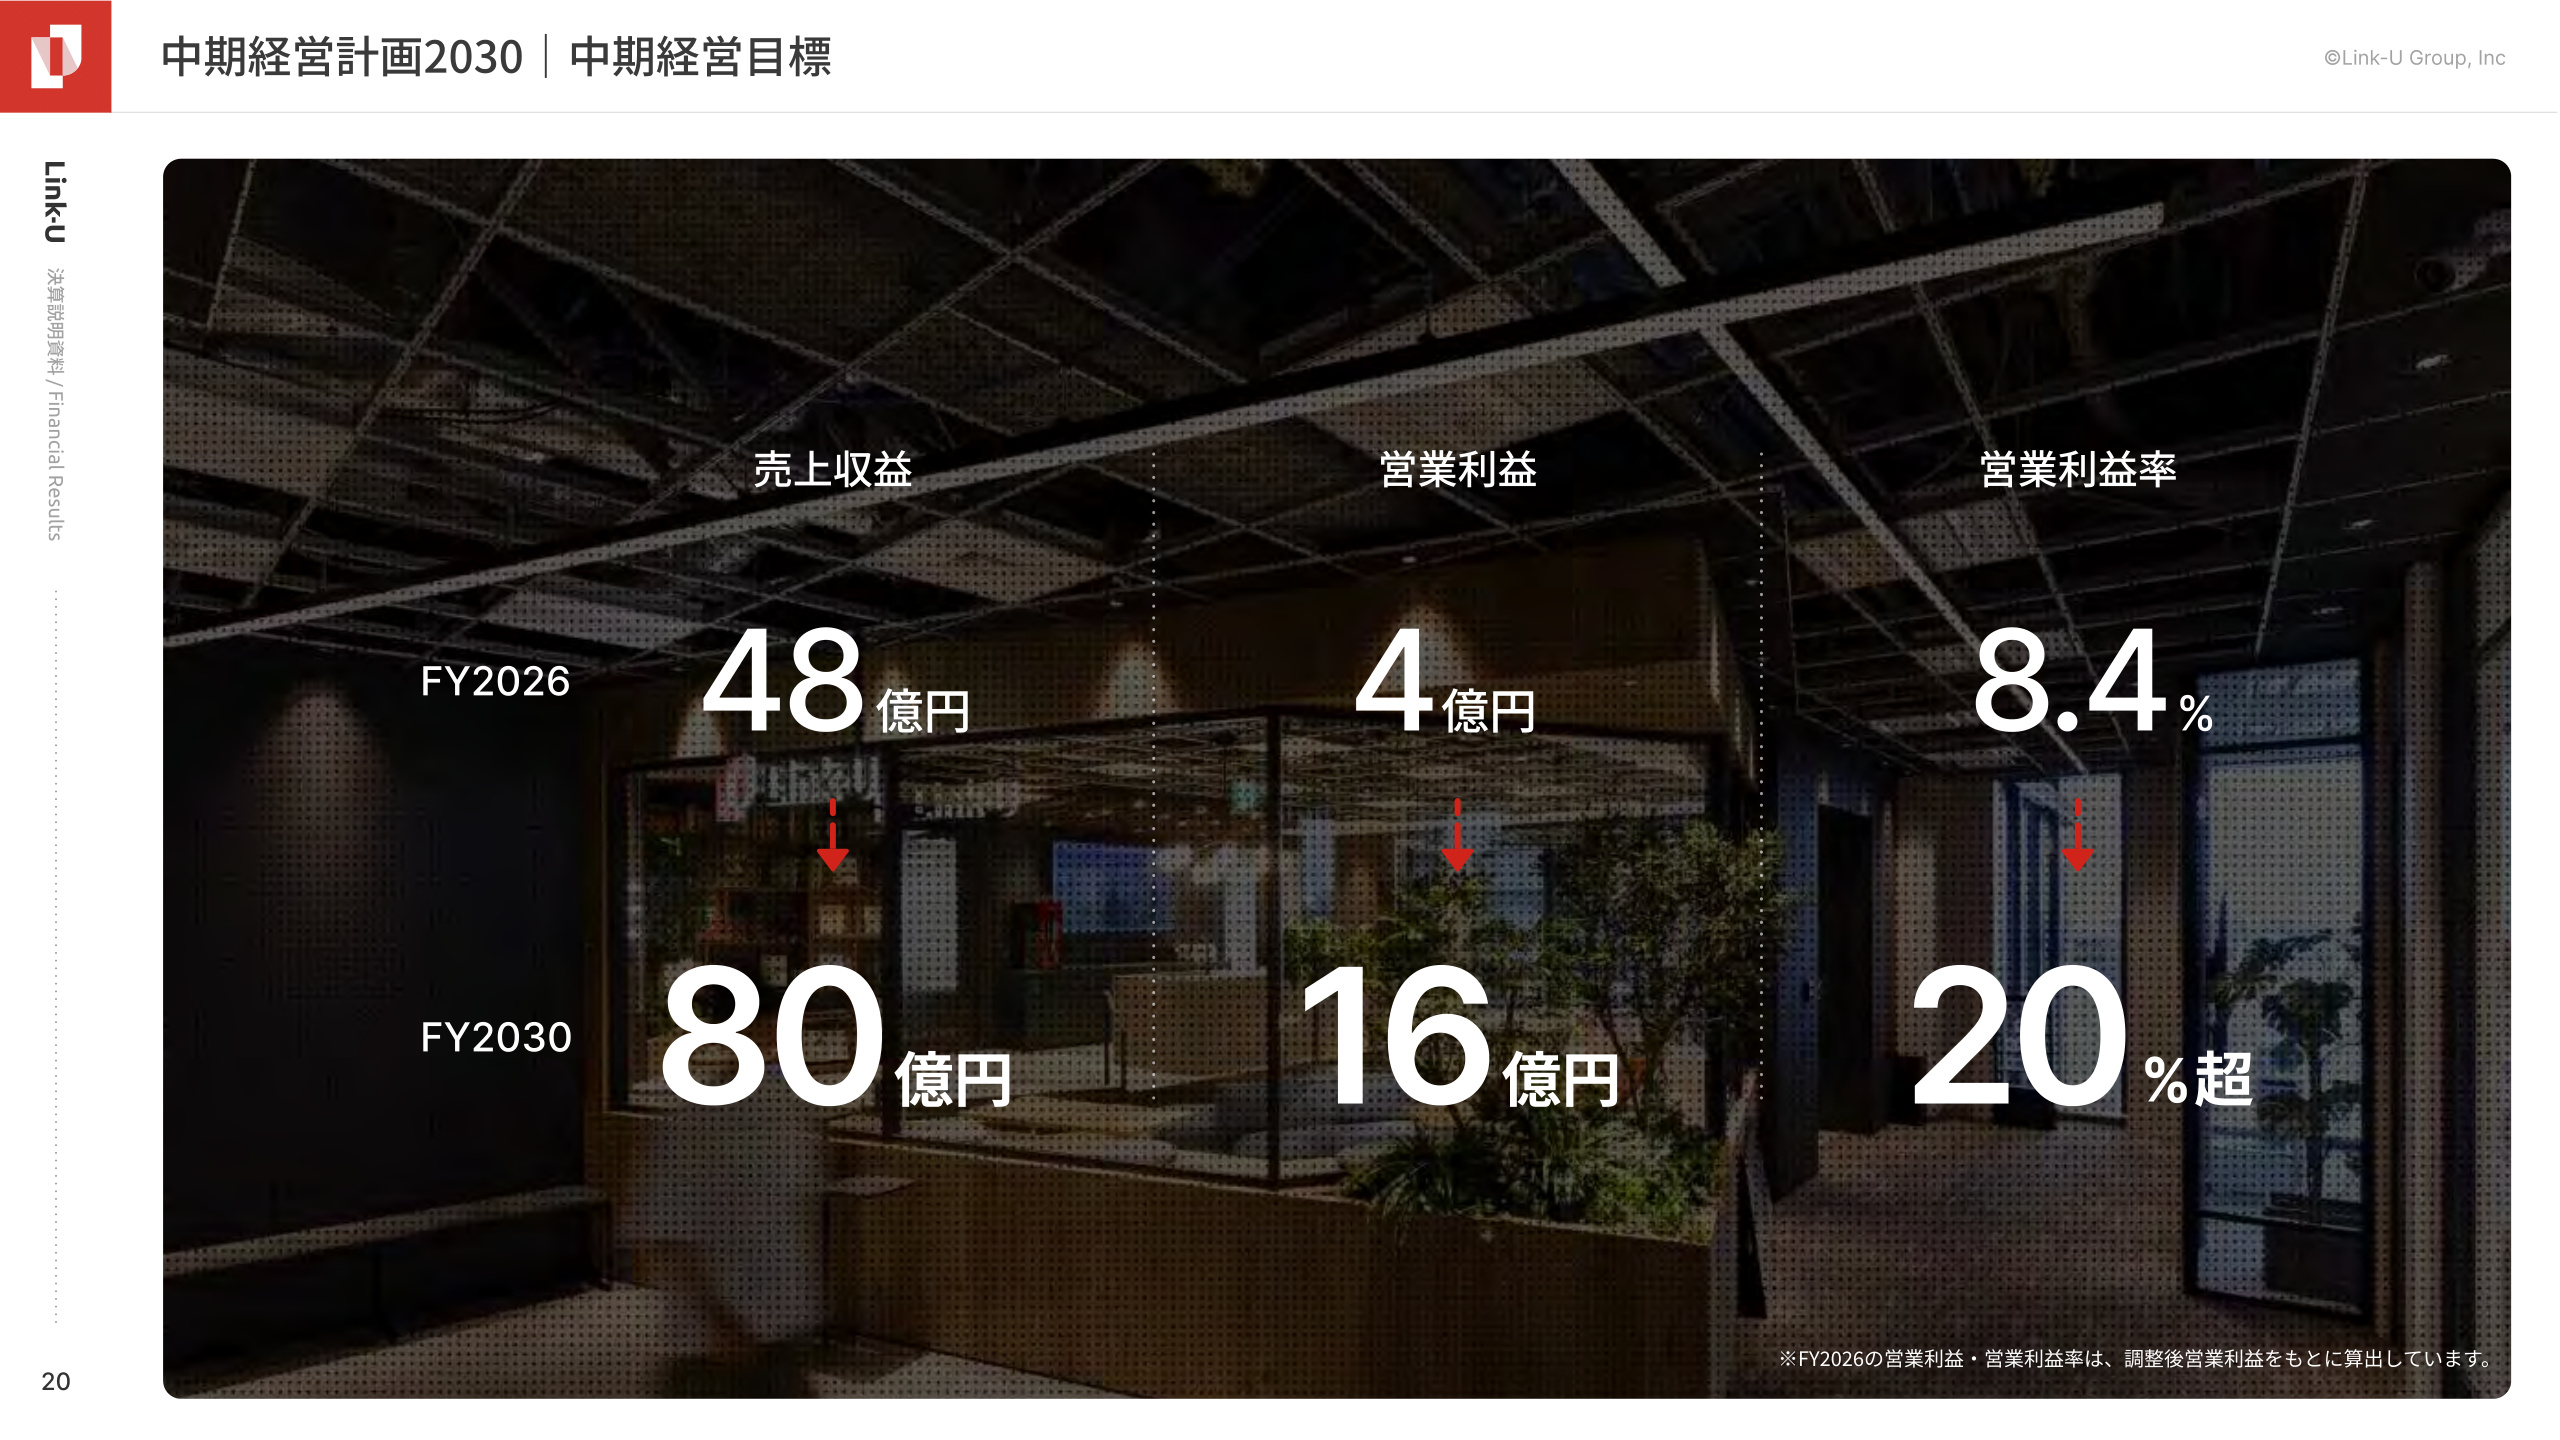
Slide Analysis: Ambitious Numerical Targets for FY2030
This slide illustrates the jump-up targets from FY2026 to FY2030:
- Revenue : 4.8 billion JPY → 8.0 billion JPY
- Operating Profit : 0.4 billion JPY (adjusted) → 1.6 billion JPY (4x increase)
- Operating Margin : 8.4% (adjusted) → Over 20% (+11.6pt or more)
This plan is not merely about scale; it explicitly declares a transition to a high-profit business model by combining "expansion of IP deployment areas (global expansion)" and "expansion of IP domains (anime, games, merchandise, etc.)," while maximizing platform operations and content revenue.
5. Organizational Restructuring and FY2027 Earnings Forecast
Optimization of Group Structure and Refresh of Business Segments
Starting in FY2027, significant organizational restructuring will be implemented to concentrate management resources on the IP domain:
- Divestment (sale) of Brightech Co., Ltd. and Value Consulting Co., Ltd.
- Reclassification of Compass Co., Ltd. to an equity-method affiliate.
- Absorption-type merger of Link-U Marketing Co., Ltd.
Accordingly, business segments will be updated into three categories: "MANGA PLATFORM (Domestic/Overseas Manga Services)," "CONTENT SOLUTION (New IP Domains/System Development)," and "LIFE STYLE (Proprietary Products/All-you-can-read services, etc.)."
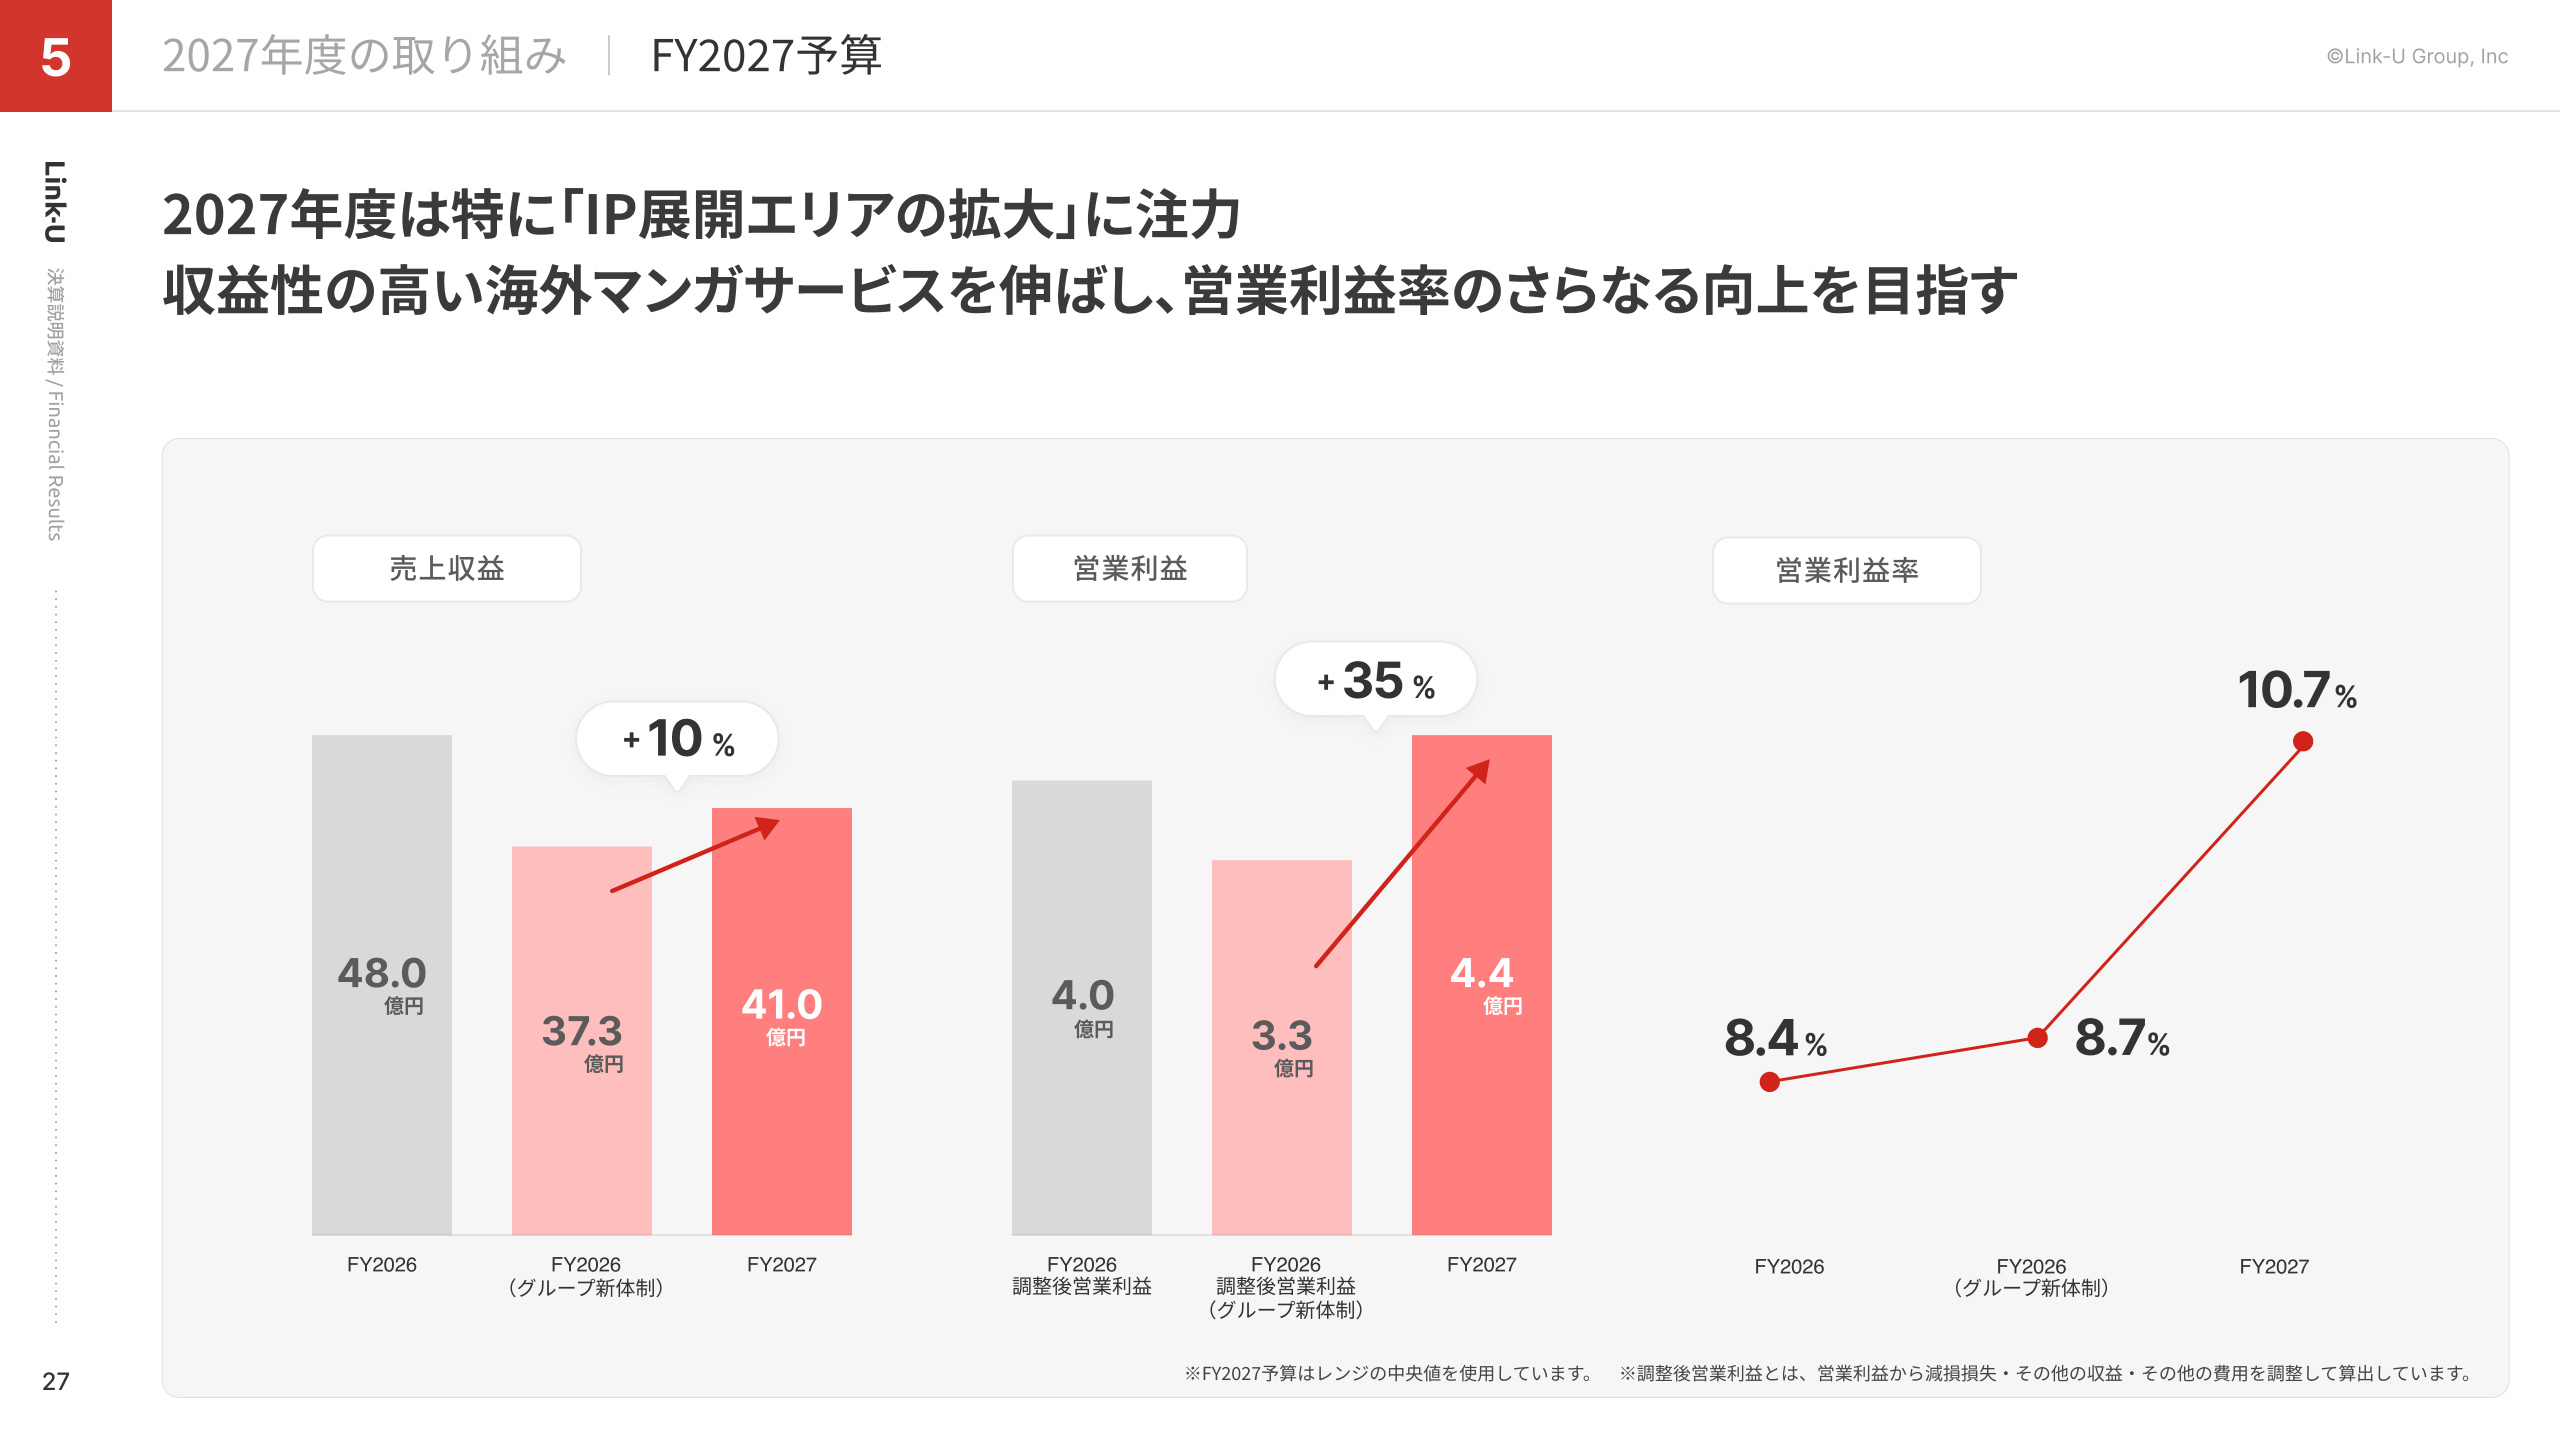
Slide Analysis: Revenue and Profit Growth Plan for FY2027
The slide above compares FY2026 actuals with the FY2027 budget based on the new group structure:
- Revenue : 3.73 billion JPY (new structure basis) → 4.10 billion JPY (+10% YoY)
- Operating Profit : 0.33 billion JPY (new structure basis) → 0.44 billion JPY (+35% YoY)
- Operating Margin : 8.7% (new structure basis) → 10.7% (+2.0pt)
By segment, MANGA PLATFORM is expected to grow from 1.61 billion JPY to 1.88 billion JPY , and CONTENT SOLUTION from 0.66 billion JPY to 8.3 billion JPY . By streamlining non-core businesses, the plan shows the transition to a lean and robust profit structure starting from the first year.
6. Conclusion
Link-U Group's FY2026 financial results served to clear out impairment losses associated with past investments, thereby cleaning up the financial and business slate while demonstrating the solid growth power of its core business, centered on overseas platforms.
Moving forward, the company will accelerate its efforts toward achieving "1.6 billion JPY in operating profit and over 20% operating margin by FY2030" by leveraging the effects of the Crunchyroll partnership, strengthening its overseas infrastructure with government subsidies, fulfilling large-scale Shueisha projects, and implementing profit-margin improvement measures under the new organizational structure.
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.