

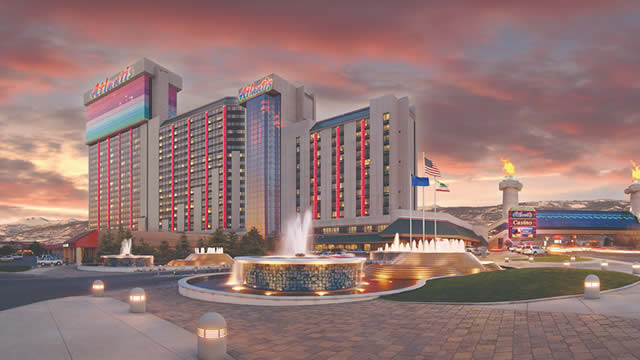
Monarch Casino: Hotels Are Carrying The Crown (Rating Upgrade)
Seeking Alpha
Published: Jul 24, 2026, 04:04 PM GMT+9
Sentiment Analysis
Monarch Casino delivered a 6% EPS beat, with hotel segment growth and robust cash generation, despite a 5% stock pullback post-earnings. MCRI's hotel revenue rose 13% YoY, now over 15% of total revenue, driven by regional visitation trends and recent property renovations. Adjusted EBITDA margin dipped 30 bps to ~37%, mainly due to higher F&B costs and wage inflation, but SG&A remains well-controlled. I upgrade to a moderate 'Buy,' targeting $125 short-term and $140–$150 medium-term, citing strong EPS growth and M&A optionality.
Monarch Casino (MCRI), which I affectionately call the 'Jewel of Regional Casinos,' reported its earnings yesterday. I had written that I expected a moderate EPS beat, with revenue at the same pace as the last.
Source: Seeking Alpha
This content is not intended as investment advice or a recommendation. Any opinions expressed are solely the personal views of each article.