

MU
マイクロン テクノロジー
MU
マイクロン テクノロジー
Bank of America (BofA) and UBS retained their 'buy' ratings on Micron Technology Inc (NASDAQ:MU), with both firms pointing to sustained memory demand, improving pricing and potential shareholder retur
Micron Technology, Inc. (MU) shares jump over 10,620% since Big Money first bought big in 1994.
Micron Technology faces moderating memory price increases as supply and demand rebalance, but AI data center demand remains robust. MU's gross margins are supported by long-term supply contracts, with
Micron Technology is rated a strong buy ahead of Q4, driven by robust memory demand and $100B in long-term take-or-pay contracts. Q4 revenue guidance of $50B includes an extra week, so true sequential
Michael Burry increased his bearish bets Tuesday on several tech and semiconductor names while adding to long positions in a handful of consumer and retail stocks.
Micron Technology, Inc. is set to deliver eye-popping earnings, driven by surging DRAM and NAND pricing well above historical levels. Despite robust fundamentals and massive free cash flow potential,
Micron Technology, Inc. is positioned for a breakout, with strong fourth-quarter earnings expected at the end of the month due to robust memory demand and positive EPS revisions. MU benefits from acce
AI's loudest voices spent the week telling everyone to slow down, and the market took them at their word. AI infrastructure names sold off into a month that traditionally is already unkind to stocks.
Micron Technology, Inc. is approaching its next earnings report, drawing investor focus to near-term performance. Key topics include earnings expectations, potential catalysts, and how MU's results ma
Micron Technology, Inc. is a Strong Buy due to AI-driven structural demand, tight supply, and robust competitive advantages. AI workloads are transforming memory demand from cyclical to structural, su
Micron Technology, Inc. remains a Strong Buy, supported by robust earnings, disciplined capital allocation, and new capacity coming online amid tight memory supply. MU's fiscal Q4 revenue guidance ben
Micron Technology, Inc. faces a pivotal FQ4 2026 earnings report amid record margin expansion and AI-driven demand. Consensus expects MU's net margin to reach a record of 70.7% in FQ4. I share the opt
Micron remains rated Hold as the earnings cycle decelerates and capital returns lag Korean peers. DRAM and NAND price growth is slowing, with inventory and end-demand pressures signaling a shift from
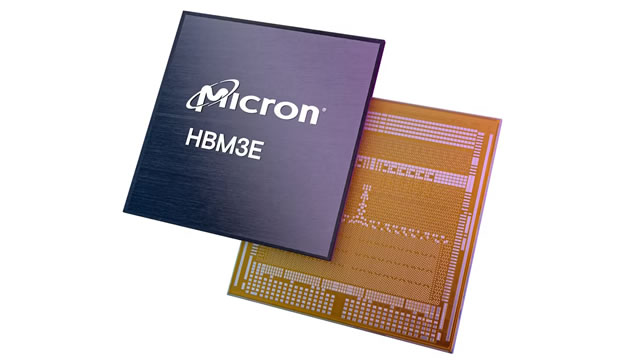
Micron Technology, Inc. is a core beneficiary of the AI infrastructure boom, uniquely positioned as the only major American DRAM and HBM supplier. MU's transition from commodity DRAM to engineered, ca
Micron Technology, Inc. is rated Buy, supported by robust fundamentals, multi-year strategic contracts, and a massive net cash position. MU's fiscal 2026 features explosive revenue and margin growth,
Micron (NASDAQ: MU) has suffered significant losses in the past month, losing roughly 8.5% of its value in a broader chip-market selloff. Looking toward the company's next earnings date, September 30,
Micron Technology, Inc. is becoming undervalued despite a 1300% return since my article from April 2025. MU has just announced the world's first 512GB DDR5 module, which secures a first-mover advantag
Micron Technology, Inc. remains a Strong Buy with Strategic Customer Agreements driving revenue durability and reducing cyclicality. MU's Q4 earnings are expected to beat both top- and bottom-line con
Signals from chart price action to analysts' sentiment point to another massive run for Micron NASDAQ: MU stock. While headwinds and hurdles such as market angst, profit-taking, and repositioning weig
The second quarter of 2026 was historic in its nature for the U.S. equity markets. The S&P 500 Index recorded 28% earnings growth in the quarter, the sixth consecutive quarter of double-digit growth.