

JAIC Q2 FY2027 Earnings Analysis: Progress in Business Restructuring Amidst Mid-Career Recruitment Challenges

StockClub
公開日時: Sep 15, 2026, 09:53 AM
Sentiment Analysis
1. Executive Summary and Performance Highlights
JAIC Co., Ltd.'s consolidated financial results for the first half (H1) of the fiscal year ending January 2027 show net sales of 2,142 million yen (92% of the previous year's level), an operating loss of 125 million yen (compared to a profit of 115 million yen in the same period last year), an ordinary loss of 127 million yen , and a net loss attributable to owners of the parent of 143 million yen . The progress rate against the full-year forecast (net sales of 5,024 million yen, operating profit of 254 million yen) stands at 42% .
On a quarterly basis, Q2 (May-July) net sales were 1,132 million yen (85% of the same period last year), with an operating loss of 47 million yen , showing a narrowing trend in losses compared to the 77 million yen loss in Q1. EBITDA for the first half, accounting for 59 million yen in depreciation and 32 million yen in goodwill amortization, was -26 million yen .
Performance varied by business segment. While the " Human Growth Business " (education and training) and " First Career Business " (new graduate recruitment support) recorded their highest H1 sales to date, the " New Career Business " (formerly Freeter support) saw a decline in revenue due to a deteriorating acquisition environment caused by an extreme seller's market.
2. Progress in Portfolio Transformation and Sales Composition
Over the past few years, the company has been working to break away from a revenue structure dependent on mid-career recruitment support, implementing structural reforms to expand new graduate recruitment and education/training through M&A and strategic alliances.
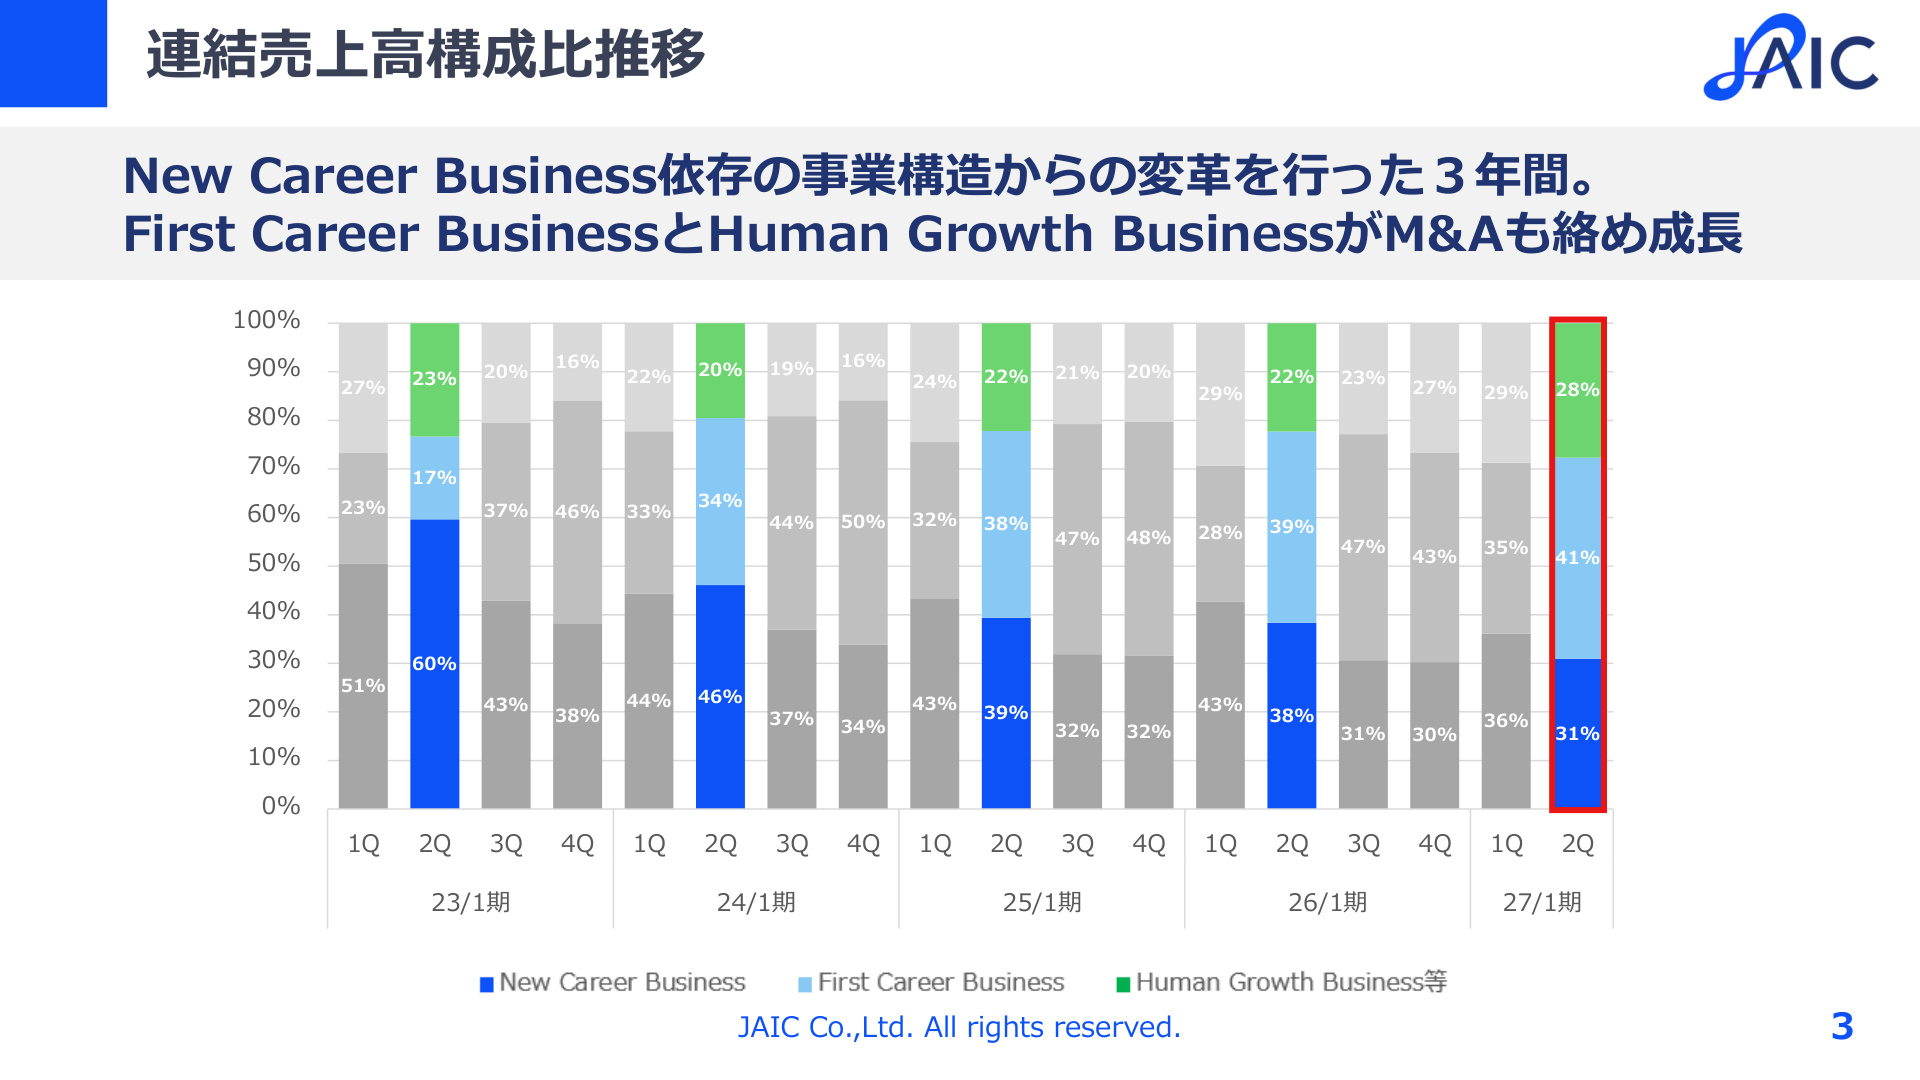
As shown in the consolidated sales composition trends above, the share of the "New Career Business," which accounted for 60% in Q2 FY2023, has fallen to 31% in the current Q2. Conversely, the "First Career Business" has grown to 41% , and the "Human Growth Business and others" to 28% , indicating a successful diversification of the portfolio into a robust three-pillar structure.
This shift in business composition reduces the risk of dependence on the external environment for a single business and demonstrates the establishment of the company's unique "education-integrated" hybrid model, which combines training with recruitment support.
3. Analysis of Major Business Segments and KPI Progress
(1) Education and Training: Human Growth Business & Kakedas Inc.
- World-Class Educational Content : The company deploys training content with global brands such as "The 7 Habits of Highly Effective People®," Dale Carnegie’s "How to Win Friends and Influence People," and Gallup’s "StrengthsFinder®." Focused efforts on acquiring large-scale clients have led to a threefold increase in sales to enterprise clients with over 2,500 employees compared to H1 FY2024.
- Rapid Growth of Kakedas Inc. : The career consultation platform operated by subsidiary Kakedas has surpassed 5,005 registered career consultants . By capturing demand related to the Ministry of Economy, Trade and Industry’s "Career Up Support Project through Reskilling," Kakedas’ standalone sales have maintained high growth at 115% year-on-year .
(2) Recruitment Support (New Graduates): First Career Business
- University Channels with Strong Barriers to Entry : The company has secured a track record of support at 204 universities through university career centers (145 schools) and the University Co-op Business Federation route (59 schools). Its greatest strength lies in leveraging a massive student infrastructure comprising 189 member co-ops and 1.52 million members.
- Rising Recruitment Unit Prices and Challenges : Driven by increased corporate hiring appetite, the unit price for job creation has risen to record levels (150% compared to H1 FY2023) . However, acquisition measures via the co-op route have become a challenge, with the number of job placements in H1 slightly decreasing to 370 (from 418 in the same period last year).
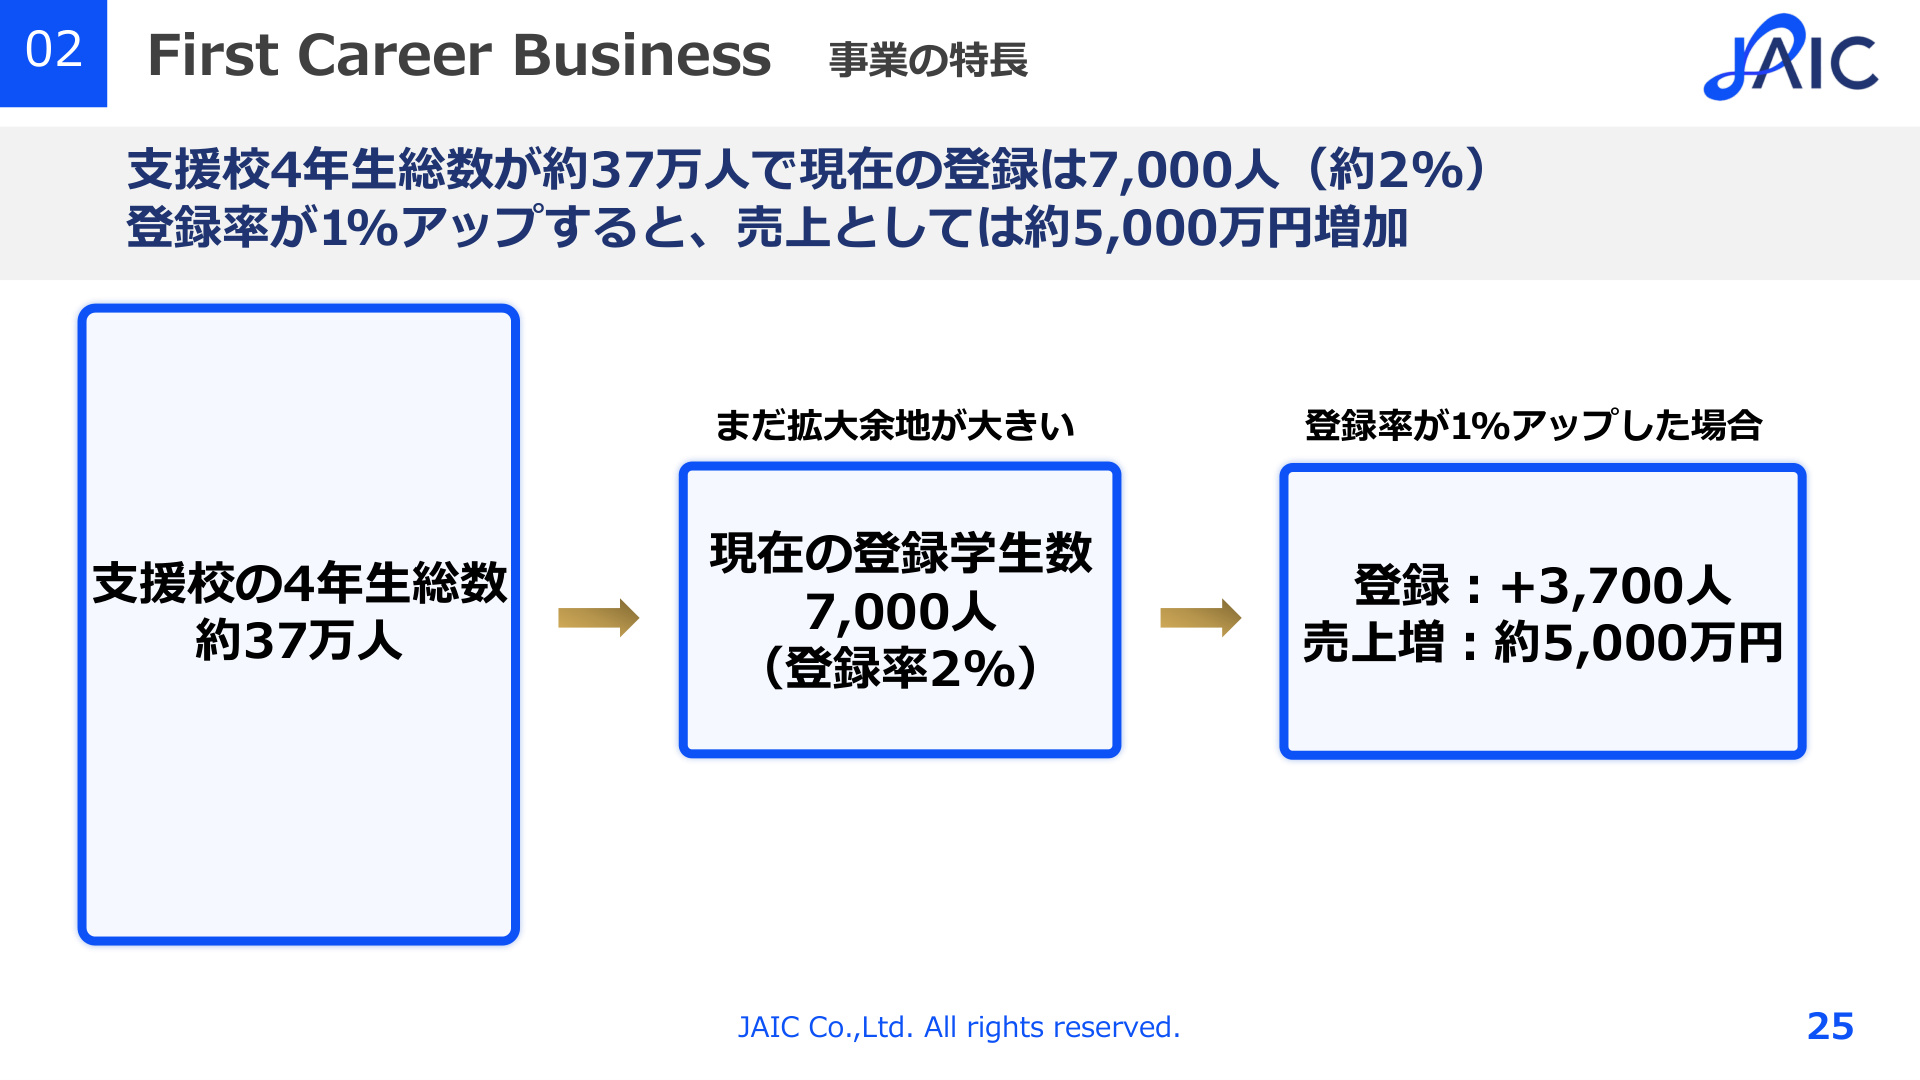
As shown in the slide above, while the total number of fourth-year students at partner universities reaches approximately 370,000, the current number of registered students is only about 7,000 (a registration rate of approximately 2%). It is estimated that a mere 1% increase in the registration rate would boost sales by approximately 50 million yen , indicating significant room for penetration within the existing alliance base.
(3) Recruitment Support (Mid-Career): New Career Business
- Delayed Response to Seller's Market and Soaring Acquisition Costs : Dependence on traditional web acquisition channels like affiliate and listing ads led to a surge in acquisition costs per job seeker, causing the number of registrants to fall from 23,284 in the same period last year to 19,575 . Consequently, the number of job placements dropped from 899 to 737 , acting as a drag on overall performance.
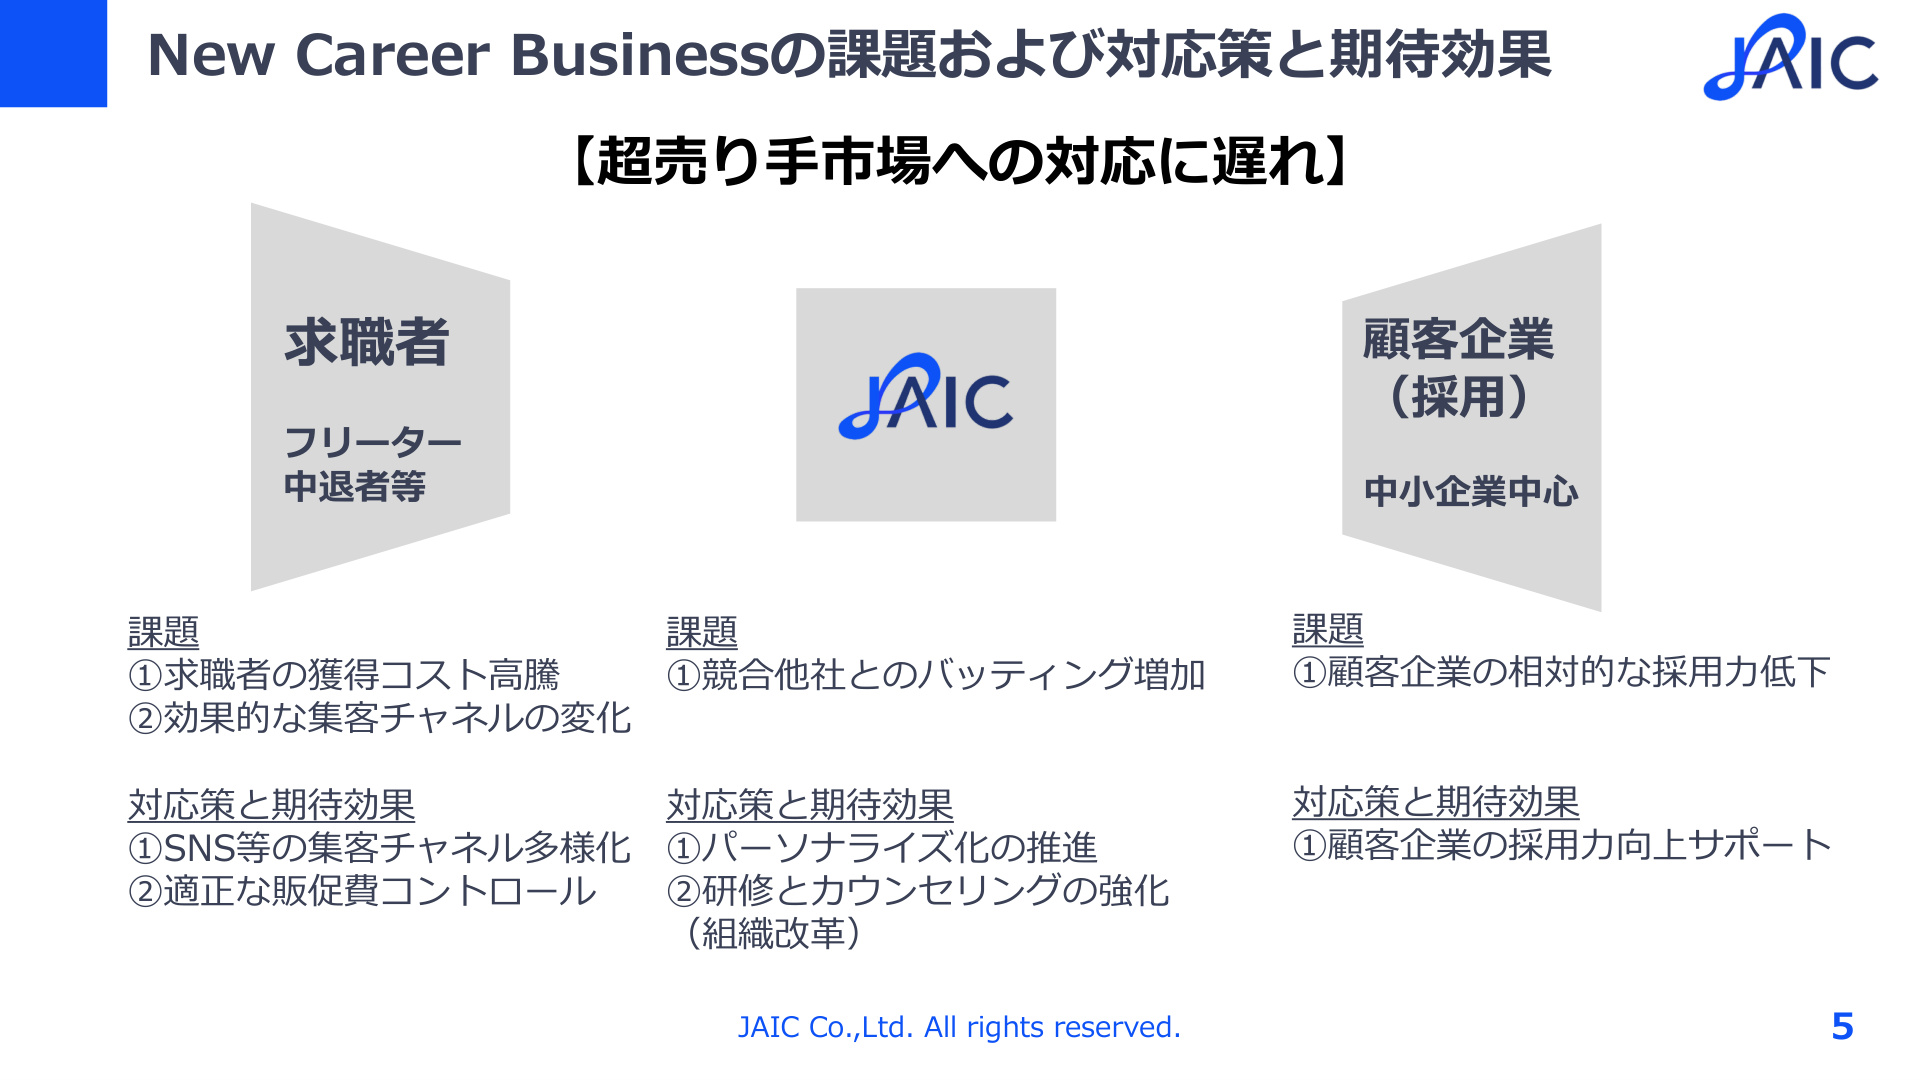
To address this, the company is diversifying into new acquisition channels such as SNS and optimizing advertising spend. On the matching side, it is promoting personalization by combining training and counseling. Furthermore, it is supporting client companies, primarily SMEs, in improving their recruitment capabilities to rebuild matching efficiency and profitability.
4. Future Growth Strategy and Shareholder Return Policy
To drive future growth, the company is pursuing the following priority strategies:
- Accelerating StrengthsFinder® Deployment : The company has launched self-analysis events for third-year university students, with 58% of participants coming from top-tier universities (Imperial universities, Waseda, Keio, Sophia, Tokyo University of Science, and MARCH), successfully expanding the quality of its target demographic.
- Expansion of Kakedas Works : Leveraging the network of over 5,000 registered career consultants, the company will accelerate outsourcing and matching businesses for corporate reskilling and human capital management support.
- Increasing Penetration in New Graduate Support : Leveraging the base of 204 partner schools nationwide, the company aims to increase student registration rates through more sophisticated marketing measures.
Regarding shareholder returns, the company maintains its plan for a year-end dividend of 55.00 yen per share and continues its shareholder benefit program conducted twice a year (mid-term and year-end) , aiming to balance long-term shareholder value enhancement with returns.
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。