

DAIWA CYCLE H1 FY2027 Earnings Analysis: Record-High Revenue Driven by Aggressive Store Openings and PB Expansion; On Track for Full-Year Profit Growth

StockClub
公開日時: Sep 14, 2026, 10:13 AM
Sentiment Analysis
DAIWA CYCLE H1 FY2027 Earnings Analysis
DAIWA CYCLE Co., Ltd. (Securities Code: 5888) , a specialized bicycle retailer, achieved record-high revenue for the first half of the fiscal year ending January 2027 (February 2026 – July 2026), fueled by continuous new store openings and growth in existing store sales. While operating profit saw a slight year-on-year decline due to upfront investment in store expansion and rising labor costs, the company is progressing at a pace that exceeds its initial projections.
This report provides a detailed analysis of current performance trends, factors impacting profit fluctuations, product and store strategies, and the full-year outlook, based on the company's earnings presentation materials.
1. H1 FY2027 Earnings Highlights
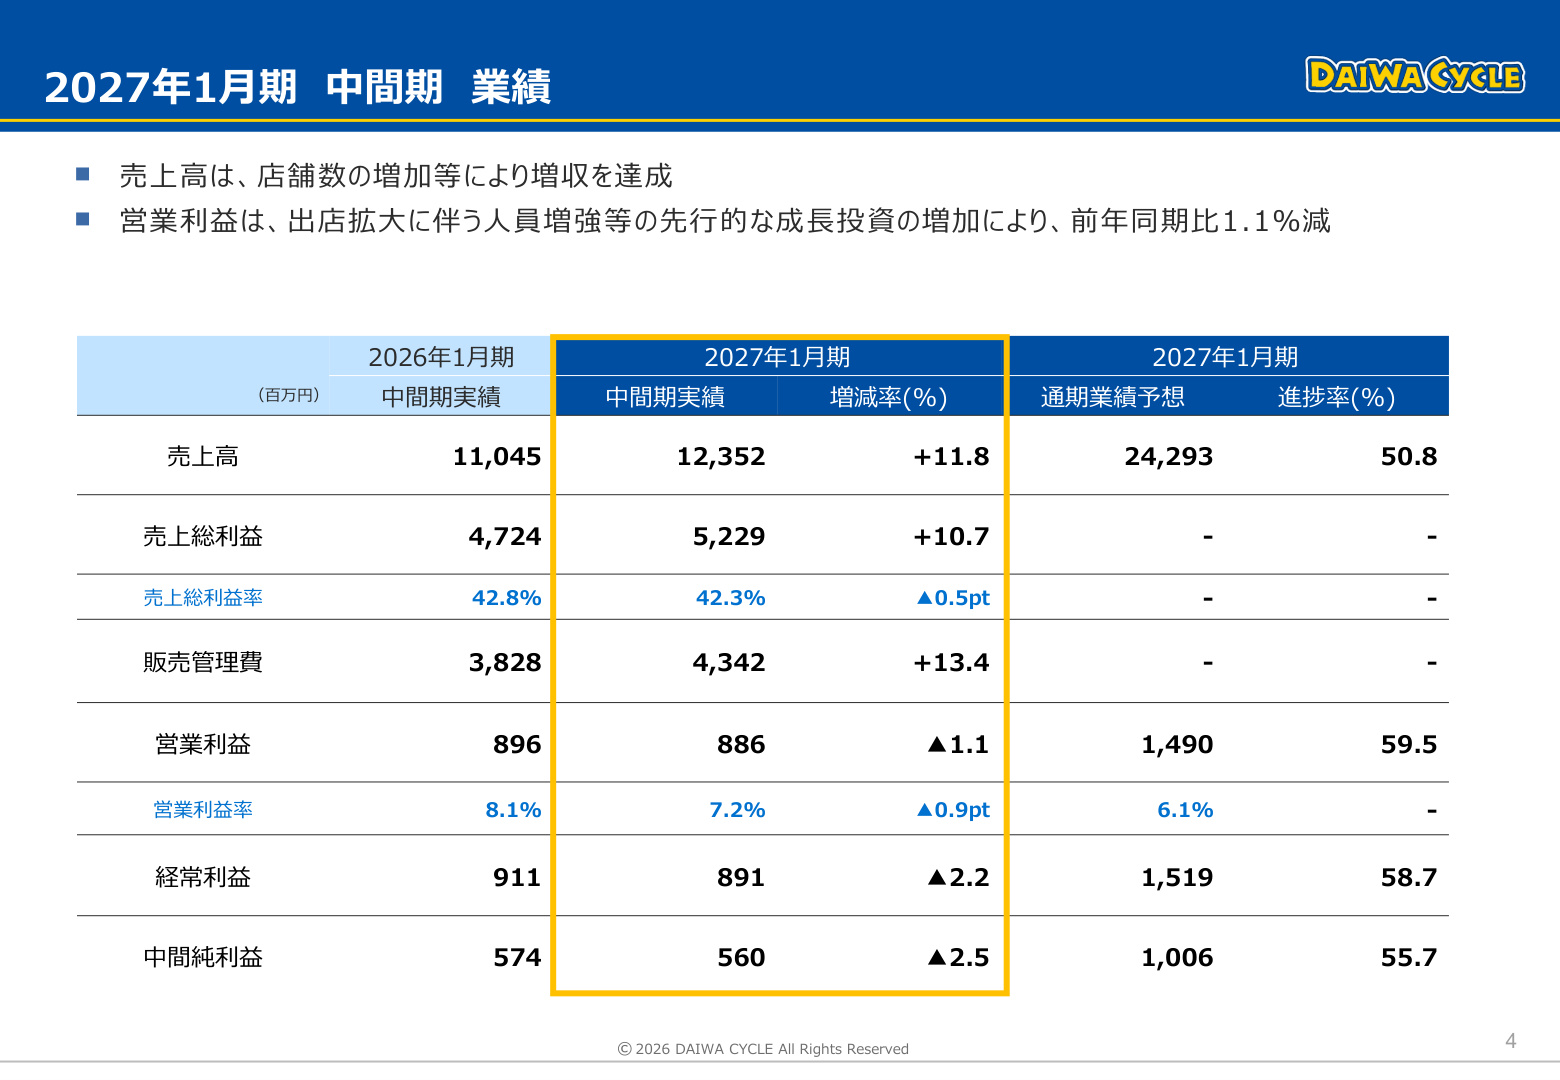
For the first half, the company reported revenue of ¥12.352 billion (+11.8% YoY) , gross profit of ¥5.229 billion (+10.7% YoY) , operating profit of ¥886 million (-1.1% YoY) , ordinary profit of ¥891 million (-2.2% YoY) , and net income of ¥560 million (-2.5% YoY) .
[Slide Commentary: H1 Performance and Full-Year Progress]
As shown in the slide above, the company achieved double-digit revenue growth compared to the same period last year. Although operating profit saw a marginal year-on-year decrease, the progress rate against the full-year forecast (¥1.49 billion) reached 59.5% , maintaining an exceptionally high level alongside the revenue progress rate (50.8%). Given the seasonal nature of the business, where profits are concentrated in the spring peak season (Q1–Q2), the company is structured to secure the majority of its full-year profit by the end of the first half.
Compared to initial forecasts, while revenue was 2.3% lower due to delays in new store openings, operating profit exceeded the initial forecast by 5.1% , thanks to improvements in the gross profit margin and the deferral of expenses associated with the delayed openings.
2. Sales Trends by Category and Gross Profit Margins
Sales by category for the first half recorded double-digit growth across all segments:
- Bicycles : ¥9.354 billion ( +11.3% YoY )
- Parts & Accessories : ¥1.768 billion ( +14.2% YoY )
- Other (Repairs, Insurance, etc.) : ¥1.228 billion ( +12.1% YoY )
In addition to the expansion of the store network (+19 directly managed stores compared to the end of the same period last year), existing store sales remained solid at 101.4% YoY (customer count 102.2%, average spend per customer 99.2%) . Although foot traffic slowed temporarily in June due to fewer holidays and poor weather (typhoons and the rainy season), the price increases for private brand (PB) products and certain repair services implemented from May onwards have been effective, putting the average spend per customer on a recovery trend.
Furthermore, the ratio of high-margin PB products rose to 33.8% (+1.1pt YoY) . Despite cost-push pressures from the weakening yen, the combination of an increased PB ratio and price revisions helped maintain a strong gross profit margin of 42.3% (+0.3pt vs. initial forecast).
3. Analysis of Operating Profit Fluctuations
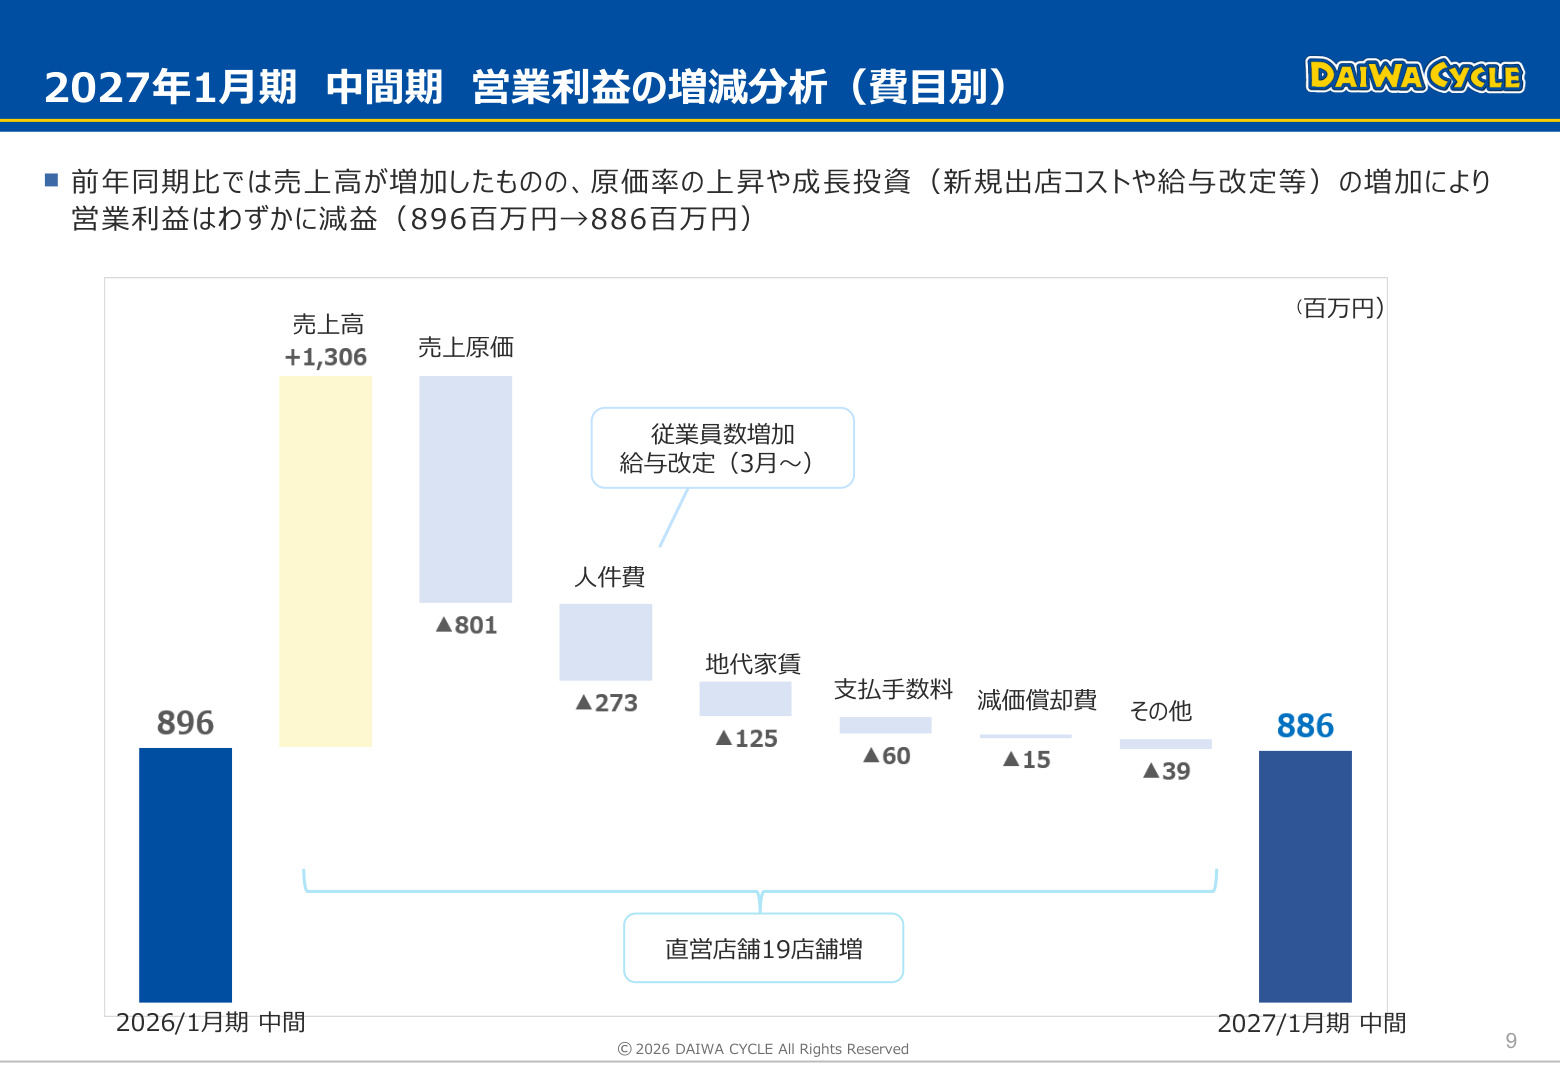
The primary reasons for the ¥10 million year-on-year decline in operating profit (from ¥896 million to ¥886 million) were increased SG&A expenses associated with aggressive store network expansion and human capital investment.
[Slide Commentary: Breakdown of Operating Profit Changes]
As the waterfall chart above illustrates, while the increase in revenue contributed ¥1.306 billion to profit growth , the following cost increases were incurred:
- Increase in Cost of Sales (¥801 million) : Driven by higher sales volume and foreign exchange impacts.
- Increase in Personnel Expenses (¥273 million) : Due to an increase in the number of employees following the addition of 19 directly managed stores, as well as higher unit labor costs resulting from the salary revision in March 2026 .
- Rent (¥125 million) and Depreciation (¥15 million) : Fixed cost increases associated with new store openings.
- Commission Fees (¥60 million) and Other (¥39 million) : Driven by the rising ratio of cashless payments and opening-related expenses.
These cost increases represent upfront growth investments for the company's "store network expansion" and "organizational strengthening" initiatives, aligning with the plan to scale the business.
4. Store Strategy and Area Development
At the end of the first half, the store network totaled 164 stores (160 directly managed, 4 franchised) . During the second quarter, the company opened a total of 5 new stores: 3 in the Kanto region (Funabashi Miyamoto, Hon-Atsugi, and Yokohama Edanishi) and 2 in the Kansai region (Kakogawa Yasuda and Sennan Shinge).
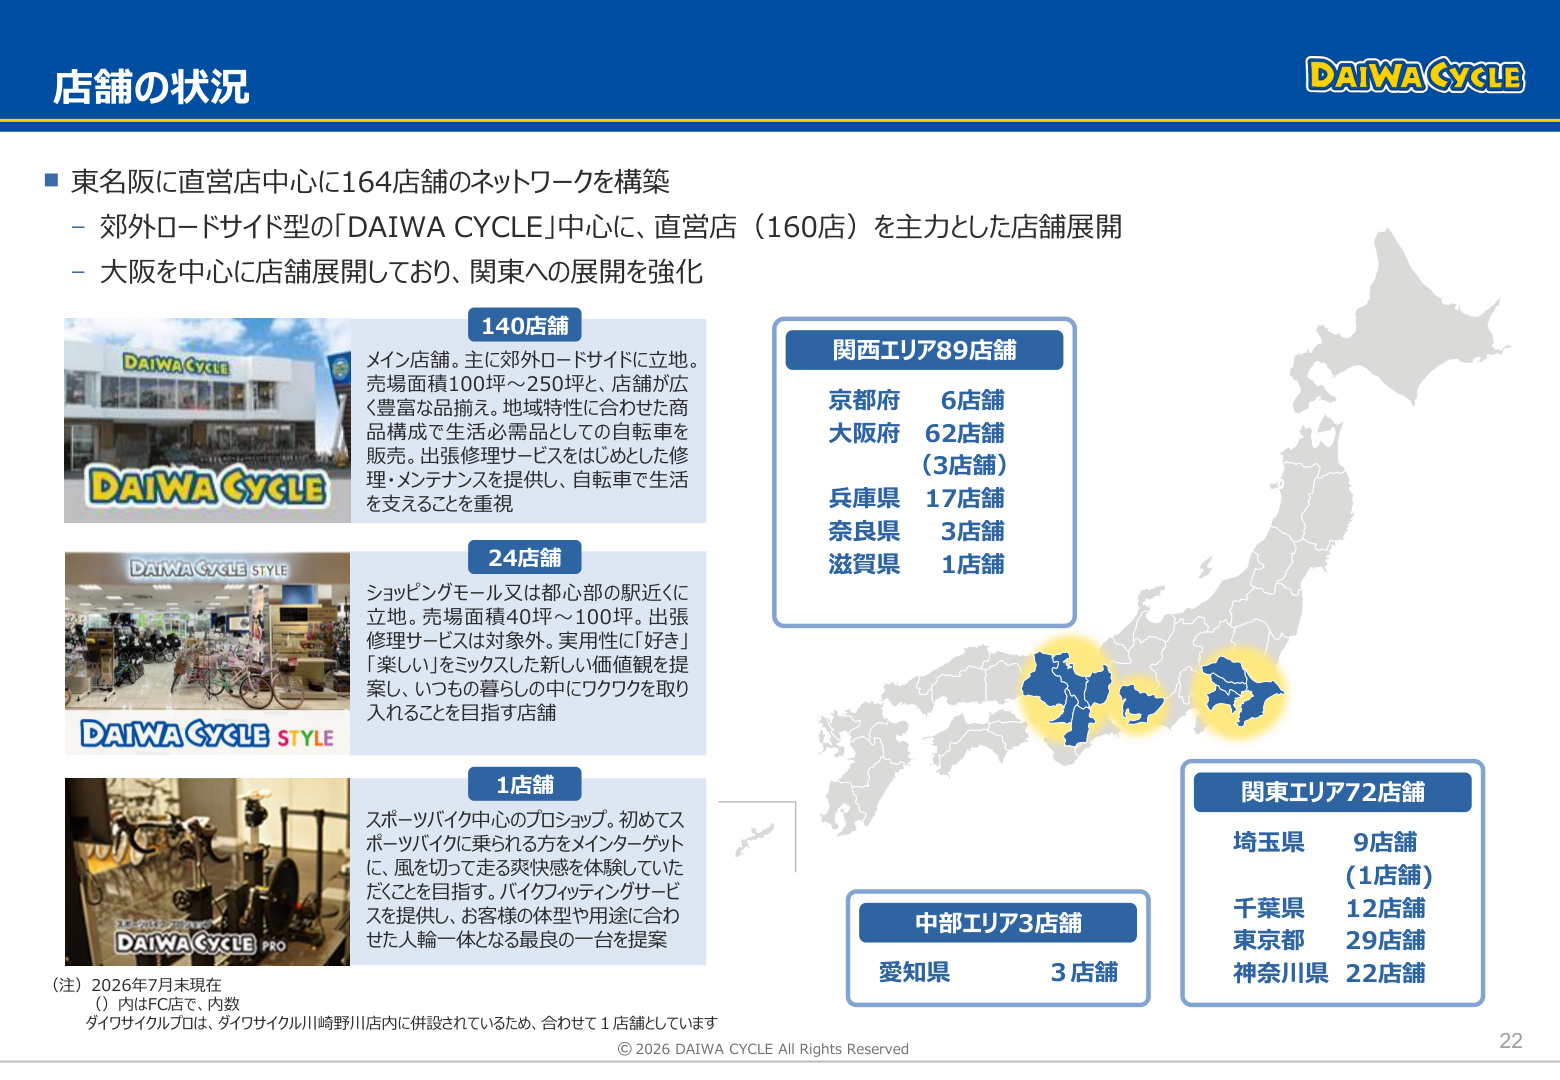
[Slide Commentary: Dominant Strategy and Store Formats]
A key feature of the company's store strategy is the active horizontal expansion of the dominant-store know-how cultivated in the Kansai region (89 stores) into the high-demand Kanto region (72 stores) .
The company operates primarily through three store formats:
- DAIWA CYCLE (140 stores) : Large flagship stores (100–250 tsubo) primarily located along roadside arterial roads.
- DAIWA CYCLE STYLE (24 stores) : Urban, trend-focused stores (40–100 tsubo) located in shopping malls or near train stations.
- DAIWA CYCLE PRO (1 store) : A specialty shop focused on sports bikes.
To ensure the efficiency of its " on-site repair service " (a service where staff travel to locations within a 2km radius of a store), the company employs a dominant-store strategy to seamlessly cover its service areas.
5. Full-Year Forecast and Future Growth Strategy
There are no changes to the full-year consolidated earnings forecast for the fiscal year ending January 2027.
- Revenue : ¥24.293 billion ( +15.1% YoY )
- Operating Profit : ¥1.49 billion ( +5.2% YoY )
- Ordinary Profit : ¥1.519 billion ( +5.9% YoY )
- Net Income : ¥1.006 billion ( +6.1% YoY )
- Annual Dividend Forecast : ¥73.0 (Payout ratio 20.0%)
The company plans a net increase of 20 stores (20 openings, 0 closures) throughout the year, bringing the total to 174 stores (170 directly managed) by year-end. The exchange rate is assumed to be 155 yen to the dollar.
[Key Focus Points and Growth Drivers]
- Expansion of High-Value-Added PB Products : The company plans to strengthen PB development for high-demand items like electric-assist bicycles in addition to standard bikes, aiming to boost gross profit margins.
- Monetizing After-Sales Services : The " Support Pack " (a package including theft insurance, free inspections, and repair discounts) has a high subscription rate, creating continuous customer touchpoints and recurring revenue after the initial vehicle sale.
- Demand from Legal Changes : With the introduction of "blue tickets" for bicycle traffic violations, demand for safety-related parts such as helmets and raincoats is expected to grow.
In pursuit of its mid-to-long-term goal of a "200-store structure," the company continues to drive business growth by balancing the pursuit of economies of scale through dominant store openings with improvements in service quality.
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。