

[Inuneko Seikatsu FY2027 Q1 Earnings] Achieving Significant Growth with +22.6% Revenue and +45.5% Operating Profit. A Comprehensive Analysis of Steady Subscription Growth, Strengthened Financial Foundation, and Mid-to-Long-Term Platform Strategy

StockClub
公開日時: Sep 14, 2026, 10:12 AM
Sentiment Analysis
Inuneko Seikatsu Inc. (Securities Code: 556A) reported strong results for the first quarter of the fiscal year ending April 2027 (May 2026–July 2026), driven by its core subscription model for premium pet food and care products. The company achieved significant year-on-year growth in both revenue and operating profit.
This report provides a multi-faceted analysis of the quarterly performance, including profit and loss structures, KPI trends, segment-specific developments, and the progress of the company's mid-to-long-term growth strategy, the "Pet Life Platform."
1. FY2027 Q1 Earnings Highlights
The consolidated results for the first quarter showed exceptionally strong progress as follows:
- Revenue : 1,287 million JPY (+22.6% YoY)
- Operating Profit : 185 million JPY (+45.5% YoY)
- Ordinary Profit : 184 million JPY (+44.1% YoY)
- Quarterly Net Profit : 116 million JPY (-16.5% YoY)
- Number of Subscription Members : 72,855 (+16.4% YoY)
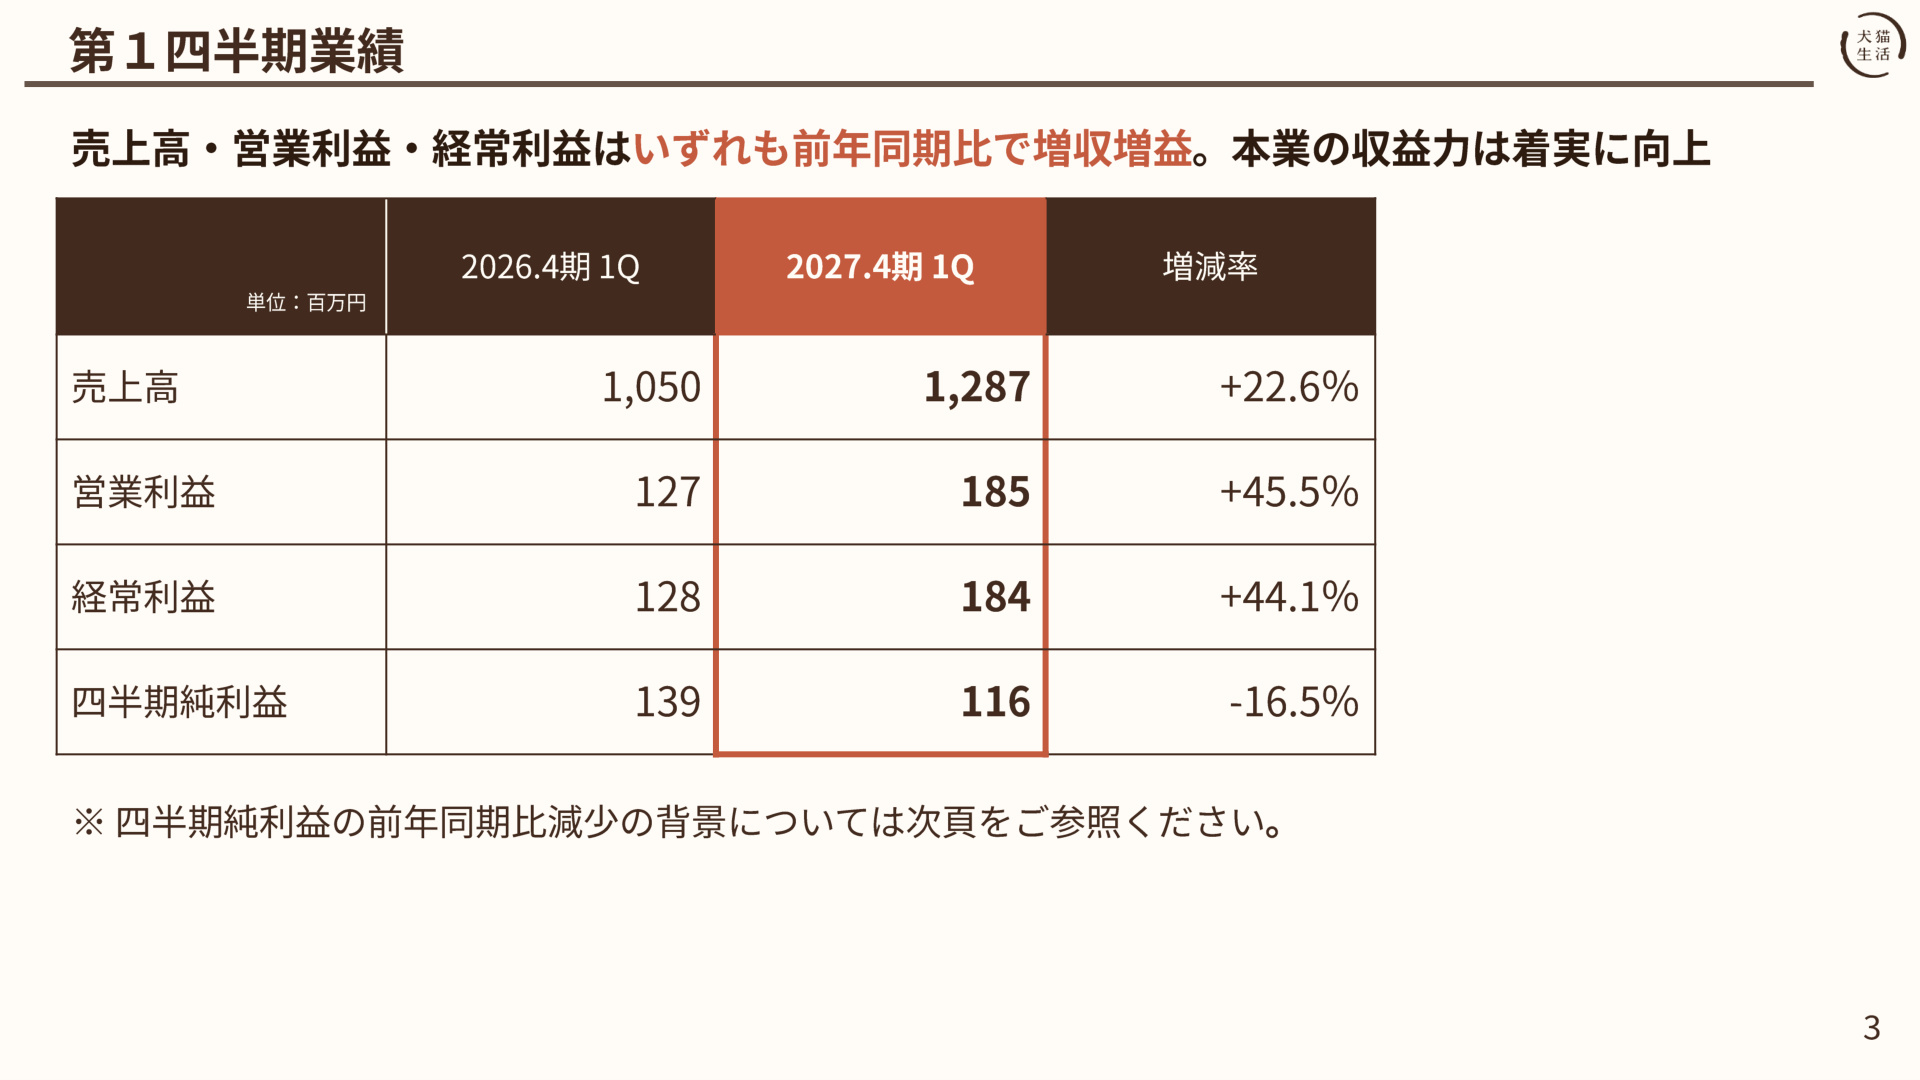
As shown in the slide above, the core pillars of the business—revenue and operating profit, which reflects the company's fundamental earning power—have expanded significantly. Revenue grew from 1.05 billion JPY in the same period last year to 1.28 billion JPY, while operating profit surged from 120 million JPY to 180 million JPY. The primary driver of this growth is the steady expansion of the number of subscription members to over 72,000 .
While quarterly net profit decreased by 16.5% YoY, this is due to a special factor in the previous year: a reduction in tax burden (a positive adjustment of 11 million JPY in corporate tax) resulting from the utilization of tax loss carryforwards. In the current period, the company recorded a standard tax burden (a total of -67 million JPY in corporate taxes and adjustments) due to stable earnings. Consequently, operating and ordinary profits, which represent core business profitability, maintained a robust growth rate exceeding 40%.
2. Progress Against Full-Year Forecasts and P&L Structure
The progress of Q1 results against the full-year consolidated earnings plan for FY2027 is as follows:
- Revenue Progress : 22.6% (Full-year forecast: 5,684 million JPY)
- Operating Profit Progress : 25.8% (Full-year forecast: 716 million JPY)
- Ordinary Profit Progress : 25.6% (Full-year forecast: 720 million JPY)
- Net Profit Progress : 24.8% (Full-year forecast: 468 million JPY)
As of the first quarter, all profit items have cleared the 25% benchmark, indicating that the company is tracking at a very steady pace toward its full-year targets.
P&L Trends and Profitability Improvement
The P&L structure for Q1 confirms that efficient operations have taken root:
- Cost of Sales Ratio : 25.8% (Improved by 0.4pt from 26.2% YoY)
- Advertising Expense Ratio : 29.5% (Decreased by 2.3pt from 31.8% YoY)
- Variable Cost Ratio : 14.2% (Improved by 0.3pt from 14.5% YoY)
- Fixed Cost Ratio : 16.1% (Increased by 0.8pt from 15.3% YoY)
- Of which, Donation Ratio: 2.1% (27 million JPY recorded)
- Operating Profit Margin : 14.4% ( +2.3pt improvement from 12.1% YoY)
By achieving revenue growth while curbing advertising expenses through improved acquisition efficiency and higher repeat rates among existing members, the operating profit margin improved significantly to 14.4% from 12.1% in the same period last year. It is worth noting that the company places "animal welfare activities" at the core of its management and achieved this high profit margin even while recording 27 million JPY in donations (2.1% of revenue) , which includes an amount equivalent to 20% of the previous year's ordinary profit (25 million JPY).
3. Segment and Channel Trends
The company's revenue is primarily driven by its "Life Sales Business," supplemented by the "Life Service Business" and overseas expansion.
① Life Sales Business (Revenue: 1,245 million JPY)
Accounting for the majority of total revenue, the Life Sales Business grew significantly from 1,004 million JPY in the same period last year. The breakdown by channel is as follows:
- Direct-to-Consumer (D2C) E-commerce : 1,081 million JPY (+19.6% YoY)
- Third-party E-commerce (Amazon, Rakuten, etc.) : 154 million JPY (+60.8% YoY)
- Wholesale : 9 million JPY (+112.8% YoY)
As shown above, the company's core D2C e-commerce business has formed a robust stock-based business model, with the number of subscription members increasing steadily on a quarterly basis. The net increase continued from 70,186 in Q4 of the 8th fiscal year to 72,855 in this Q1, supporting the continuous growth of D2C revenue. Furthermore, third-party e-commerce (+60.8%) and wholesale (+112.8%) are expanding rapidly, indicating progress in diversifying sales channels beyond D2C.
② Life Service Business (Revenue: 40 million JPY)
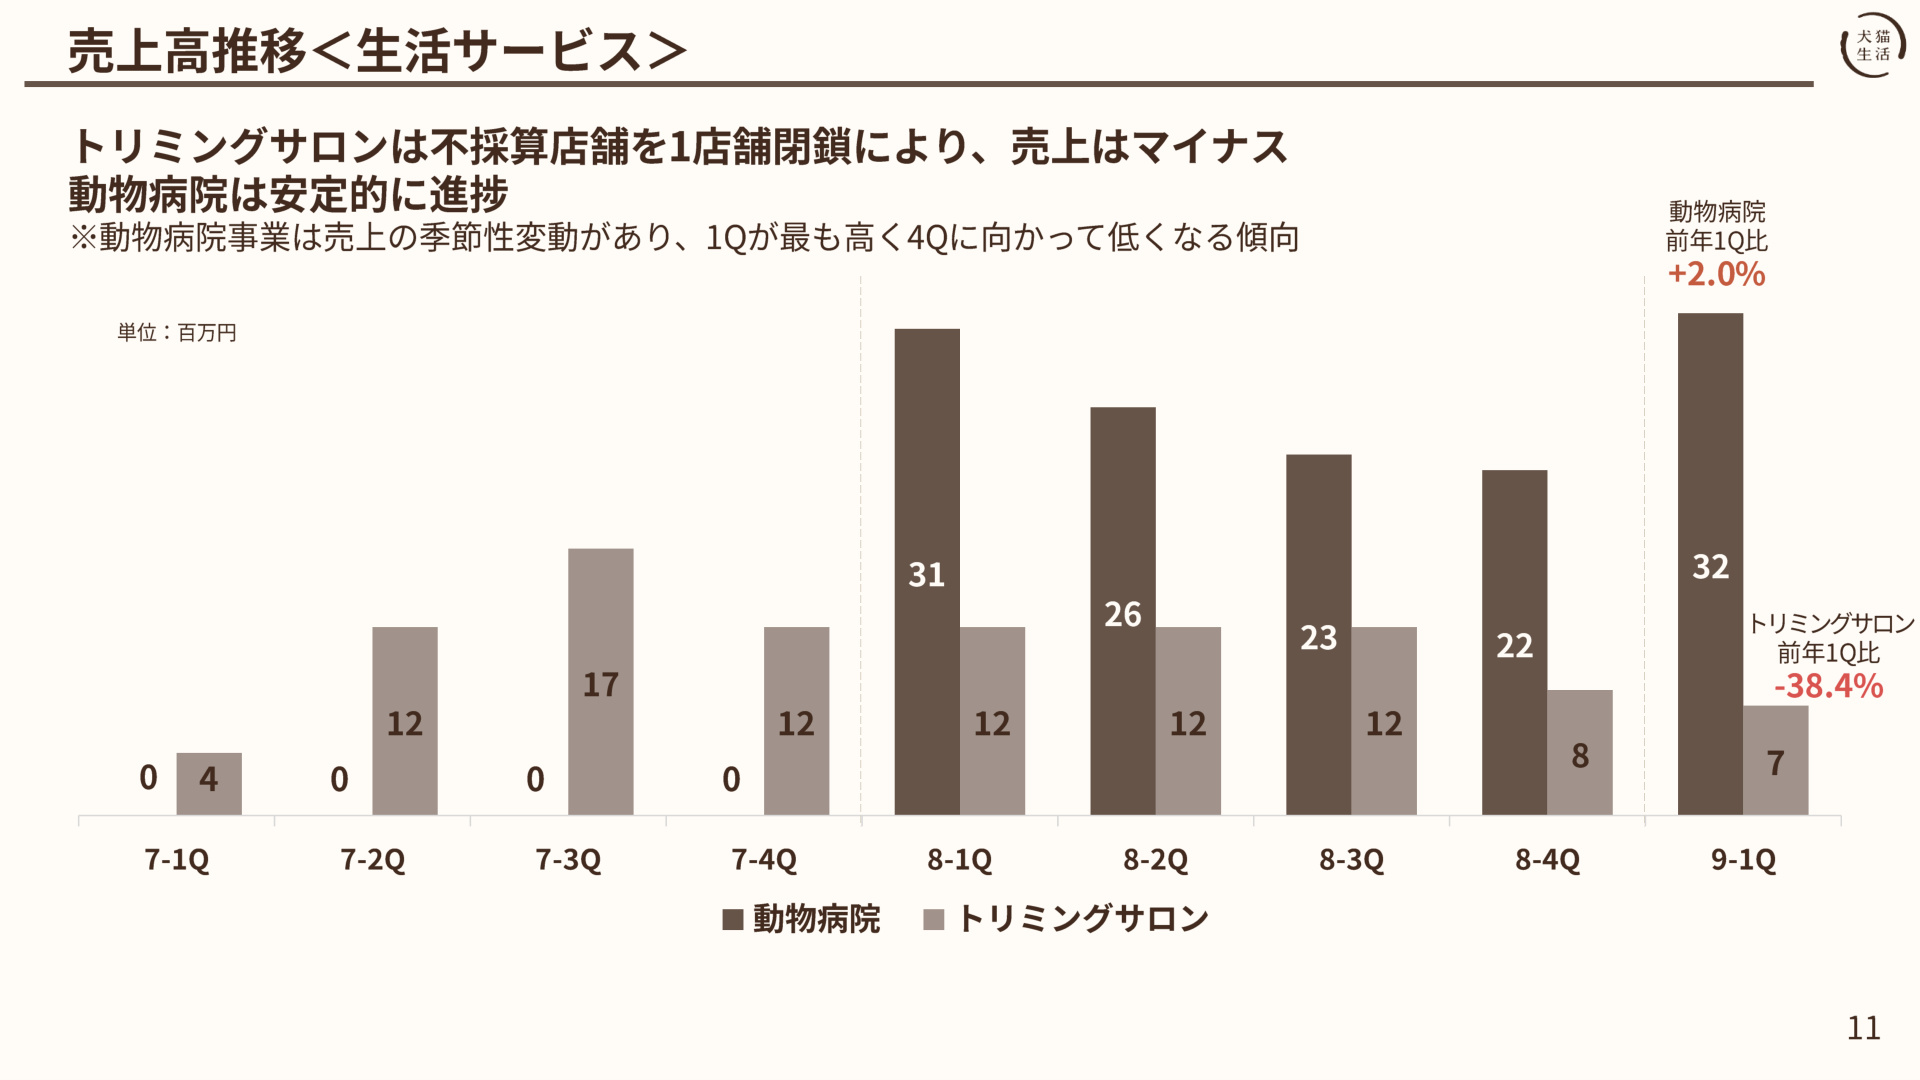
- Veterinary Clinic Business : 32 million JPY (+2.0% YoY)
- Remained stable despite seasonal trends where revenue tends to be higher in Q1 and lower toward Q4.
- Trimming Salon Business : 7 million JPY (-38.4% YoY)
- Experienced a temporary decline due to the closure of one unprofitable store in the previous fiscal year, but the company is proceeding with a portfolio restructuring that prioritizes profitability.
4. Solid Financial Foundation (B/S Analysis)
As of the end of Q1 FY2027, the company maintains an extremely healthy financial position.
- Total Assets : 2,670 million JPY (+12.0% from previous year-end)
- Cash and Deposits : 1,721 million JPY (Abundant cash position, accounting for approx. 64% of total assets)
- Net Assets : 2,152 million JPY (+21.1% from previous year-end)
- Equity Ratio : 80.6% ( +6.1pt improvement from 74.5% at previous year-end)
- Interest-bearing Debt Ratio : 2.6% (Effectively debt-free management)
With the accumulation of retained earnings, the equity ratio has exceeded 80%, ensuring sufficient investment capacity (cash) to execute aggressive M&A, new business investments, and product development.
5. Growth Strategy Progress and Topics
The company aims to build a "Pet Life Platform" that covers everything from food to medical care, salons, and other infrastructure in the mid-to-long term.
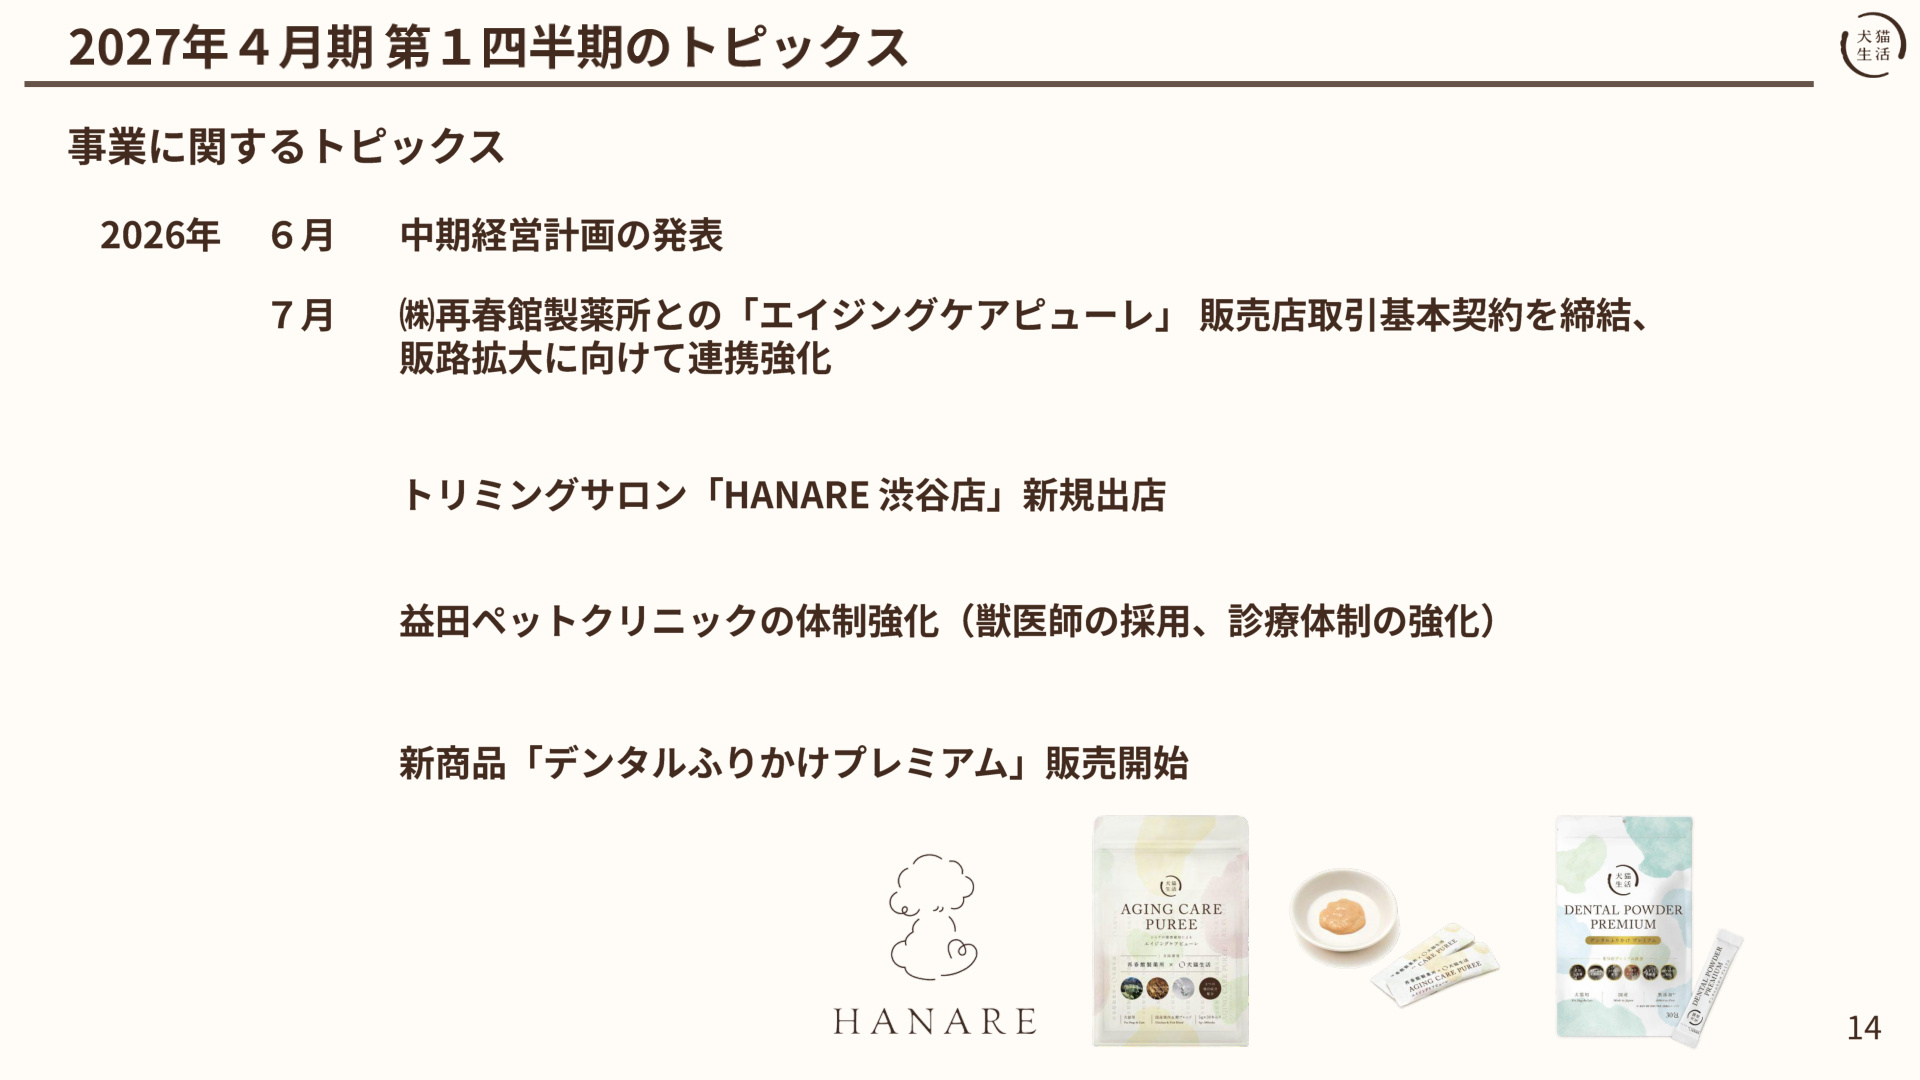
Specific progress in the three pillars of the growth strategy during Q1 is as follows:
① Expansion of Retail Wholesale (Accelerating Nationwide Rollout)
- Strengthening retail sales as a customer touchpoint following D2C. The number of stores carrying the products expanded rapidly from 160 at the end of the previous fiscal year to 197 at the end of Q1.
- Promoting O2O (Online-to-Offline) synergies by using retail-exclusive products and trial sizes to build brand awareness and acquire new customers in physical stores, then guiding them to D2C subscriptions.
- Additionally, the company is strengthening its sales partnership with Saishunkan Pharmaceutical Co., Ltd. , a major cosmetics mail-order company. Direct retail sales of the co-developed product "Aging Care Puree" by Saishunkan are scheduled to begin this autumn.
② Promotion of Veterinary Clinic M&A (Paving the way for a 50-clinic nationwide network)
- Actively pursuing M&A to capture business succession needs of high-quality local veterinary clinics.
- In addition to strengthening the medical system at the existing Masuda Pet Clinic through the recruitment of veterinarians, the company plans to conclude an M&A agreement in September 2026 for the "Moriya Forest Animal Hospital" (annual revenue of approx. 87.5 million JPY) in Moriya City, Ibaraki Prefecture, marking progress toward a nationwide network.
③ New Product Development and Value-Added Services (LTV Improvement Measures)
- In July 2026, the company launched "Dental Furikake Premium," an upgraded version of its flagship dental care supplement. By increasing the number of active ingredients from 7 to 9, the company is meeting customer needs while promoting higher unit prices and cross-selling.
④ Expansion of Life Service Hubs and Shareholder Returns
- In July 2026, the company opened a new original brand trimming salon, "HANARE Shibuya," produced in-house. This initiative aims to provide care as a wellness partner and foster a fan community.
- As a shareholder return measure, the company announced the introduction of a shareholder benefit program , offering vouchers usable on its D2C site twice a year (end of April and October; 1,500 JPY worth twice a year for 100 shares, 6,000 JPY worth twice a year for 300 shares).
6. Summary and Future Outlook
Inuneko Seikatsu's Q1 FY2027 earnings report marks a strong start, with the core subscription model demonstrating robust cash-generating power and achieving a high operating profit margin of 14.4%.
Key points to watch moving forward include:
- Whether the continuous net growth trend in subscription members is maintained.
- Optimization of new customer acquisition costs through the partnership with Saishunkan Pharmaceutical and the expansion of wholesale locations (aiming for 15,000 stores nationwide).
- The execution speed of veterinary clinic M&A , such as the Moriya Forest Animal Hospital, and the degree of cross-selling synergies created with the D2C business.
With a solid financial foundation and a clear growth strategy, the company's evolution from a mere pet food D2C company into a comprehensive "Pet Life Platform" remains a key area of interest.
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。