

TO Books FY2027 Q1 Earnings Deep Dive: Accelerated Media Mix for Core IPs, Record-High Progress, and Robust Shareholder Return Policy

StockClub
公開日時: Sep 14, 2026, 10:11 AM
Sentiment Analysis
TO Books Co., Ltd. FY2027 Q1 Earnings Deep Dive Report
TO Books Co., Ltd. (Securities Code: 500A) , listed on the Tokyo Stock Exchange Standard Market, is an IP production company that specializes in self-led, multi-faceted media mix strategies—spanning anime, stage plays, films, and merchandise—originating from its light novel and comic publishing business.
This report provides a comprehensive analysis based on the company's FY2027 Q1 earnings materials , covering performance highlights, segment and cost structure analysis, the upcoming media mix pipeline, the four pillars of its growth strategy, and the newly established shareholder return and benefit program.
1. FY2027 Q1 Earnings Highlights and Revenue Structure
In the first quarter, the company achieved significant year-on-year growth in both revenue and profit, driven by the media mix ripple effects from the broadcast of the third season of the flagship anime "Ascendance of a Bookworm" and the robust expansion of its core e-book business.
Financial Results and Progress
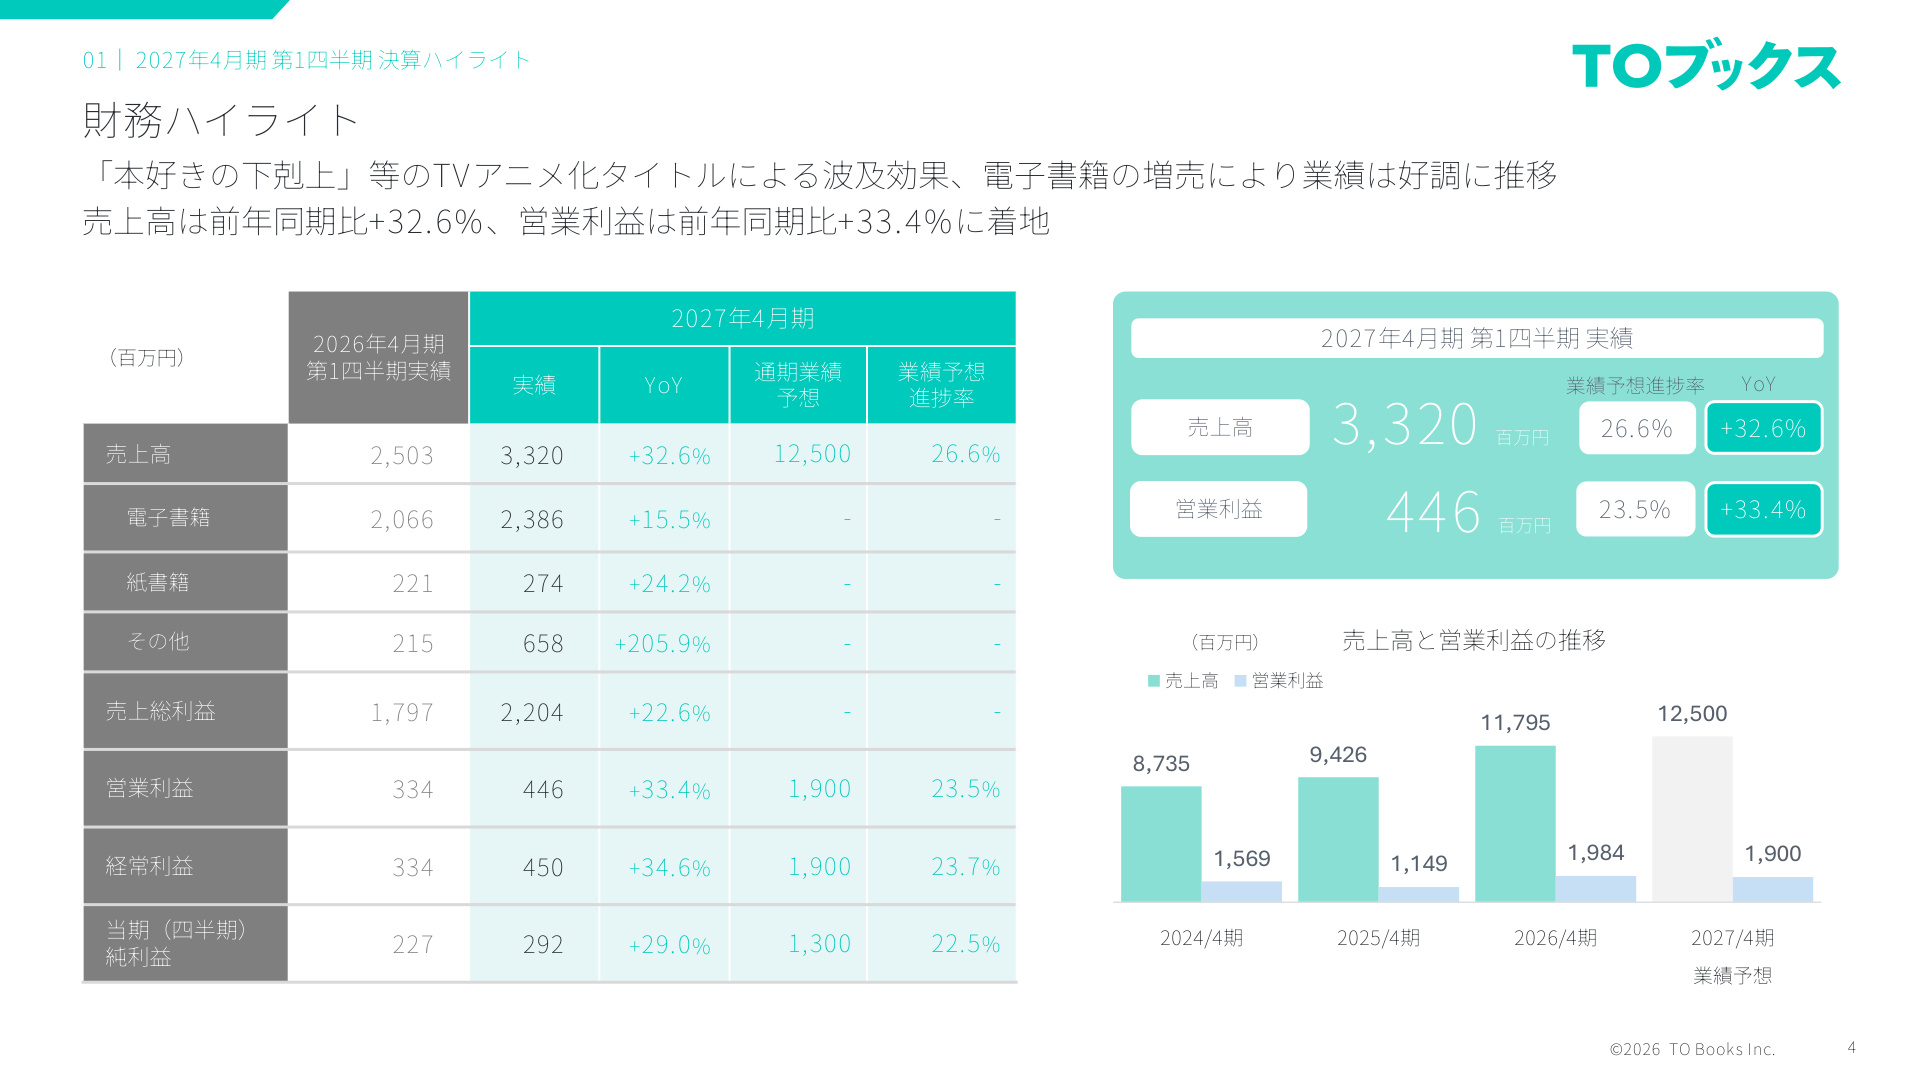
As shown in the earnings highlights above, key performance indicators are trending strongly:
- Net Sales : ¥3,320 million (+32.6% YoY)
- Gross Profit : ¥2,204 million (+22.6% YoY)
- Operating Profit : ¥446 million (+33.4% YoY)
- Ordinary Profit : ¥450 million (+34.6% YoY)
- Quarterly Net Income : ¥292 million (+29.0% YoY)
Progress against the full-year forecasts (Net Sales of ¥12,500 million, Operating Profit of ¥1,900 million) stands at 26.6% for sales and 23.5% for operating profit , marking a solid start for the first quarter.
Revenue Trends by Product Category
The breakdown of sales by category confirms the ongoing diversification of the company's business structure:
- E-books : ¥2,386 million (+15.5% YoY, 72% of total sales) Driven by the continuous release of new titles and successful promotional campaigns on e-book platforms, this segment maintains stable growth as the foundation of total revenue.
- Print Books : ¥274 million (+24.2% YoY, 8% of total sales) Benefited from increased bookstore exposure linked to anime broadcasts and new title releases, showing steady growth.
- Other (Anime, Live-action, Stage, Audio, Merchandise, Overseas Licensing, etc.) : ¥658 million (+205.9% YoY, 20% of total sales) Revenue from TV anime-related rights, merchandise sales, and tie-ups—led by "Ascendance of a Bookworm"—surged, recording more than triple the growth compared to the same period last year .
2. Cost Structure, Profitability, and KPI Analysis
Cost Structure and Profit Margin Maintenance
Cost of sales increased to ¥1,115 million (up from ¥705 million in the same period last year). This is primarily due to the amortization of investments in production committees following the expansion of anime-related sales, increased royalty payments to creators, and upfront investments in content production. However, thanks to the expansion of high-margin e-books and licensing revenue, the operating profit margin remains at 13.4% , maintaining the double-digit profitability seen in the previous year.
Key Performance Indicators (KPIs)
KPIs related to IP creation and development, the source of the company's earnings, are on a steady upward trajectory:
- Editorial Staff : Increased from 57 at the end of the previous fiscal year to 64 (a leading indicator for increasing the number of major IPs).
- Major IPs (Titles with annual e-book sales of ¥10 million or more) : 88 IPs (compared to 91 at the end of the previous fiscal year; maintaining a high level on a full-year basis).
- Revenue per Major IP (IP Value) : ¥37 million as of Q1 (equivalent to ¥148.3 million on an annualized basis, outpacing the previous year's ¥133.6 million).
By standardizing the training process and accelerating the onboarding of editors, the company has built a system where the expansion of creative staff directly translates into a robust IP creation pipeline.
3. Media Mix Development and Pipeline
The company's greatest strength lies in its media mix execution capability , which allows it to develop its own IPs into anime, films, stage plays, and merchandise.
Accelerated Anime Adaptations and Revenue Drivers
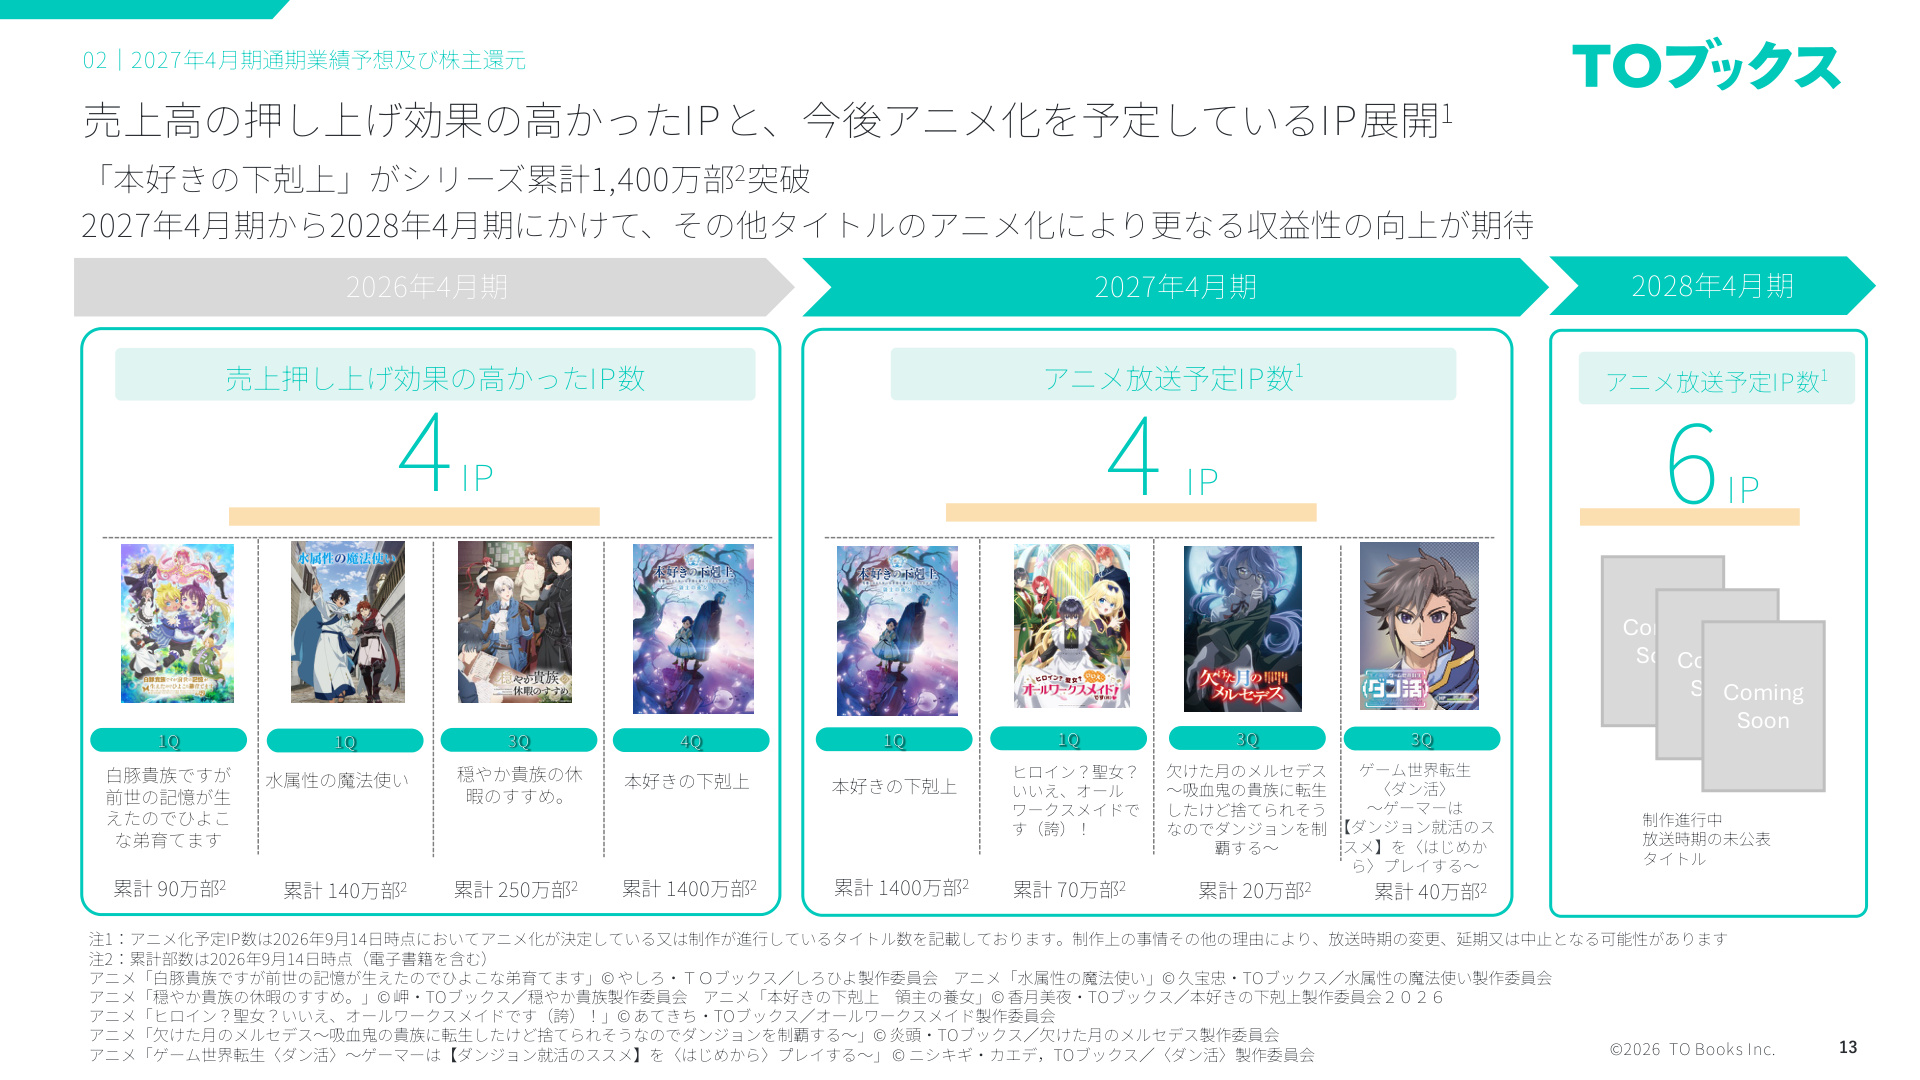
As shown in the slide above, the number of anime adaptations—which have a significant impact on boosting sales—is planned to increase annually:
- FY2026 (Previous Year Results) : 4 IPs ("Ascendance of a Bookworm" 14M copies, "The Magic User: Reincarnated in Another World" 1.4M copies, "The Gentle Noble's Vacation Recommendation" 2.5M copies, "I'm a White Pig Noble, but Since I Have Memories of My Previous Life, I'll Raise My Chick Brother" 0.9M copies)
- FY2027 (Current Year Plan) : 4 IPs
- Q1: "Ascendance of a Bookworm," "Heroine? Saint? No, I'm an All-Works Maid (Proud)!"
- Q3 (Scheduled for Jan 2027): "Mercedes of the Chipped Moon," "Dungeon Activity (Dankatsu)"
- FY2028 (Next Year Plan) : 6 IPs (Titles currently in production; broadcast dates TBD)
Anime adaptations serve not only as visual content but as a starting point for "awareness acquisition," leading to "increased sales of backlist books/e-books," "merchandise development," and "stage/reading plays/live-action films," creating a cycle that dramatically increases the Lifetime Value (LTV) per IP.
4. "Four Growth Strategies" for Mid-to-Long-Term Expansion
TO Books has outlined the following four strategic pillars to achieve sustainable growth:
- Deepening Media Mix Strategy (Maximizing IP Value and Evergreen Status) By moving away from reliance on a single medium and integrating anime, stage plays, films, audio CDs, and real-world events (such as TSUTAYA POP UP and regular events at Shibuya Sakura Stage), the company aims to deepen and extend the lifespan (evergreening) of its IP fan base.
- Stable IP Creation (Talent Acquisition and E-bookstore Alliances) Leveraging a favorable hiring environment (a buyer's market with a 0.27x job-to-applicant ratio for new graduates), the company is aggressively hiring creative talent. It is also shortening training periods and utilizing joint labels and alliances with external e-bookstores to enhance creation speed and exposure.
- Leveraging Third-Party IPs (Levers for "Delivery" Capabilities) The company provides its planning, sound production, distribution, and merchandise production capabilities—honed through its own IPs—to promising third-party IPs (games, characters, artists, etc.). By participating in joint management and production investments, it expands revenue opportunities beyond publishing.
- Accelerating Overseas Expansion (Penetration into Global Markets) The company is scaling its global distribution network through the acquisition of shares in the Thai publisher "TAMA STUDIO," providing titles to "MangaPlaza" in North America, and establishing a system to release over 100 English-translated print and e-book titles annually through collaborations with local distributors and publishers.
5. Shareholder Return Policy and New Shareholder Benefit Program
The company views active and stable shareholder returns, alongside mid-to-long-term corporate value enhancement, as a key management priority.
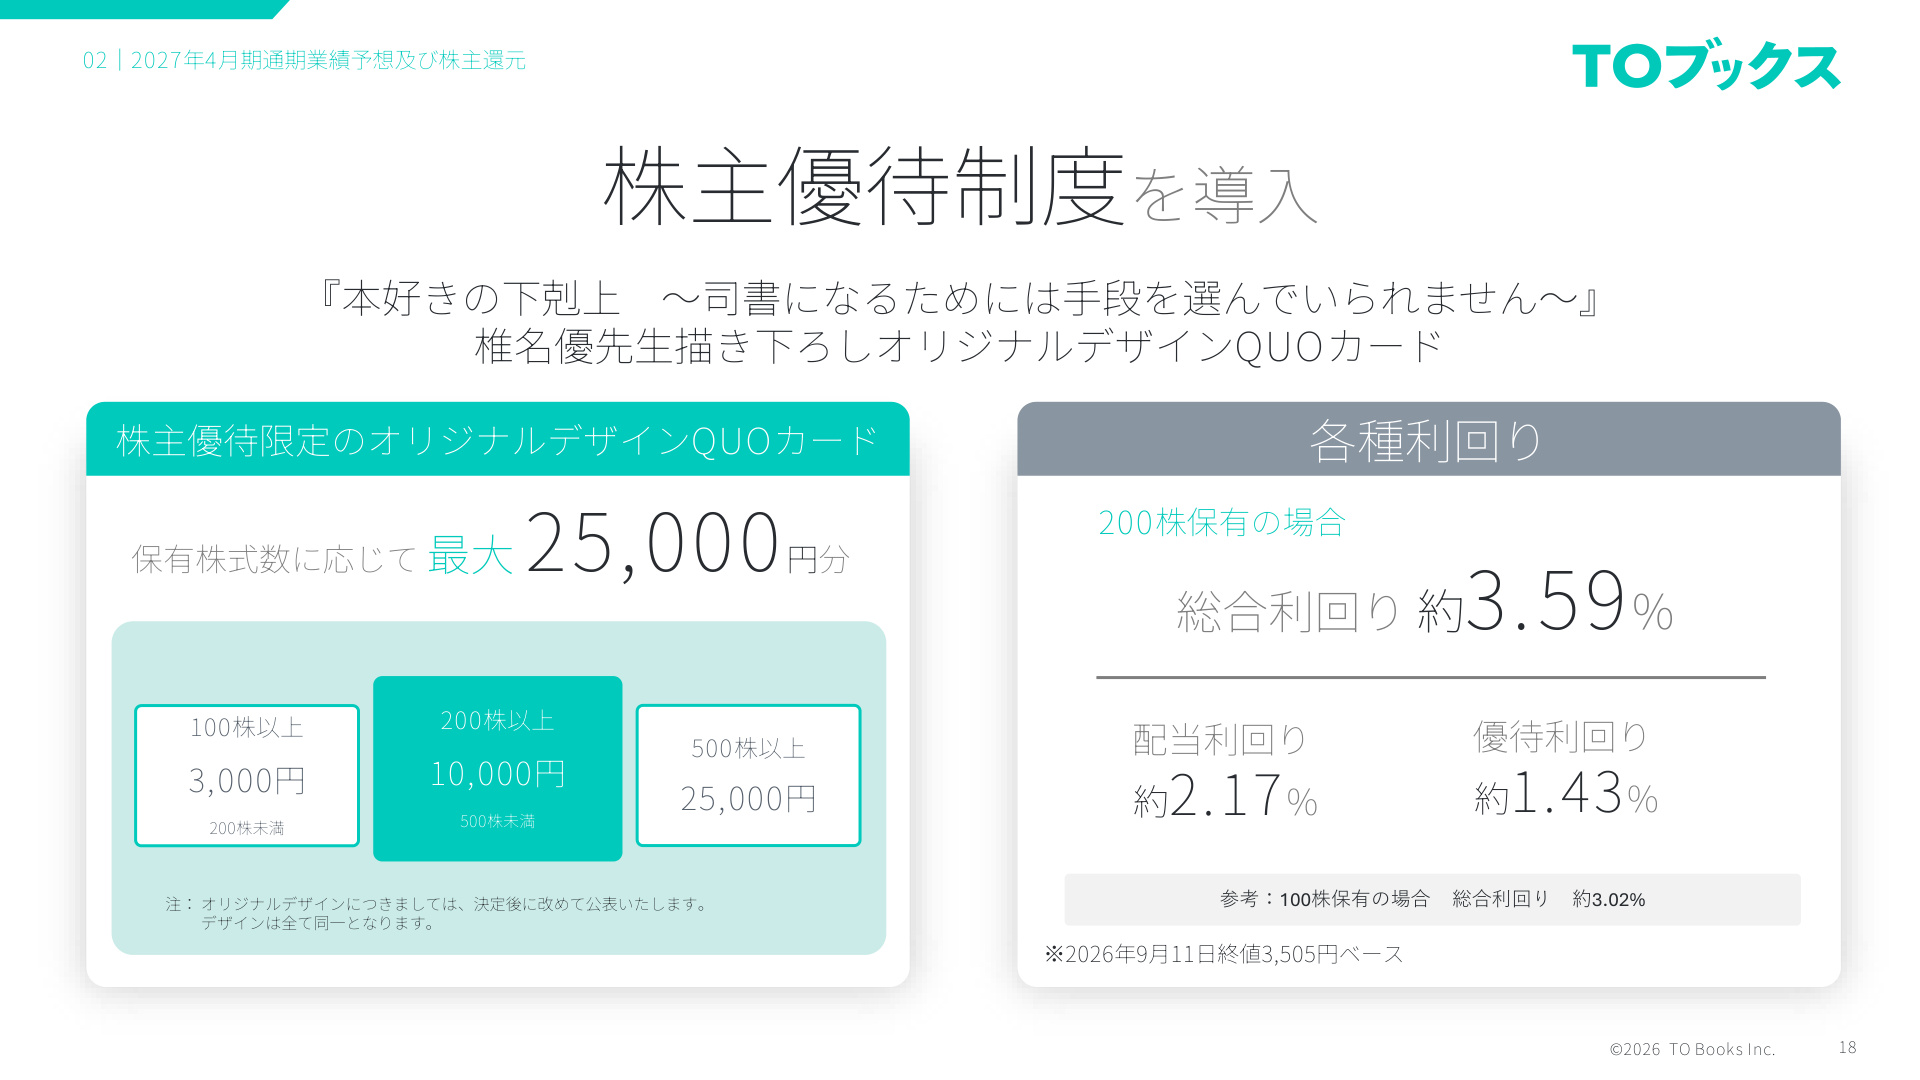
Dividend Policy and Forecast
- FY2027 Annual Dividend (Forecast) : ¥76 per share (same as the previous year's ¥76)
- Dividend Payout Ratio : 20.6% (increased from 18.0% in the previous year, with a policy to further increase the payout ratio over the mid-to-long term)
Introduction of Original Shareholder Benefit Program
To expand the individual investor base and encourage long-term holding, a new shareholder benefit program has been established, offering original design QUO cards illustrated by You Shiina for the popular IP "Ascendance of a Bookworm."
- 100 to under 200 shares : ¥3,000 value
- 200 to under 500 shares : ¥10,000 value
- 500 shares or more : ¥25,000 value
According to the calculations in the materials (based on the closing price of ¥3,505 on September 11, 2026), the dividend yield for holding 200 shares is approximately 2.17%, the benefit yield is approximately 1.43%, and the total yield is approximately 3.59% (approx. 3.02% for 100 shares), creating a highly attractive return structure for both fans and income-oriented investors.
6. Conclusion: Sustainable Growth through Strong IP Creation and Multi-layered Media Mix
TO Books' FY2027 Q1 earnings demonstrate powerful results, with "Other Sales" exceeding three times the previous year's level due to the success of its flagship IP media mix.
- High-Level Performance Progress : A strong start against the full-year plan with ¥3,320 million in sales and ¥446 million in operating profit.
- Solid Pipeline : With 4 anime projects scheduled for FY2027 and 6 for FY2028, the wave of media mix developments is visible for the mid-to-long term.
- Strengthened Business Foundation and Returns : Expansion of the editorial system, promotion of overseas expansion (Thailand/North America), an increase in the dividend payout ratio to 20.6%, and the establishment of a new shareholder benefit program worth up to ¥25,000.
With its unique production system that handles everything from in-house IP creation to visual adaptation, merchandising, and overseas expansion, this earnings report confirms the steady progress of the company's mid-to-long-term growth story.
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。