

AXXZIA FY2026 Earnings Deep Dive: Rebounding from Losses Driven by Soaring Chinese Ad Costs and Strategic Regional/Channel Diversification

StockClub
公開日時: Sep 14, 2026, 10:10 AM
Sentiment Analysis
Introduction: Overview of FY2026 Financial Results
AXXZIA (Ticker: 4936) reported its full-year financial results for the fiscal year ending July 2026. While net sales remained largely flat at ¥13.466 billion (down 0.1% YoY) , the company faced a challenging bottom line, reporting an operating loss of ¥176 million (compared to an operating profit of ¥513 million in the previous year) and a net loss attributable to owners of the parent of ¥464 million (compared to a net profit of ¥320 million in the previous year).
Profitability was pressured by surging advertising expenses in the core Chinese e-commerce market and increased personnel costs associated with strengthening the organizational structure for future growth. Additionally, the company recorded an impairment loss on fixed assets of ¥410 million, reflecting current operating losses and future business plans, which further impacted the net result.
However, structural reforms are progressing, characterized by "reducing dependence on China and diversifying the regional portfolio" and the "growth of emerging brands." For the upcoming fiscal year ending July 2027, the company projects a return to top-line growth with sales of ¥14.8 billion (up 9.9% YoY) and a significant narrowing of the operating loss to ¥50 million . This report provides a detailed analysis of performance drivers, sales trends, and the turnaround strategy.
Performance Highlights and Cost Structure Analysis
1. Sales and Profitability
Consolidated net sales for FY2026 reached ¥13.466 billion, maintaining levels consistent with initial plans and the previous year's performance. However, a significant increase in SG&A expenses weighed down operating profit.
2. Drivers of SG&A Expenses and Cost of Sales Trends
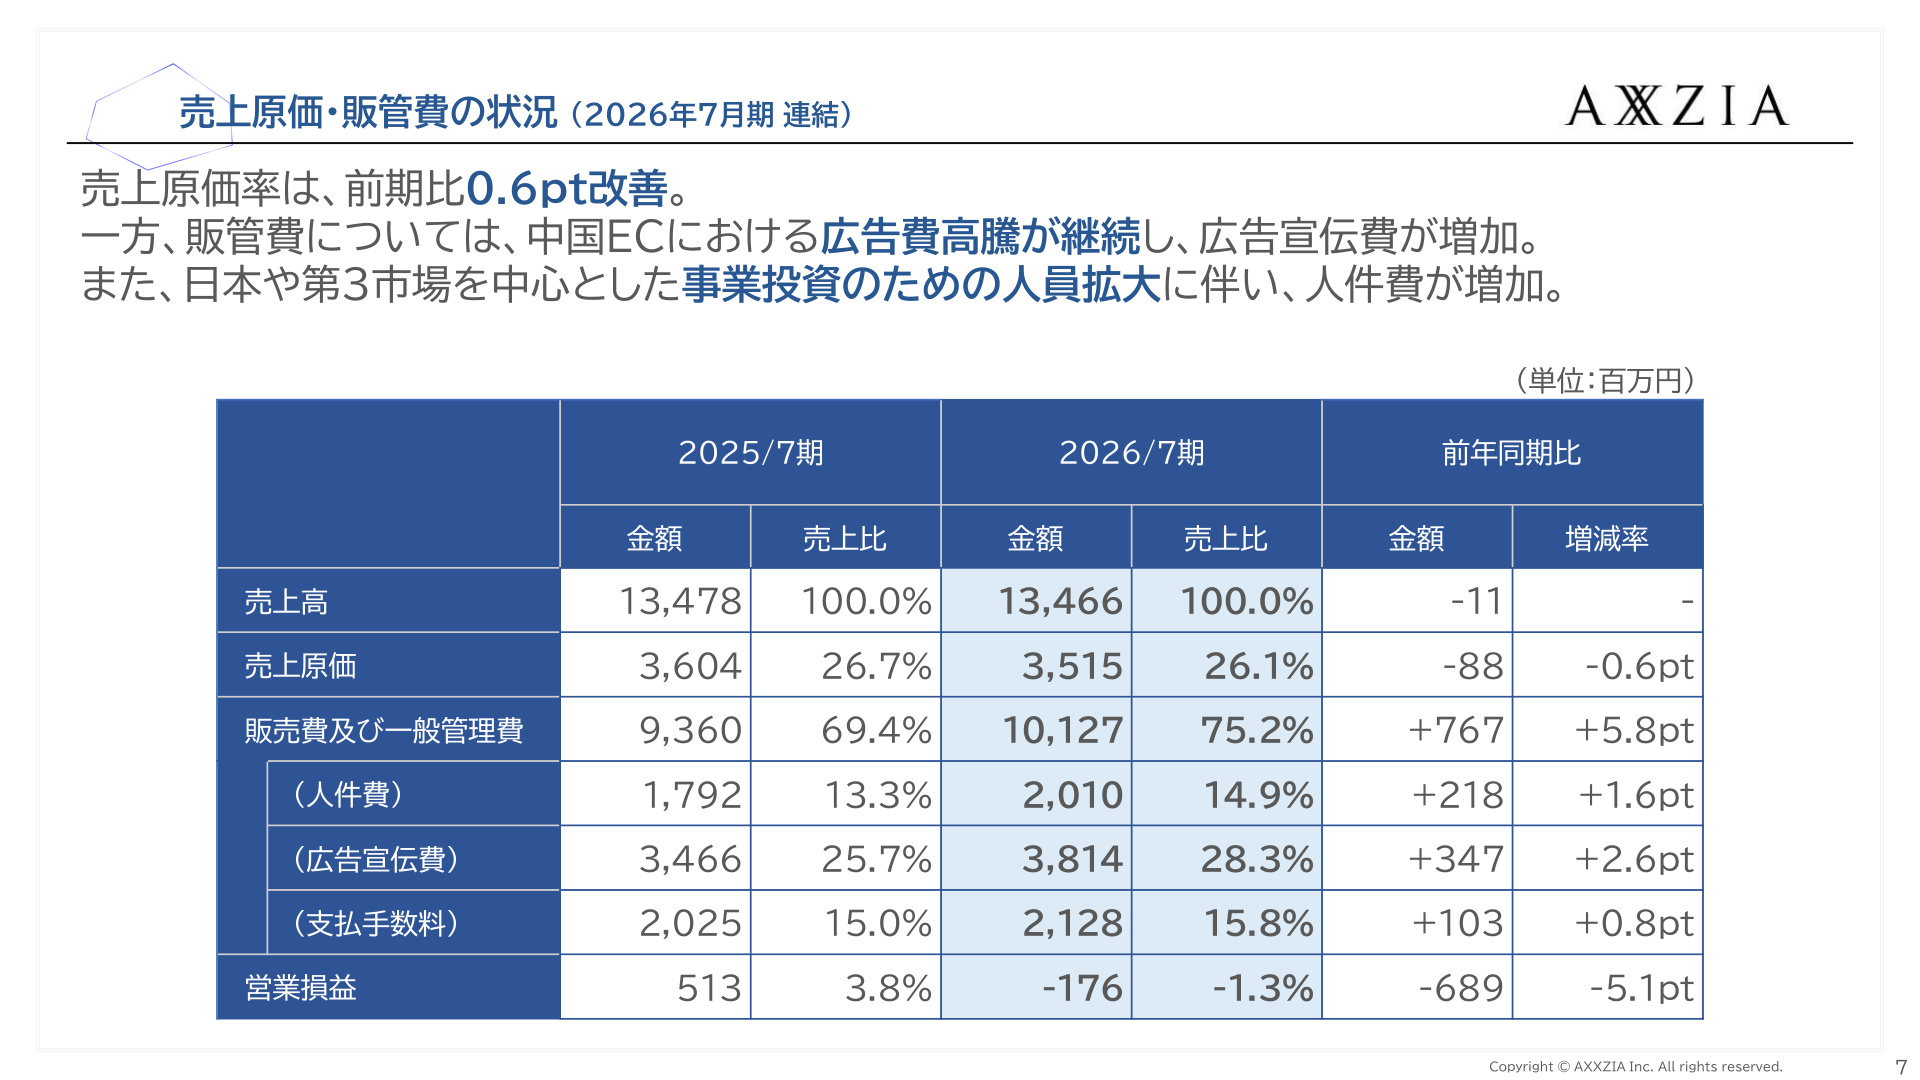 The slide above provides critical data on the breakdown of cost of sales and SG&A expenses.
Notably, the cost of sales ratio improved to 26.1% (a 0.6pt improvement YoY) , indicating that fundamental product profitability is being maintained or improved through manufacturing cost control and the sale of high-value-added products.
Conversely, the SG&A ratio deteriorated significantly to 75.2% (up 5.8pt YoY) . The breakdown is as follows:
- Advertising Expenses : ¥3.814 billion (28.3% of sales, +¥347 million / +2.6pt YoY ). Customer Acquisition Costs (CAC) remained high due to intensifying competition on Chinese e-commerce platforms.
- Personnel Expenses : ¥2.01 billion (14.9% of sales, +¥218 million / +1.6pt YoY ). This reflects upfront investments in expanding the organization to support development in Japan and the "Third Market," primarily Southeast Asia.
- Commission Fees : ¥2.128 billion (15.8% of sales, +¥103 million / +0.8pt YoY ).
3. Maintaining Financial Soundness
Despite the ¥410 million impairment loss and annual dividend payments (totaling ¥228 million), the company maintains a strong financial position with cash and deposits of ¥3.996 billion and an equity ratio of 79.7% . Interest-bearing debt has been reduced to ¥654 million (a decrease of ¥205 million from the end of the previous fiscal year), securing a solid financial foundation to drive business structural reforms.
Progress by Region and Channel
4. Diversification of Regional Portfolio
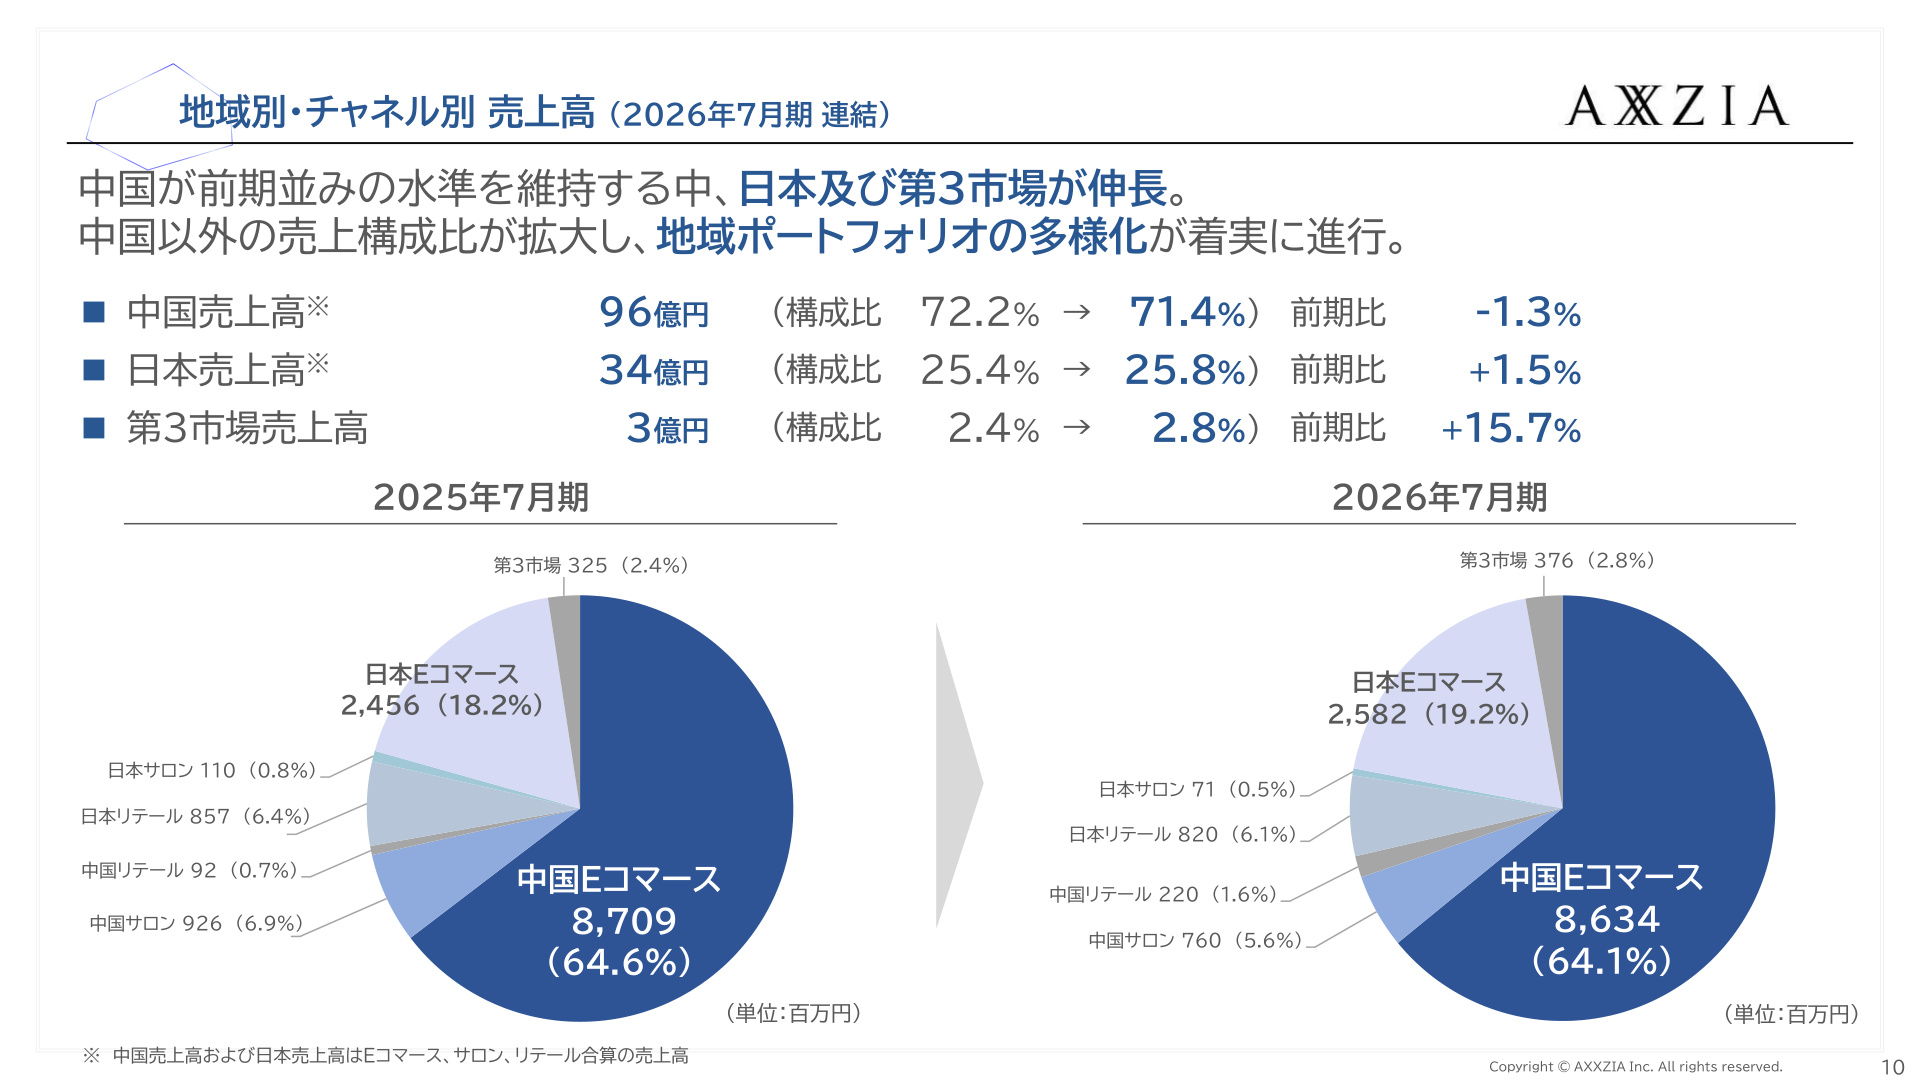 While AXXZIA has long relied on the Chinese market for the majority of its sales, efforts to diversify its regional footprint are beginning to yield steady results.
- China Sales : ¥9.615 billion (down 1.3% YoY, 71.4% of total sales). The composition ratio decreased from 72.2% in the previous year.
- Japan Sales : ¥3.474 billion (up 1.5% YoY, 25.8% of total sales). Despite fluctuations in inbound demand, sales are growing steadily, driven by domestic e-commerce.
- Third Market Sales : ¥376 million ( up 15.7% YoY , 2.8% of total sales).
5. Channel Composition in the Chinese E-commerce Market
In China, the short-video platform Douyin (TikTok China) remains the primary sales pillar at ¥4.651 billion. Furthermore, traditional e-commerce channels have seen significant growth: Tmall reached ¥2.029 billion (up from ¥1.5 billion), and JD.com expanded rapidly to ¥228 million (up from ¥92 million), demonstrating progress in channel diversification beyond specific platforms.
6. Rapid Growth in Southeast Asia
Within the "Third Market," Southeast Asia is showing particularly remarkable growth. Driven by strengthened influencer (KOL) marketing, particularly in Malaysia, sales in Southeast Asia surged by 381.4% YoY to ¥202 million .
Brand Overview and Product Development
7. Stability of Core Brands and Expansion of Emerging Categories
- AGTHEORY : Sales of ¥6.931 billion. The core inner-care product "AG Drink" accounted for ¥5.93 billion, serving as a stable pillar supporting approximately half (49.7%) of total company sales. In August 2026, the company launched "AG Tablet," a highly portable supplement, to expand the lineup.
- AXXZIA : Sales of ¥3.109 billion. The "Essence Sheet" eye-care series generated ¥2.68 billion, with cumulative sales surpassing 7 million units .
- Emerging Categories (Venus Recipe / RevWell) : Sales of ¥1.778 billion ( up 13.5% YoY ). Mid-range inner-care products like "PQ Drink Plus" performed well, with the sales composition ratio increasing by 1.9pt from 13.0% to 14.9% , solidifying its position as a third pillar.
FY2027 Earnings Outlook and Growth Strategy
8. FY2027 Consolidated Earnings Plan
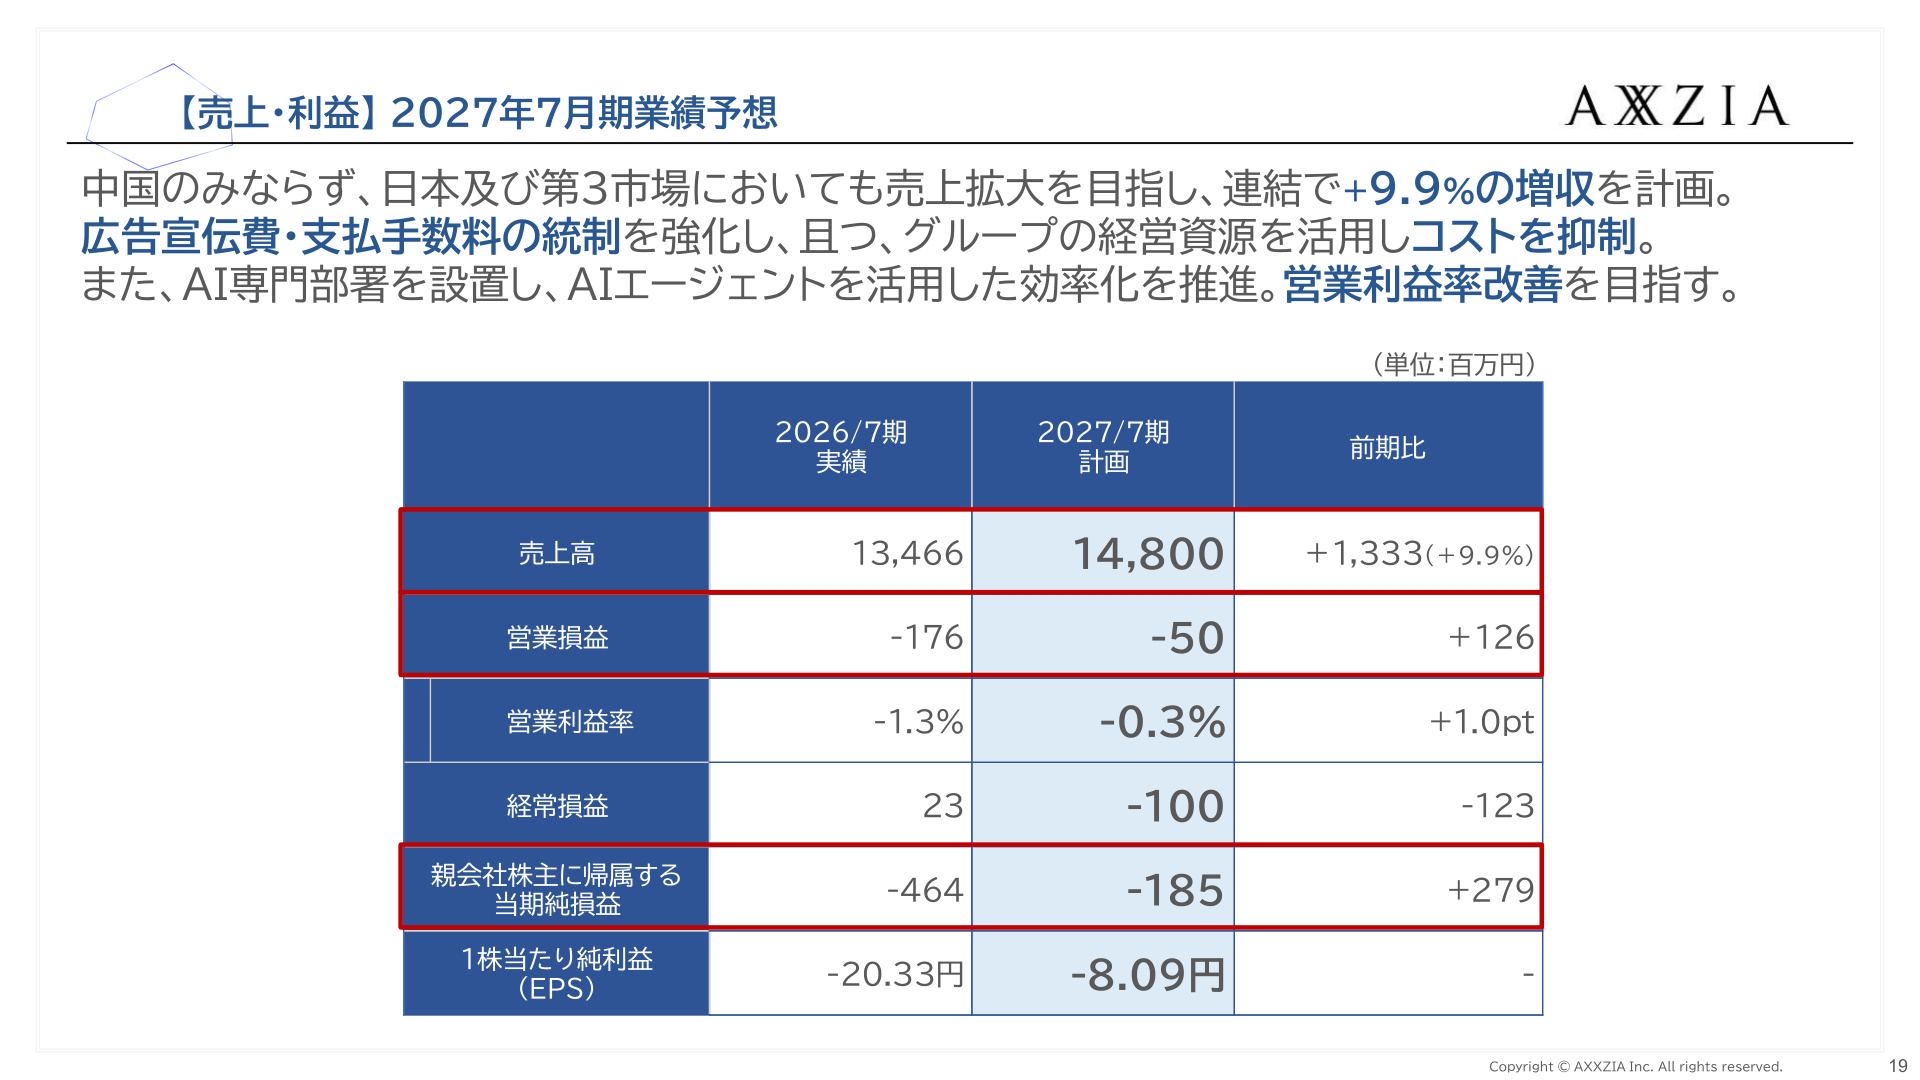 The consolidated plan for the fiscal year ending July 2027 targets net sales of ¥14.8 billion (up 9.9% YoY) , an operating loss of -¥50 million (an improvement of ¥126 million YoY) , and a net loss attributable to owners of the parent of -¥185 million (an improvement of ¥279 million YoY) .
By region, the company expects growth across all areas: China at ¥10.5 billion (up 9.2% YoY) , Japan at ¥3.5 billion (effectively up 10.0% YoY) , and the Third Market at ¥799 million (up 112.3% YoY) .
9. Key Measures for Profitability Improvement and Growth
To narrow losses and achieve future profitability, the company will implement the following measures:
- Cost Control and AI Utilization : Strengthen control over soaring advertising and commission expenses. Establish an internal AI department to drive operational efficiency through the use of AI agents .
- Rigorous Profit Management in China : Tighten profitability management by platform, with a focus on Douyin. Enhance ROI on promotions through the appointment of celebrity ambassadors and the launch of collaboration products directed by Mika Ninagawa.
- Focus on TikTok Shop in Japan : Leverage live-commerce expertise gained in China to expand into Japan's TikTok Shop, building an end-to-end model from awareness to purchase. Promote wholesale expansion of the low-to-mid-range brand "Lisblanc."
- Strengthening Southeast Asian Operations : Established a local subsidiary in Malaysia in August 2026. Shorten lead times through local inventory and accelerate sales via Shopee, Lazada, TikTok Shop, and wholesale distribution to drugstores.
10. Shareholder Return Policy
Despite the projected operating loss for FY2027, the company plans to maintain an annual dividend of ¥10 (¥5 interim, ¥5 year-end) , prioritizing shareholder returns backed by its strong financial foundation (79.7% equity ratio). The shareholder benefit program , including incentives for long-term holding, will also be maintained.
Conclusion
For AXXZIA, the fiscal year ending July 2026 was a "transition period" where profitability was impacted by changes in the Chinese e-commerce environment and upfront investments. However, signs of structural reform are emerging, including improved cost of sales ratios, business expansion in Japan and Southeast Asia, and the successful launch of emerging brands. The focus for FY2027 will be on whether the company can successfully balance top-line growth through regional and channel diversification with the correction of its cost structure through AI utilization and advertising expense control.
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。