

[North Sand] Q2 FY2027 Earnings Report: Sustained High Growth in Revenue and Profit, Upward Revision of Full-Year Forecast, and Application for Prime Market Listing

StockClub
公開日時: Sep 14, 2026, 10:09 AM
Sentiment Analysis
Overview: Achieving Both High Top-Line Growth and Improved Profit Margins, Leading to Upward Revision of Full-Year Forecast
North Sand, Inc. (Securities Code: 446A), a provider of comprehensive consulting services, has announced its financial results for the second quarter (cumulative) of the fiscal year ending January 2027. Driven by the rapid expansion of its consultant headcount, the maintenance of high utilization rates, and an increase in average project unit prices, the company achieved exceptional growth, reporting revenue of 18.445 billion yen (+60.2% YoY) and operating profit of 3.766 billion yen (+68.7% YoY) .
Backed by strong first-half performance and a robust pipeline of recruitment and projects, the company has upwardly revised its full-year earnings forecast . Concurrently, it announced an increase in the annual dividend forecast (from 33 yen to 35 yen per share) and the submission of an application to transition its listing to the Tokyo Stock Exchange Prime Market .
1. Q2 FY2027 Earnings Highlights and Key KPI Trends
During the first half of the fiscal year, all key performance indicators (KPIs) exceeded planned targets, resulting in significant year-on-year growth in both revenue and profit.
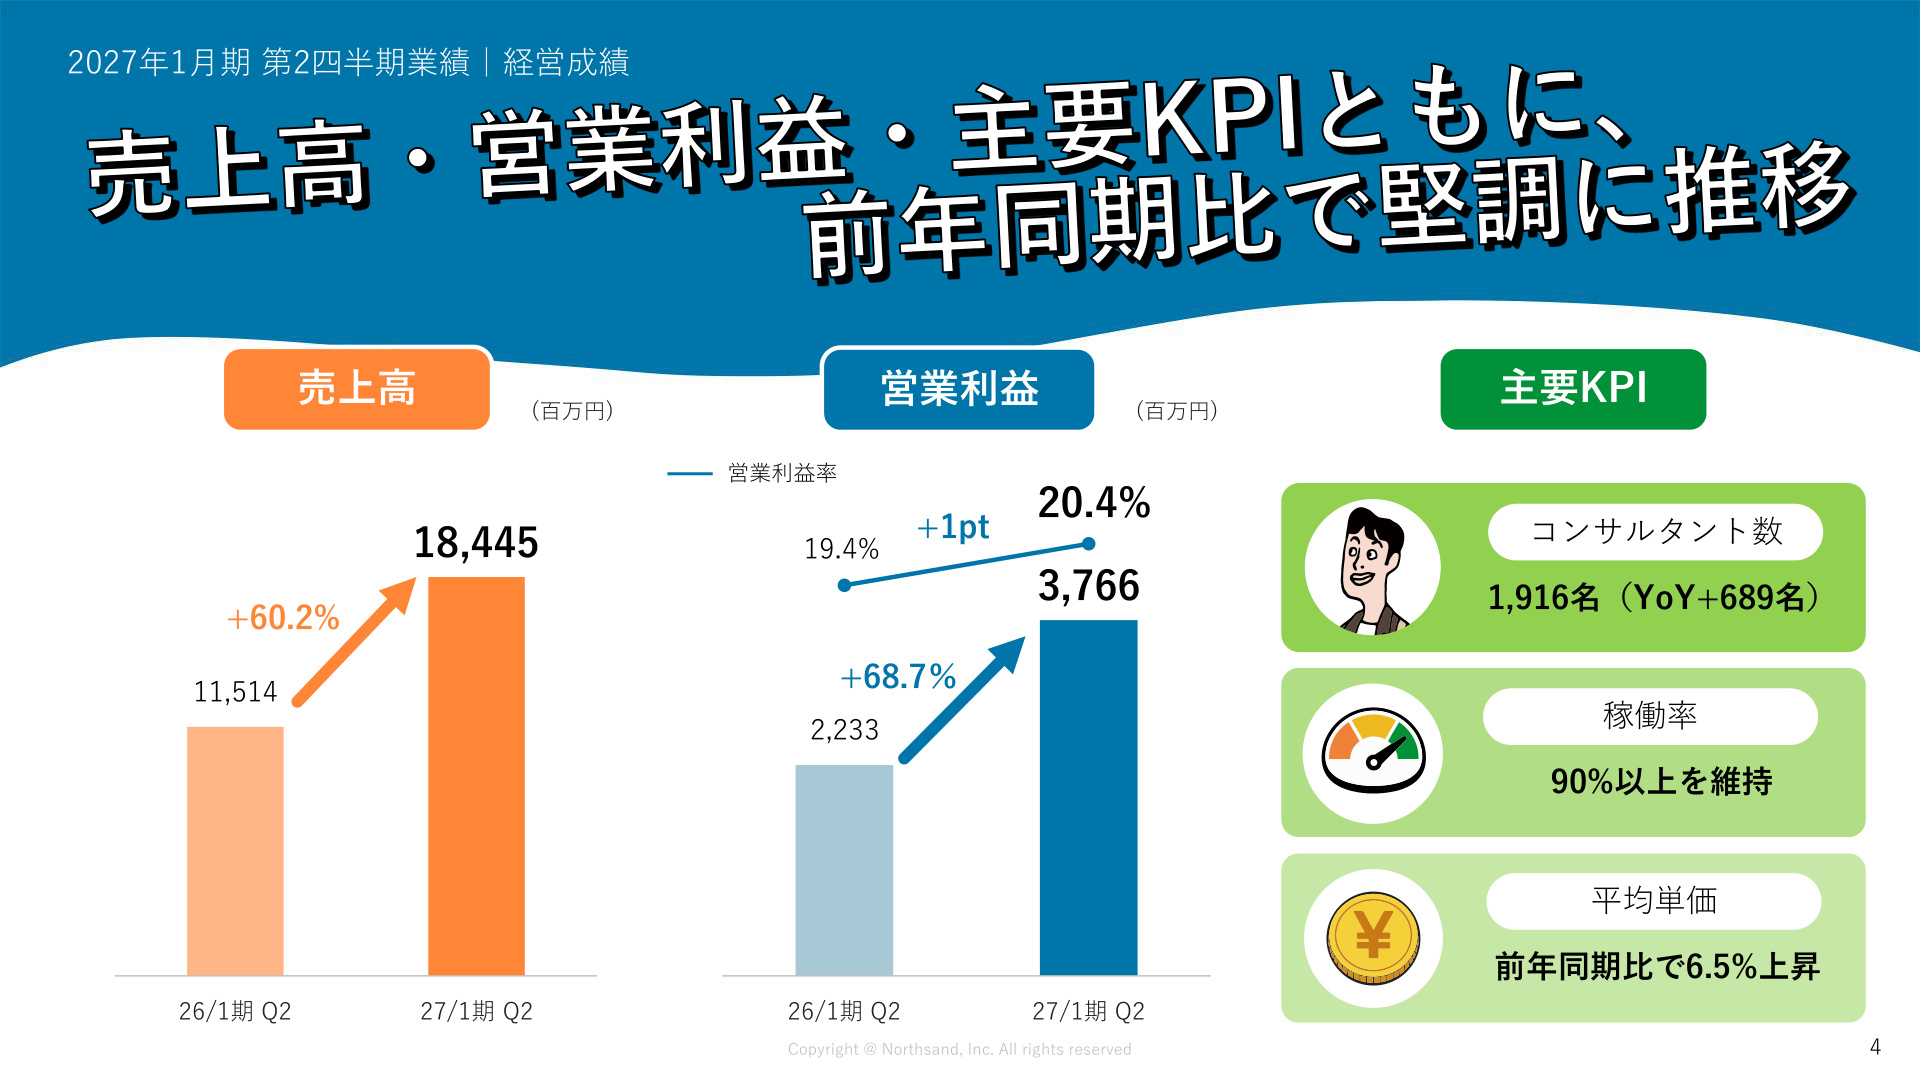
As shown in the chart above, the company's three primary growth drivers—consultant headcount, utilization rate, and average unit price—are all expanding steadily.
- Revenue : 18.445 billion yen ( +60.2% YoY)
- Operating Profit : 3.766 billion yen ( +68.7% YoY)
- Operating Profit Margin : 20.4% ( +1.0pt YoY)
- Consultant Headcount : 1,916 (a significant increase of +689 YoY)
- Utilization Rate : Maintained at a high level of over 90%
- Average Unit Price : Increased by +6.5% YoY
In the consulting industry, rapid scaling often leads to temporary dips in utilization or unit prices. However, North Sand has successfully achieved a net increase of 689 personnel while simultaneously maintaining a "high utilization rate of over 90%" and a "6.5% increase in unit price," demonstrating the strength of its operational structure.
2. Cost Structure and Profitability Analysis (Trends in Gross and SG&A Ratios)
The company's profit structure is characterized by a stable gross margin and a steady reduction in the SG&A ratio as the business scales.
- Cost of Sales and Gross Margin : The cumulative gross margin for the first half was 48.3% (on par with the previous year), remaining in line with plans. Despite rising labor costs, the company has secured high-value margins through increased unit prices and high utilization.
- SG&A Expenses and Ratio : The cumulative SG&A ratio for the first half was 27.9% , an improvement of 1.0pt from 28.9% in the same period last year. While continuing to invest aggressively in recruitment, training, and office costs, the company is benefiting from economies of scale. The SG&A ratio has steadily declined from 29.3% in Q1 to 26.6% in Q2 alone .
As a result, the cumulative operating profit margin for the first half reached 20.4% , marking a 1.0pt improvement in profitability compared to the previous year.
3. Upward Revision of Full-Year Forecast and Dividend Increase
Following the strong performance in the first half, the company has announced an upward revision to its full-year consolidated earnings and dividend forecasts.
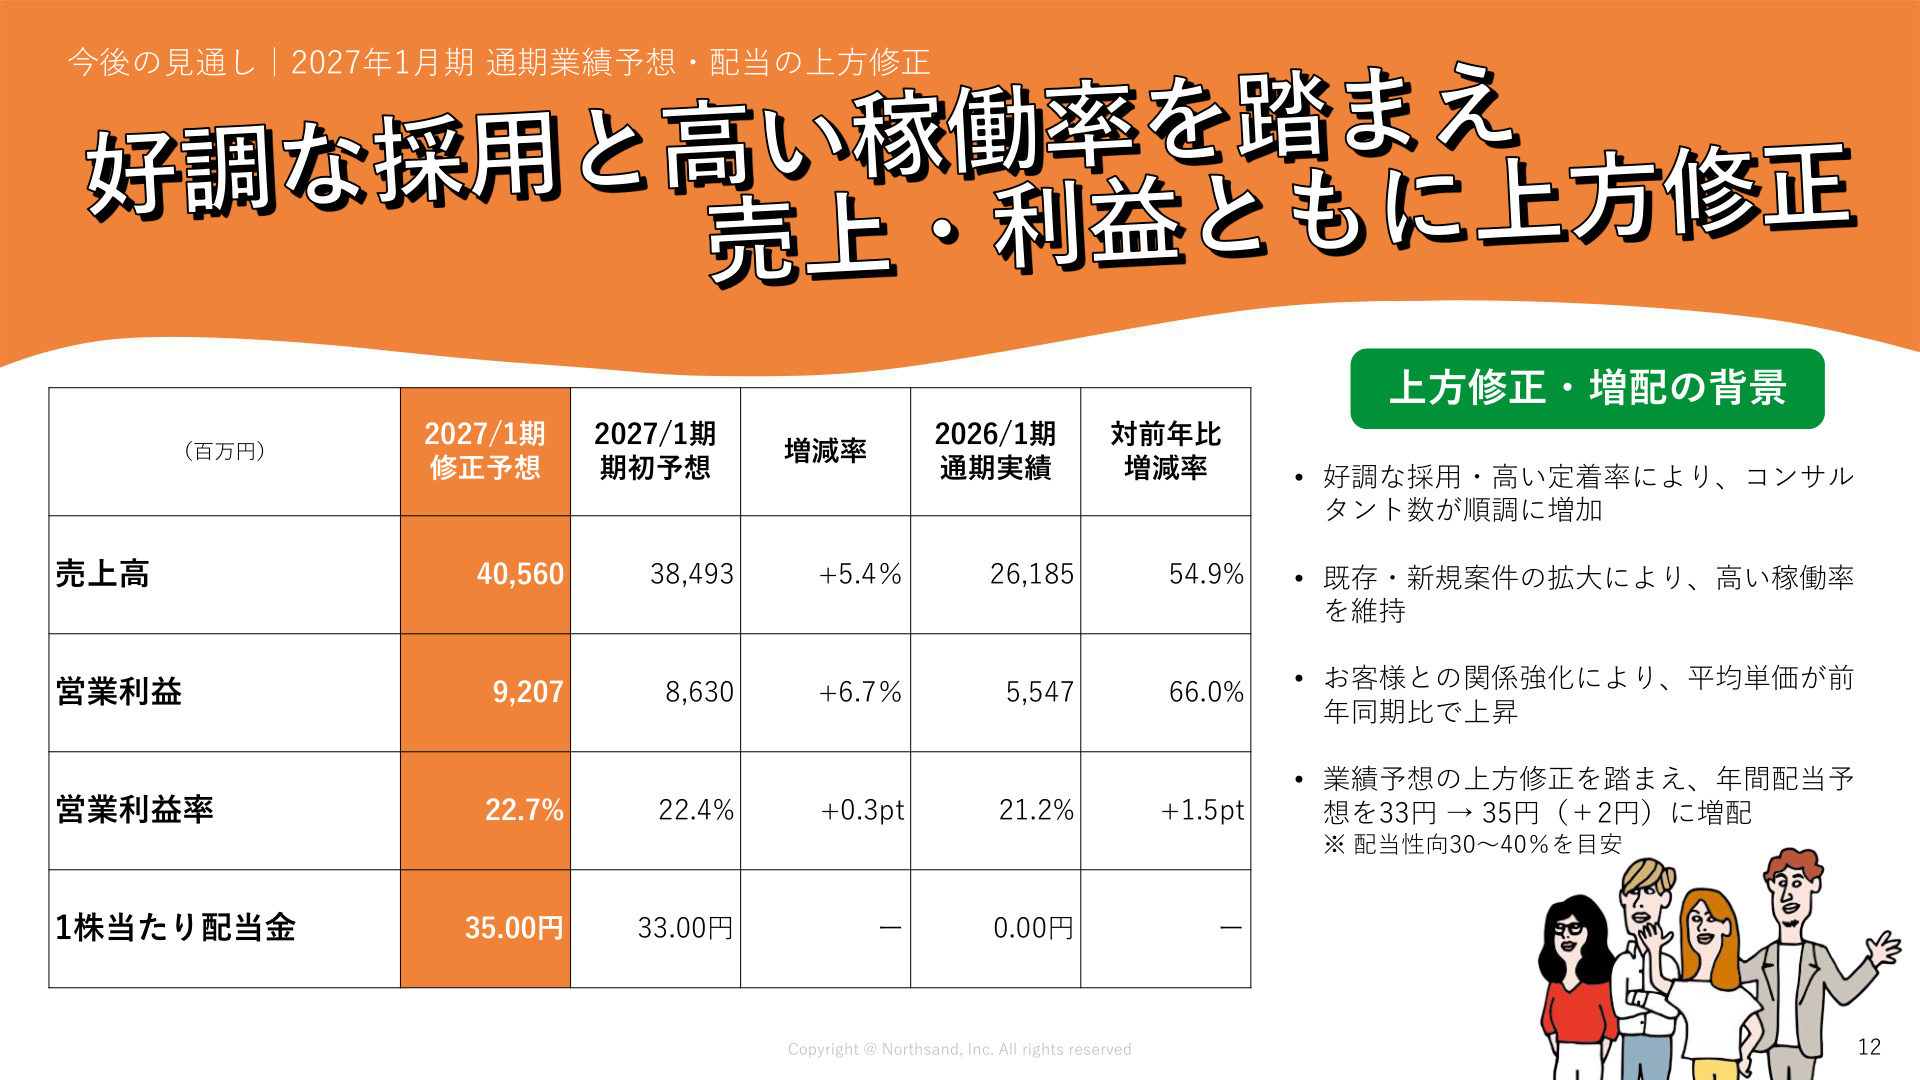
The revision is supported by a steady net increase in consultants backed by strong recruitment capabilities and low turnover, the maintenance of high utilization rates due to robust demand for DX and business consulting from both existing and new clients, and an increase in average unit prices resulting from enhanced value delivery.
Details of Full-Year Forecast Revision
- Revenue : 40.56 billion yen ( +5.4% vs. initial forecast, +54.9% YoY)
- Operating Profit : 9.207 billion yen ( +6.7% vs. initial forecast, +66.0% YoY)
- Operating Profit Margin : 22.7% ( +0.3pt vs. initial forecast, +1.5pt YoY)
- Annual Dividend : 35.00 yen per share (an increase of 2.00 yen from the initial forecast of 33.00 yen; no dividend was paid in the previous fiscal year)
The company maintains a policy of stable and continuous shareholder returns with a target dividend payout ratio of 30–40% , and has raised the dividend amount in line with the upward revision of its earnings.
4. Sources of Growth: Recruitment Power, Low Turnover, and the Unique "Fan-Building Cycle"
North Sand demonstrates unique strengths in "talent acquisition" and "talent retention," which are often the biggest constraints to growth in the consulting business.
- Broad Candidate Pool Including Non-Consultants : The company targets those without prior consulting experience, with approximately 88.5% of applicants coming from outside the industry. With 21,891 annual applicants, the company maintains a rigorous selection process with a 35.5x acceptance ratio .
- Culture-Fit Recruitment Focusing on Human Qualities : Rather than focusing solely on skills and knowledge, the company prioritizes "human qualities" such as charm, honesty, and tenacity, as well as cultural fit.
- Industry-Leading Retention Rate : The turnover rate for the fiscal year ended January 2026 was 7.6% , an exceptionally low level for the consulting industry.
- Establishment of a Fan-Building Cycle : The company has built an ecosystem that turns "recruitment agents and candidates," "employees," and "clients" into fans, creating a virtuous cycle that promotes referral hiring, maintains low turnover, and drives high utilization and unit prices.
5. Financial Foundation and Focus on Capital Efficiency (ROE and Cost of Capital)
As the business expands, both financial health and capital efficiency are being maintained at high levels.
- Strong Equity Ratio : With total assets of 24.376 billion yen and net assets of 19.238 billion yen, the company boasts a robust financial position with an equity ratio of 78.9% (+3.6pt from the end of the previous fiscal year).
- ROE Target Significantly Exceeding Cost of Capital : Estimating its own cost of capital (CAPM basis) at around 9% and the market's expected cost of capital at 10–11% , the company has set a target ROE of 30% or higher for the fiscal year ending January 2027, aiming to achieve capital profitability that significantly exceeds the cost of capital.
- Capital Allocation Policy : The company has clarified its policy to optimally allocate operating cash flow and cash on hand toward "steady-state working capital (retaining approximately 2 months of monthly sales)," "shareholder returns (payout ratio of 30–40%)," and "agile funds (securing approximately 6 months of personnel costs for human capital investment)."
6. Mid-to-Long-Term Growth Strategy and Application for TSE Prime Market Listing
The company is not merely focused on short-term high growth but has presented a clear mid-to-long-term roadmap.
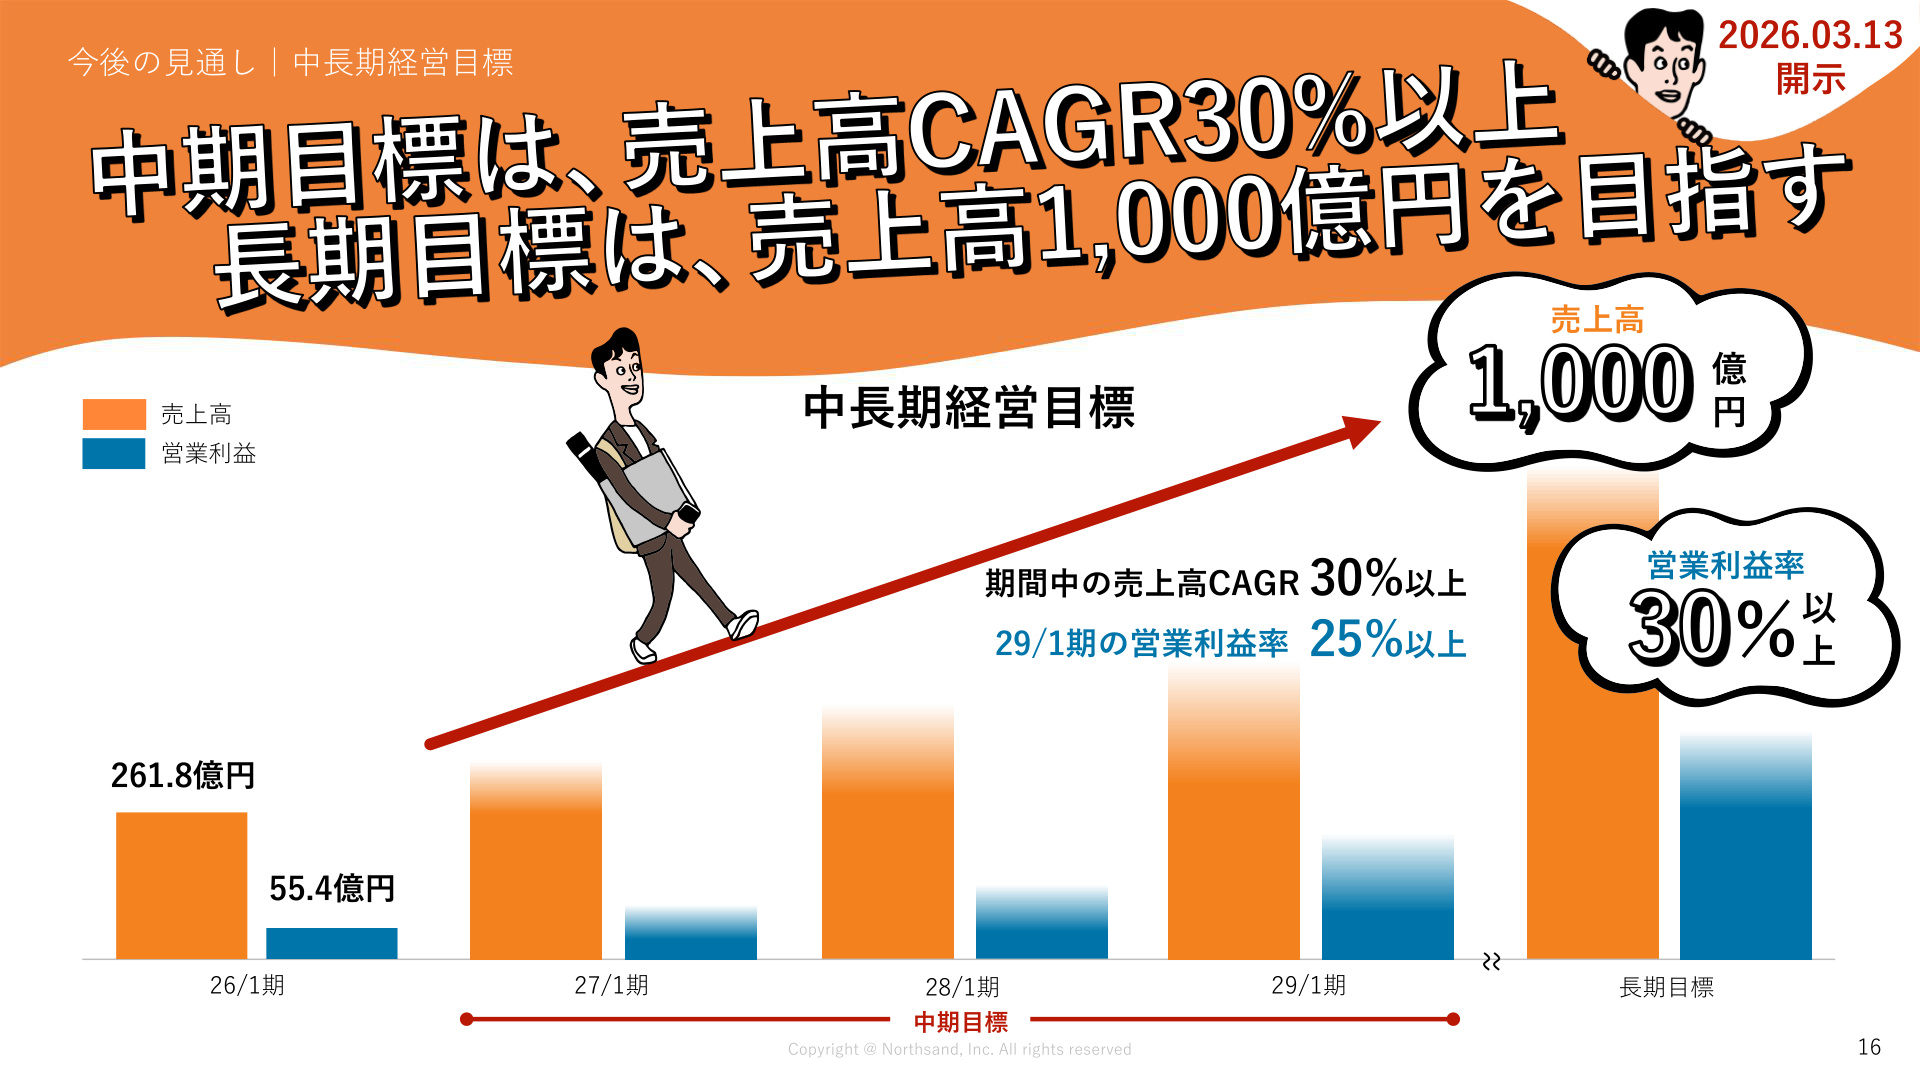
Key Mid-to-Long-Term Management Goals
- Mid-Term Goal : Achieve a CAGR (Compound Annual Growth Rate) of 30% or more in revenue and an operating profit margin of 25% or more by the fiscal year ending January 2029.
- Long-Term Goal : Achieve 100 billion yen in revenue and an operating profit margin of 30% or more .
- Personnel Plan : Build a structure of 3,000 consultants in the mid-term and 5,000 in the long term.
Furthermore, with the aim of sustainable growth and long-term corporate value enhancement, the company disclosed that it submitted an application to transition to the Tokyo Stock Exchange Prime Market on September 7, 2026 . It plans to complete the transition within 2026 (during the fiscal year ending January 2027) to strengthen corporate governance and social credibility.
7. Conclusion
North Sand's Q2 FY2027 earnings report reflects a period where the three major KPIs—consultant recruitment, utilization rate, and unit price—all performed at high levels, resulting in significant growth in both revenue and profit. The series of actions, including the upward revision of the full-year forecast, the dividend increase, and the application for a Prime Market listing, demonstrate the company's confidence in its mid-to-long-term growth and its commitment to the capital markets. Progress toward its long-term goals of "100 billion yen in revenue and 30% operating profit margin" will be closely watched.
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。