

Smaregi FY2027 Q1 Earnings Report: ARR Hits ¥11.58 Billion with 73.3% YoY Operating Profit Growth, Driven by High-Margin Recurring Revenue Model and Mid-Term Plan Progress

StockClub
公開日時: Sep 14, 2026, 10:06 AM
Sentiment Analysis
Smaregi, Inc. reported strong financial results for the first quarter of the fiscal year ending April 2027 (FY2027 1Q). Driven by the steady growth of its core cloud POS service, the rapid expansion of its cashless payment business, and successful cross-selling strategies, the company achieved net sales of ¥3.608 billion (+19.7% YoY) and an operating profit of ¥1.027 billion (+73.3% YoY) , marking a significant increase in both revenue and profit. Annual Recurring Revenue (ARR) reached ¥11.58 billion (+22.9% YoY) , setting a new all-time high.
This report provides a comprehensive analysis of the earnings highlights, shifts in the revenue structure, KPI trends across product lines, and the progress of the 3rd Mid-Term Management Plan, which centers on the "Store OS" vision.
1. FY2027 1Q Earnings Highlights and Structural Transformation of P&L
Performance in the first quarter showed extremely steady progress against initial plans across both top-line sales and all profit stages.
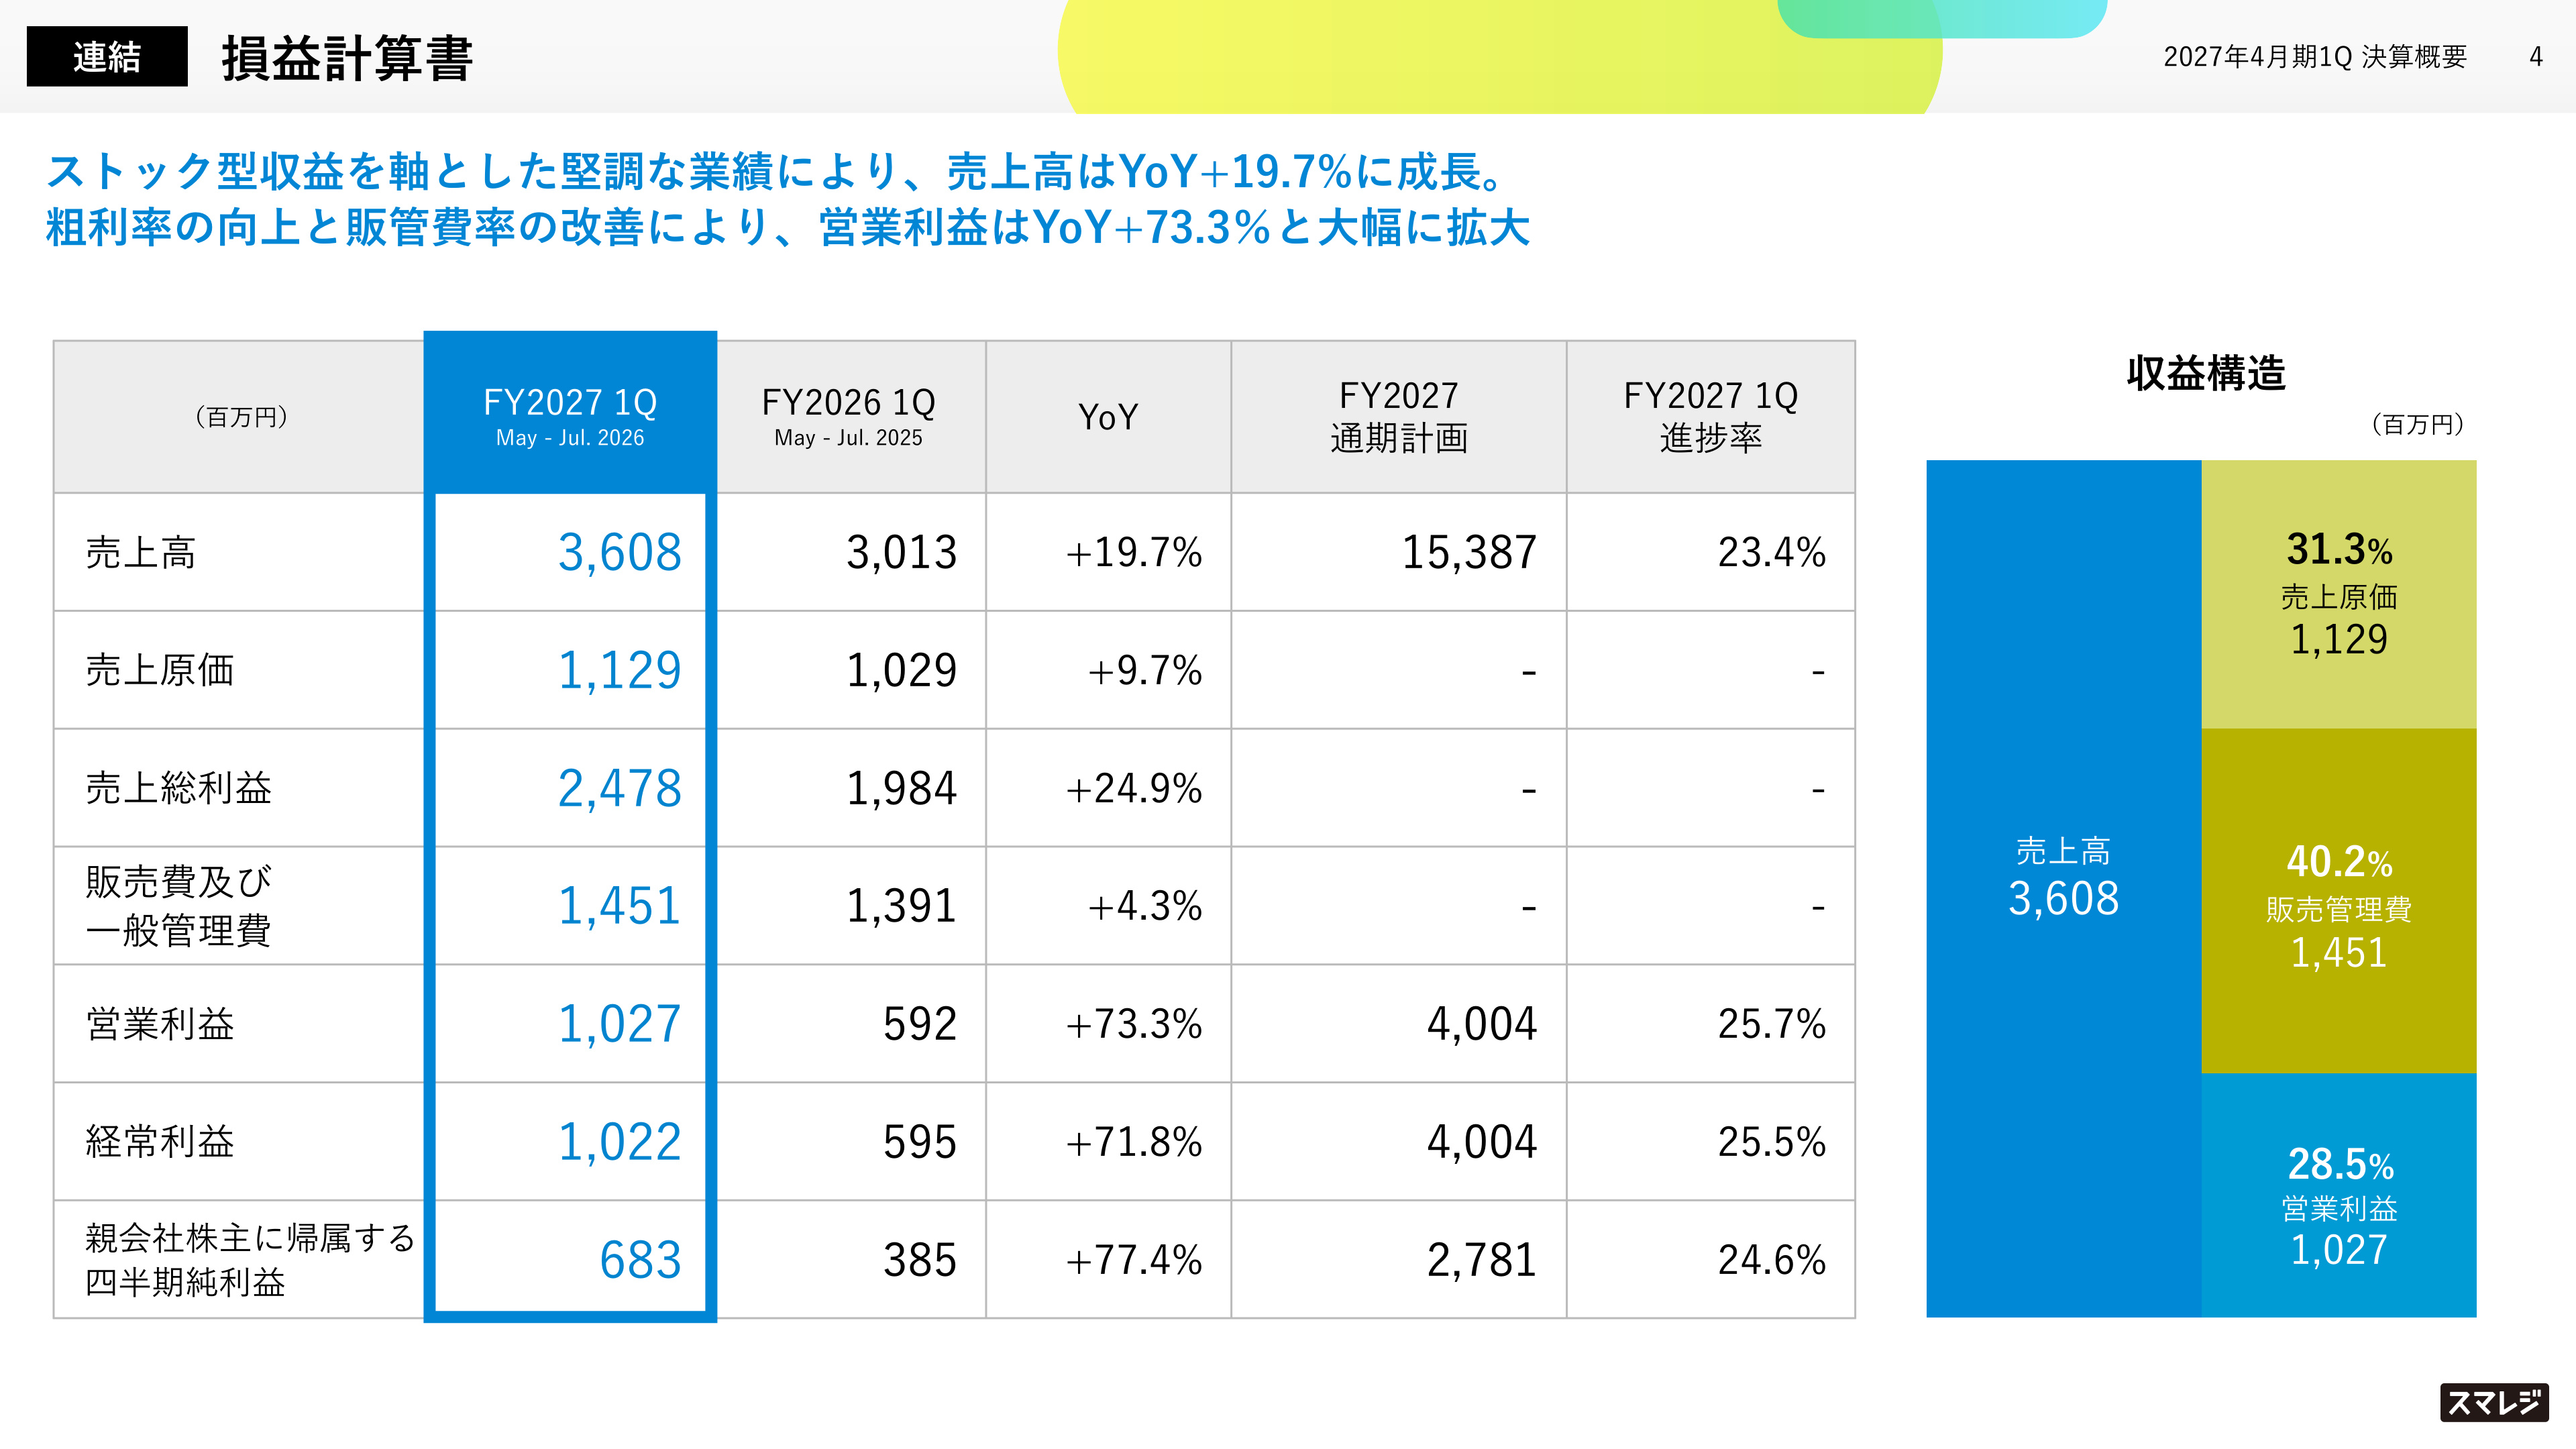
A structural shift evident in the income statement is that the cost of sales grew by only 9.7% YoY, while gross profit expanded significantly by 24.9% YoY. This was driven by cost reductions from internalizing the payment business and an increase in the ratio of high-margin recurring revenue (with gross margins exceeding 80%) to 79.4% .
Selling, General and Administrative (SG&A) expenses were contained at ¥1.451 billion, an increase of 4.3% YoY. Despite rising personnel costs due to organizational expansion, the optimization and increased efficiency of advertising expenses, such as TV commercials, led to a significant improvement in the SG&A-to-sales ratio, which dropped from 46.2% in the same period last year to 40.2% . Consequently, the operating profit margin reached 28.5% (+8.8pt YoY) , the highest profit level on a quarterly basis to date.
Regarding financial position, the company maintains a robust foundation to support future growth investments and M&A, holding ¥7.66 billion in cash and deposits with a high equity ratio of 71.0% .
2. ARR Trends and Expansion of the Revenue Base
The powerful growth of ARR, which represents recurring subscription revenue, symbolizes the expansion of Smaregi's business foundation.
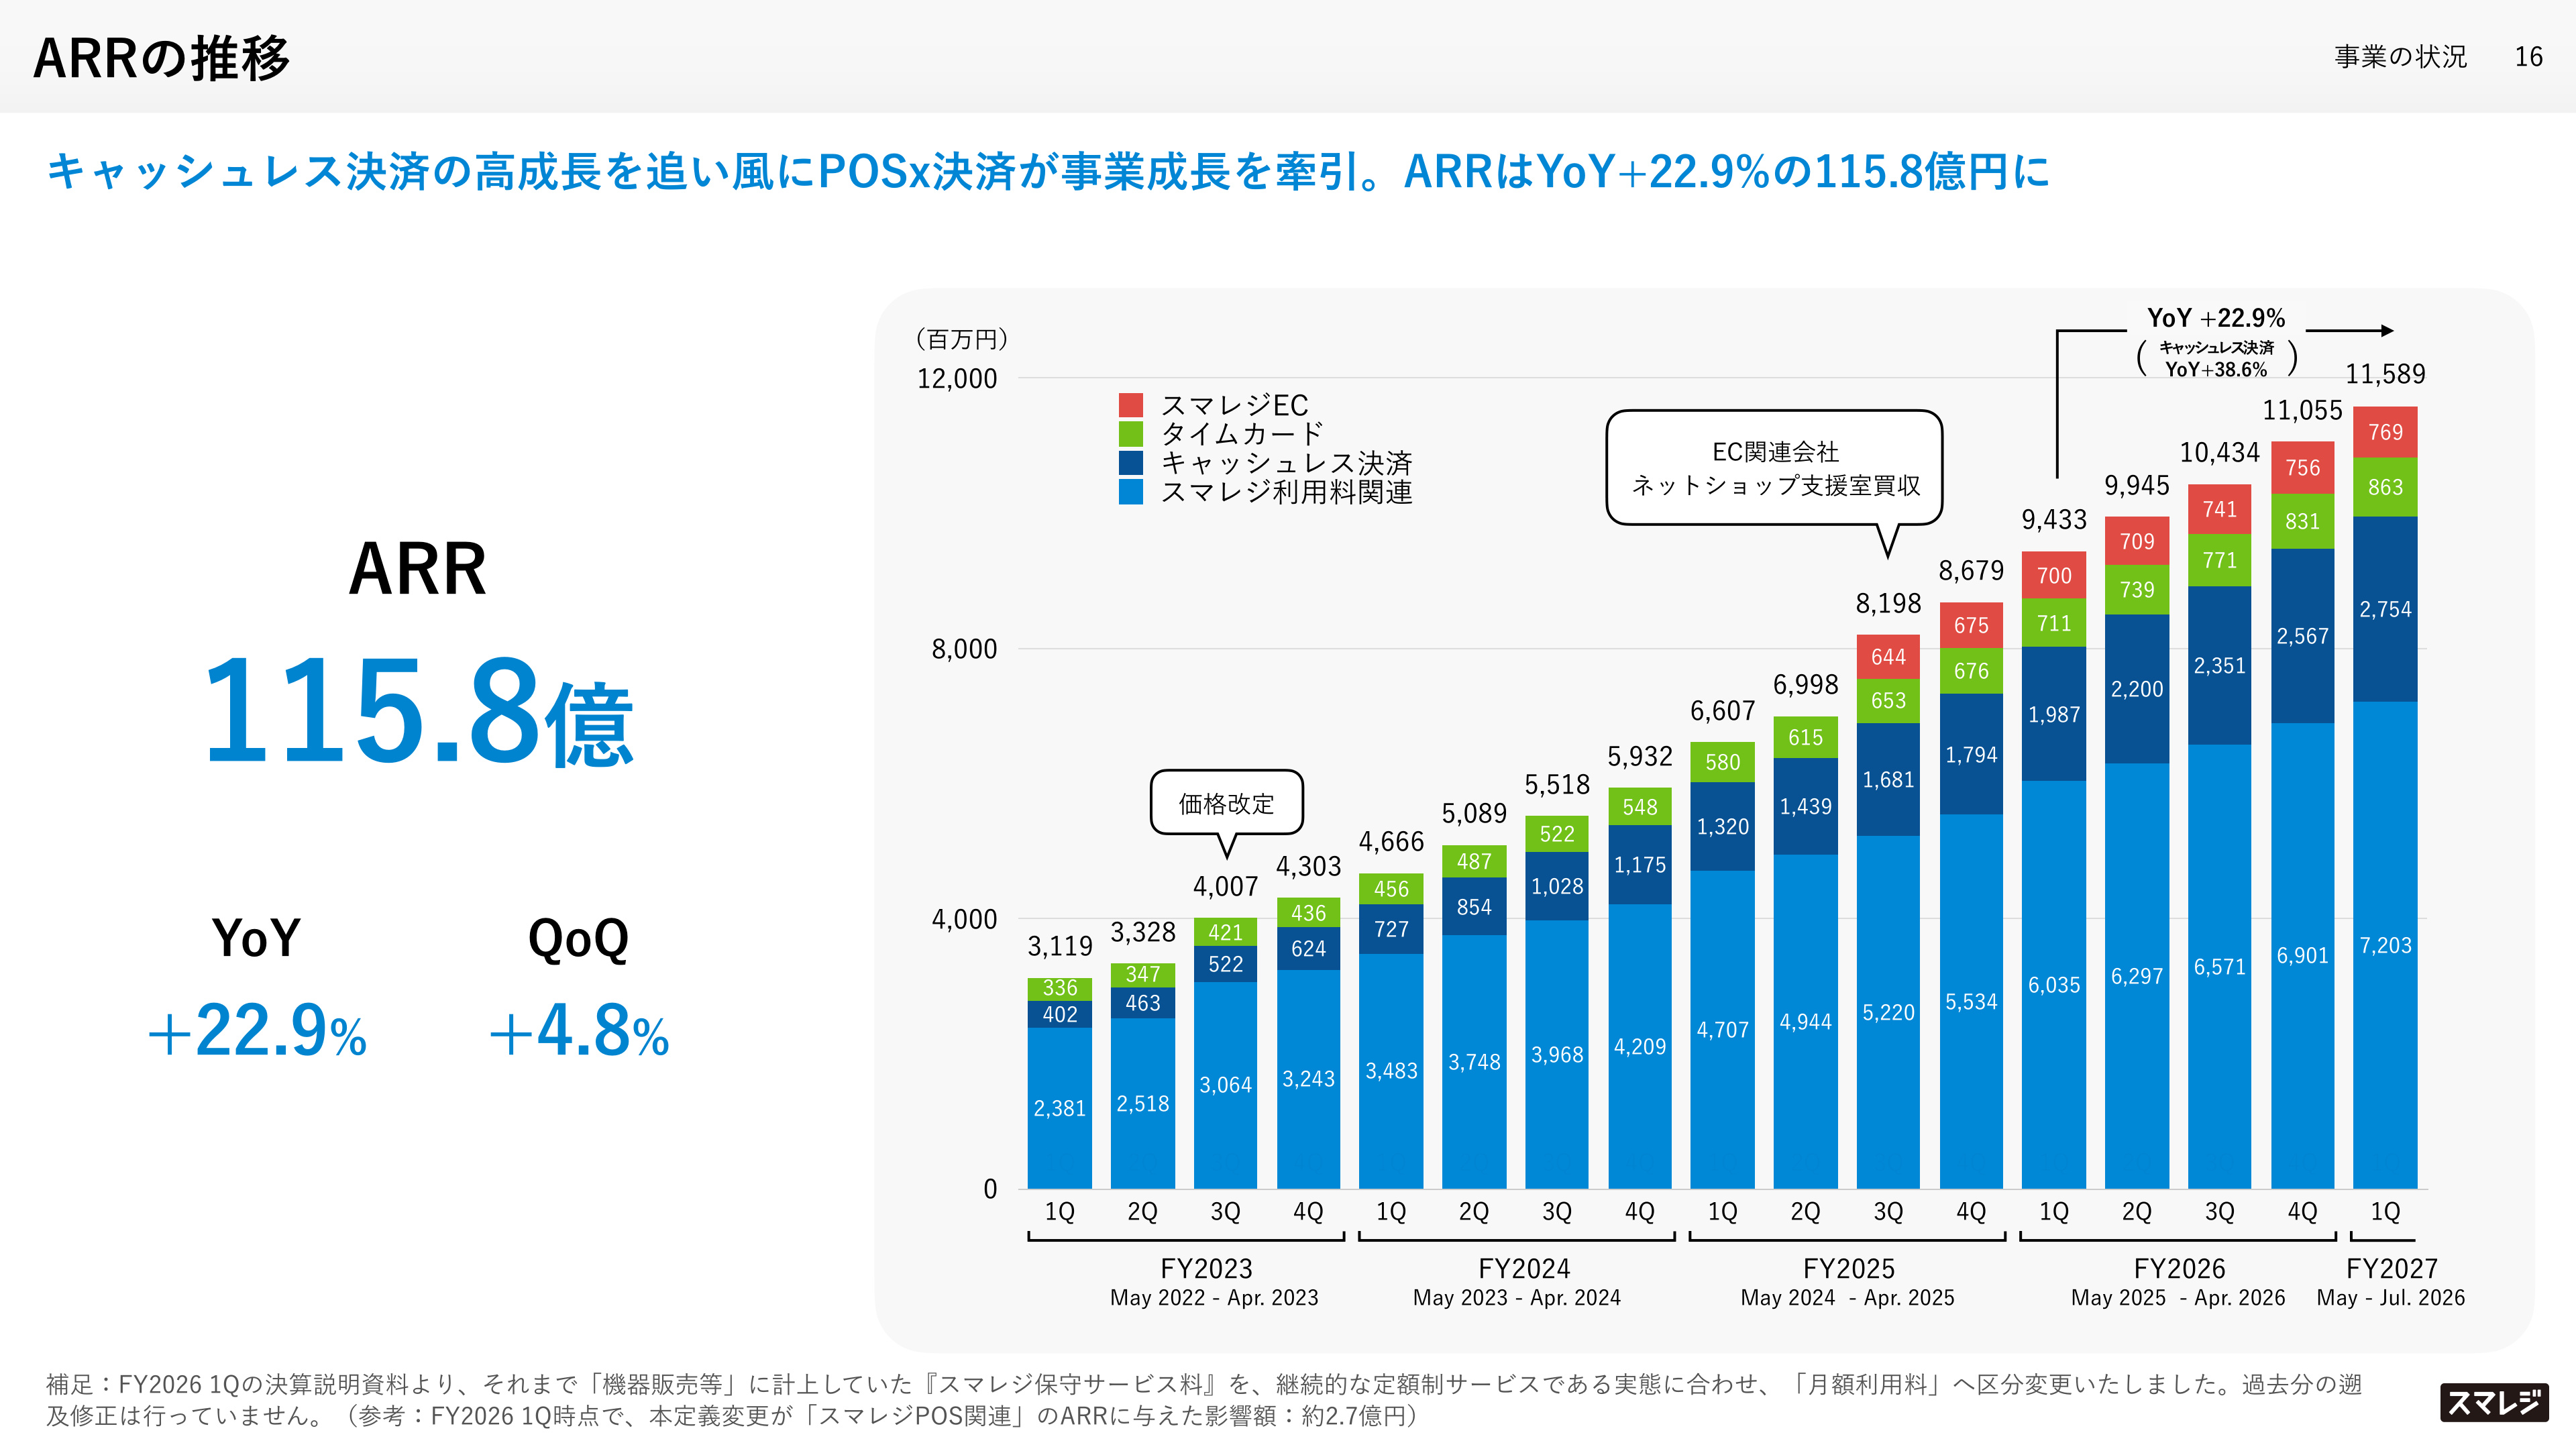
Total company ARR reached ¥11.58 billion, maintaining a growth rate of +22.9% YoY. A breakdown shows that the core product, "Smaregi (POS-related)," maintained steady growth at ¥7.20 billion (+19.4% YoY), while the cashless payment business ARR reached ¥2.75 billion (+38.6% YoY) , maintaining an exceptionally high growth pace.
Furthermore, the attendance management system "Smaregi Time Card" reached ¥860 million (+21.4% YoY), and the EC-related business (formerly Net Shop Shien-shitsu) reached ¥760 million, demonstrating steady expansion across multiple pillars. The transition to a recurring business model centered on monthly fixed fees and transaction-based payment fees, rather than relying on one-time (flow) sales like hardware, is steadily bearing fruit.
3. Key KPI Analysis of the Core POS Business
In the core POS business, Smaregi is simultaneously achieving ideal SaaS metric improvements: expanding the customer base, increasing customer unit prices, and reducing churn rates.
- Number of Paid Stores : Expanded to 49,952 stores (+14.5% YoY) , driven by the acquisition of medium-to-large accounts and multi-store deployments by existing clients.
- Customer Unit Price (ARPA/ARPU) : ARPA (monthly fee per contract) grew to ¥25,505 (+3.8% YoY) , and ARPU (per store) grew to ¥11,520 (+4.5% YoY) . The shift from one-time peripheral hardware purchases to monthly subscriptions is supporting this price increase.
- Churn Rate (MRR Churn Rate) : Due to thorough onboarding support and strengthened customer success, the rate reached a record low of 0.41% (-0.07pt YoY) .
- Gross Merchandise Volume (GMV) : Quarterly GMV expanded to ¥932.1 billion (+22.7% YoY) , with cumulative transaction volume surpassing ¥15 trillion. The cashless payment ratio within GMV has risen to 64.9%.
4. Multi-Product Deployment and Cross-Selling Strategy Progress
Smaregi is pursuing its "Store OS" vision of integrating all functions necessary for store operations, accelerating the cross-selling of other services based on the POS system.
- Cross-Sell Contracts and Unit Price : The number of cross-sell contracts (using POS paid plans alongside other services like payments, time cards, or EC) reached 11,326 , with a cross-sell ARPA of ¥46,148 (+8.8% YoY) , achieving a significantly higher unit price than single-service customers.
- Cashless Payment (PSP) : The number of contracts reached 17,803 (+14.5% YoY), and the payment utilization rate (cross-sell rate) among POS users rose to 34.1% (+6.4pt YoY) .
- Time Card (HR) : Following the price revision (partial transition to paid plans) for the Standard plan, the number of contracts surged to 12,124 (+41.3% YoY) , and the number of registered employees reached 302,000 (+54.6% YoY).
- Smaregi EC : Following the absorption-type merger and organizational integration completed in May 2026, the number of POS x EC cross-sell contracts has approximately doubled YoY. End-to-end proposals for customers seeking OMO (Online Merges with Offline) are gaining traction.
5. External Environment and Mid-to-Long-Term Growth Strategy (3rd Mid-Term Management Plan)
In its 3rd Mid-Term Management Plan (FY2027–FY2029), Smaregi is targeting a CAGR of over 25% .
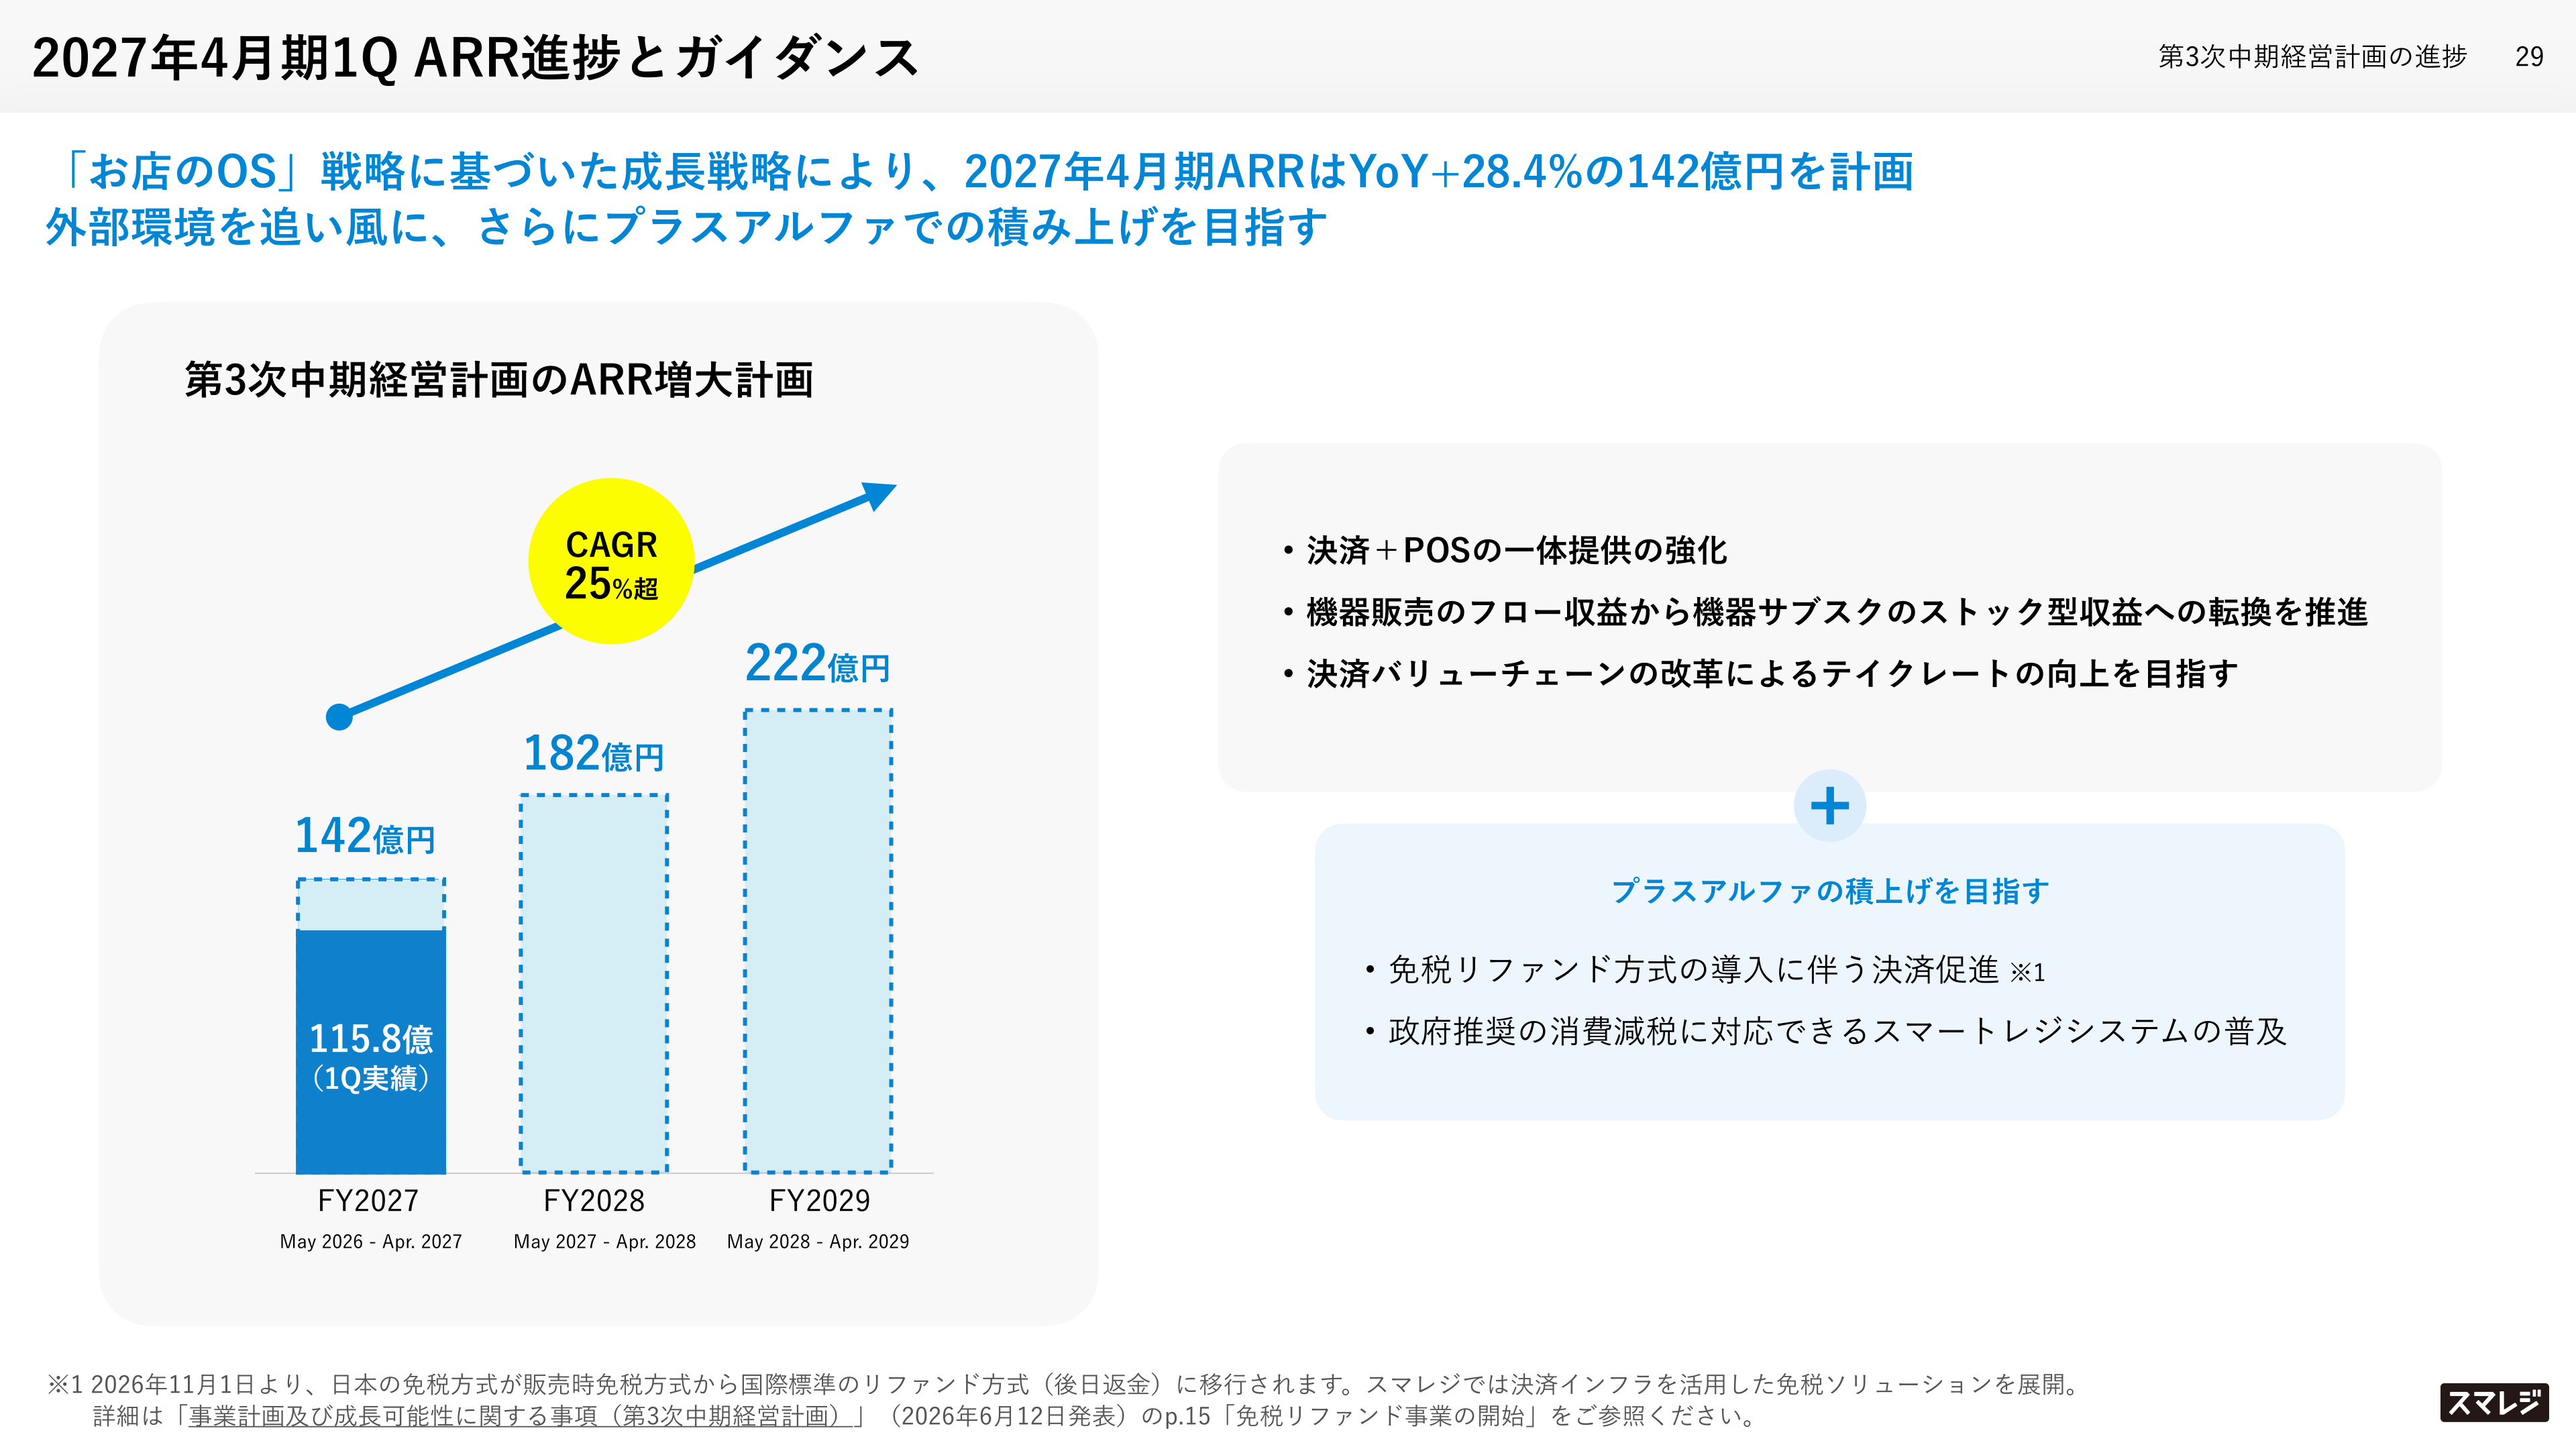
The full-year forecast for FY2027 targets an ARR of ¥14.2 billion (+28.4% YoY) , with goals of ¥22.2 billion in ARR by FY2029 , and an ARR of ¥30 billion under the long-term vision "VISION 2031."
To achieve this, the following tailwinds and growth initiatives are underway:
- Consumption Tax Revisions and Smart Register Adoption : The government's policy to lower the reduced tax rate for food (from 8% to 1%) highlights the advantage of cloud POS systems that can flexibly adapt to frequent regulatory changes, fueling demand for migration from legacy POS systems.
- Introduction of Tax-Free Refund System : With the transition to the international standard refund system starting in November 2026, demand for tax-free solutions utilizing Smaregi's payment infrastructure is expected to grow.
- Launch of "Store OS Fund" : The company has established a framework to accelerate M&A, investments, and group integrations to further expand its product lineup for the retail sector.
Summary
Smaregi's FY2027 Q1 earnings demonstrated a significant improvement in profit margins (operating profit margin of 28.5%) through increased gross margins and controlled SG&A expenses, confirming a further strengthening of its high-profit structure. The accumulation of ¥11.58 billion in ARR and the success of the cross-sell model involving cashless, EC, and HR services provide a powerful foothold for achieving the Mid-Term Management Plan (¥22.2 billion ARR) and the long-term vision (¥30 billion ARR).
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。