

Value Golf Q2 FY2027 Earnings Analysis: Strategic Shift Toward Profitability, AI/DX Investments, and Growth Roadmap for Standard Market Listing

StockClub
公開日時: Sep 14, 2026, 10:03 AM
Sentiment Analysis
1. Q2 FY2027 Earnings Summary and Highlights
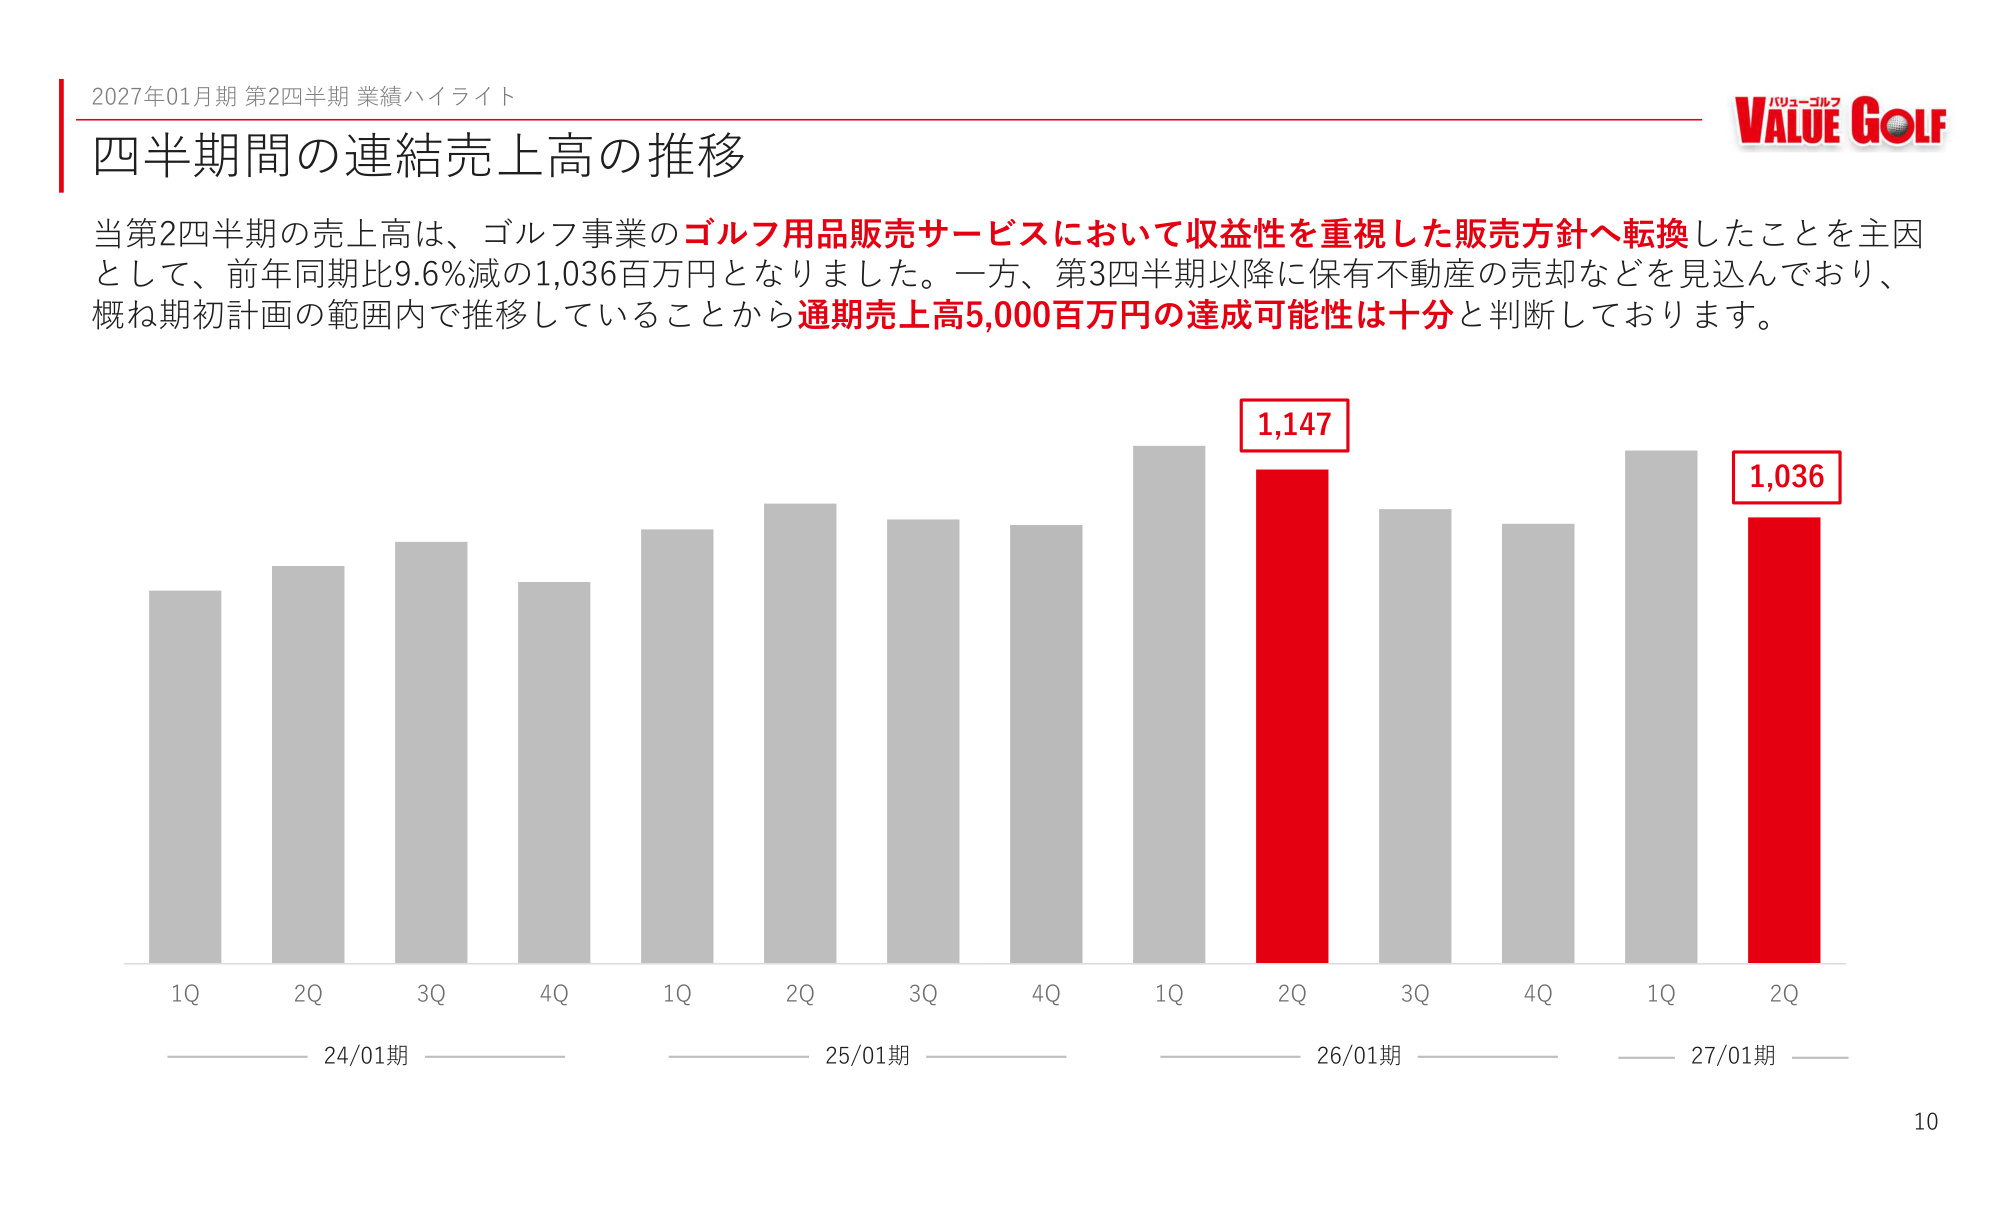
Value Golf Co., Ltd. reported consolidated financial results for the first half of the fiscal year ending January 2027, with net sales of 2,228 million yen (down 5.2% YoY) , operating profit of 26 million yen (down 47.6% YoY) , ordinary profit of 14 million yen (down 68.5% YoY) , and net profit attributable to owners of the parent of 9 million yen (down 68.5% YoY) .
While the headline figures show a decline in both revenue and profit, this is driven by a clear strategic shift: "moving away from excessive price competition toward a profit-oriented policy" and "proactive upfront investment in new service development, including AI-driven solutions." Although the operating profit progress against the full-year target (5,000 million yen in sales, 220 million yen in operating profit) stands at 12.2%, the company expects to recognize gains from the sale of real estate holdings starting in the third quarter . Consequently, performance remains largely within the initial plan, and management maintains confidence in achieving the full-year targets.
| Item | Q2 FY26/01 Actual | Q2 FY27/01 Actual | YoY Change | FY27/01 Full-Year Forecast | Progress Rate |
|---|---|---|---|---|---|
| Net Sales | 2,350 million yen | 2,228 million yen | -5.2% | 5,000 million yen | 44.6% |
| Gross Profit | 793 million yen | 773 million yen | -2.5% | - | - |
| Gross Profit Margin | 33.7% | 34.7% | +1.0pt | - | - |
| Operating Profit | 51 million yen | 26 million yen | -47.6% | 220 million yen | 12.2% |
| Operating Profit Margin | 2.2% | 1.2% | -1.0pt | 4.4% | - |
| Ordinary Profit | 47 million yen | 14 million yen | -68.5% | 190 million yen | 7.9% |
| Net Profit | 30 million yen | 9 million yen | -68.5% | 110 million yen | 8.6% |
2. Factors Behind Operating Profit Fluctuations and Qualitative Changes in Revenue Structure
To accurately interpret the performance in the second quarter, it is essential to understand the drivers behind the changes in net sales and operating profit.
■ Analysis of Sales and Operating Profit Drivers
As shown in the waterfall chart above, while the Golf business (-153 million yen) and Travel business (-63 million yen) saw declines, the "Other" segment, which includes real estate transactions and advertising media production, increased (+94 million yen). The decline in the Golf business is attributed to the "Jeepers" golf equipment retail service, where the company curbed excessive discount competition to chase volume, shifting instead toward high-margin product selection and sales strategies.
Operating profit fluctuations are driven by three main factors:
- Improved Profitability in the Golf Business (+9 million yen) : Despite lower sales, segment profit increased due to the shift in retail policy and steady performance of core web services.
- Fluctuations in Travel and Other Businesses (-6 million yen) : Impacted by a cooling in demand for overseas tours due to the weak yen and changes in business composition.
- Increase in Adjustments (-27 million yen) : Upfront investments in AI-driven new service development and one-time costs associated with business acquisitions.
The gross profit margin improved by 1.0 percentage point to 34.7% from 33.7% in the same period last year, confirming a steady strengthening of the profit structure over top-line expansion.
3. Application for Market Reclassification to the Standard Market and Financial Position
On September 14, 2026, Value Golf resolved to begin preparations for applying to transition its listing to the Tokyo Stock Exchange Standard Market.
■ Status of Compliance with Standard Market Listing Criteria (As of end of Jan 2026)
- Number of Shareholders : 1,264 (Requirement: 400+) (Compliant ○)
- Number of Tradable Shares : 6,620 units (Requirement: 2,000+) (Compliant ○)
- Ratio of Tradable Shares : 36.6% (Requirement: 25%+) (Compliant ○)
- Net Assets : 1,073 million yen (Requirement: Positive) (Compliant ○)
- Market Cap of Tradable Shares : Approx. 989 million yen (Requirement: 1,000 million yen+) (△)
The market capitalization of tradable shares is very close to the threshold, and the company aims to fully satisfy this requirement through future earnings growth and corporate value enhancement initiatives.
■ Financial Position
Total assets were 3,192 million yen (+7 million yen from the previous fiscal year-end) , total liabilities were 2,159 million yen (+48 million yen) , and net assets were 1,032 million yen (-40 million yen) . Inventory assets account for 1,335 million yen, reflecting stock held for golf equipment retail and land held for sale in the real estate business. The company employs a leveraged management strategy using debt, resulting in an equity ratio of 32.3% , though financial health is expected to improve following the planned sale of real estate holdings.
4. Segment Performance and Key KPI Progress
① Golf Business (Sales: 1,920 million yen, Operating Profit: 148 million yen)
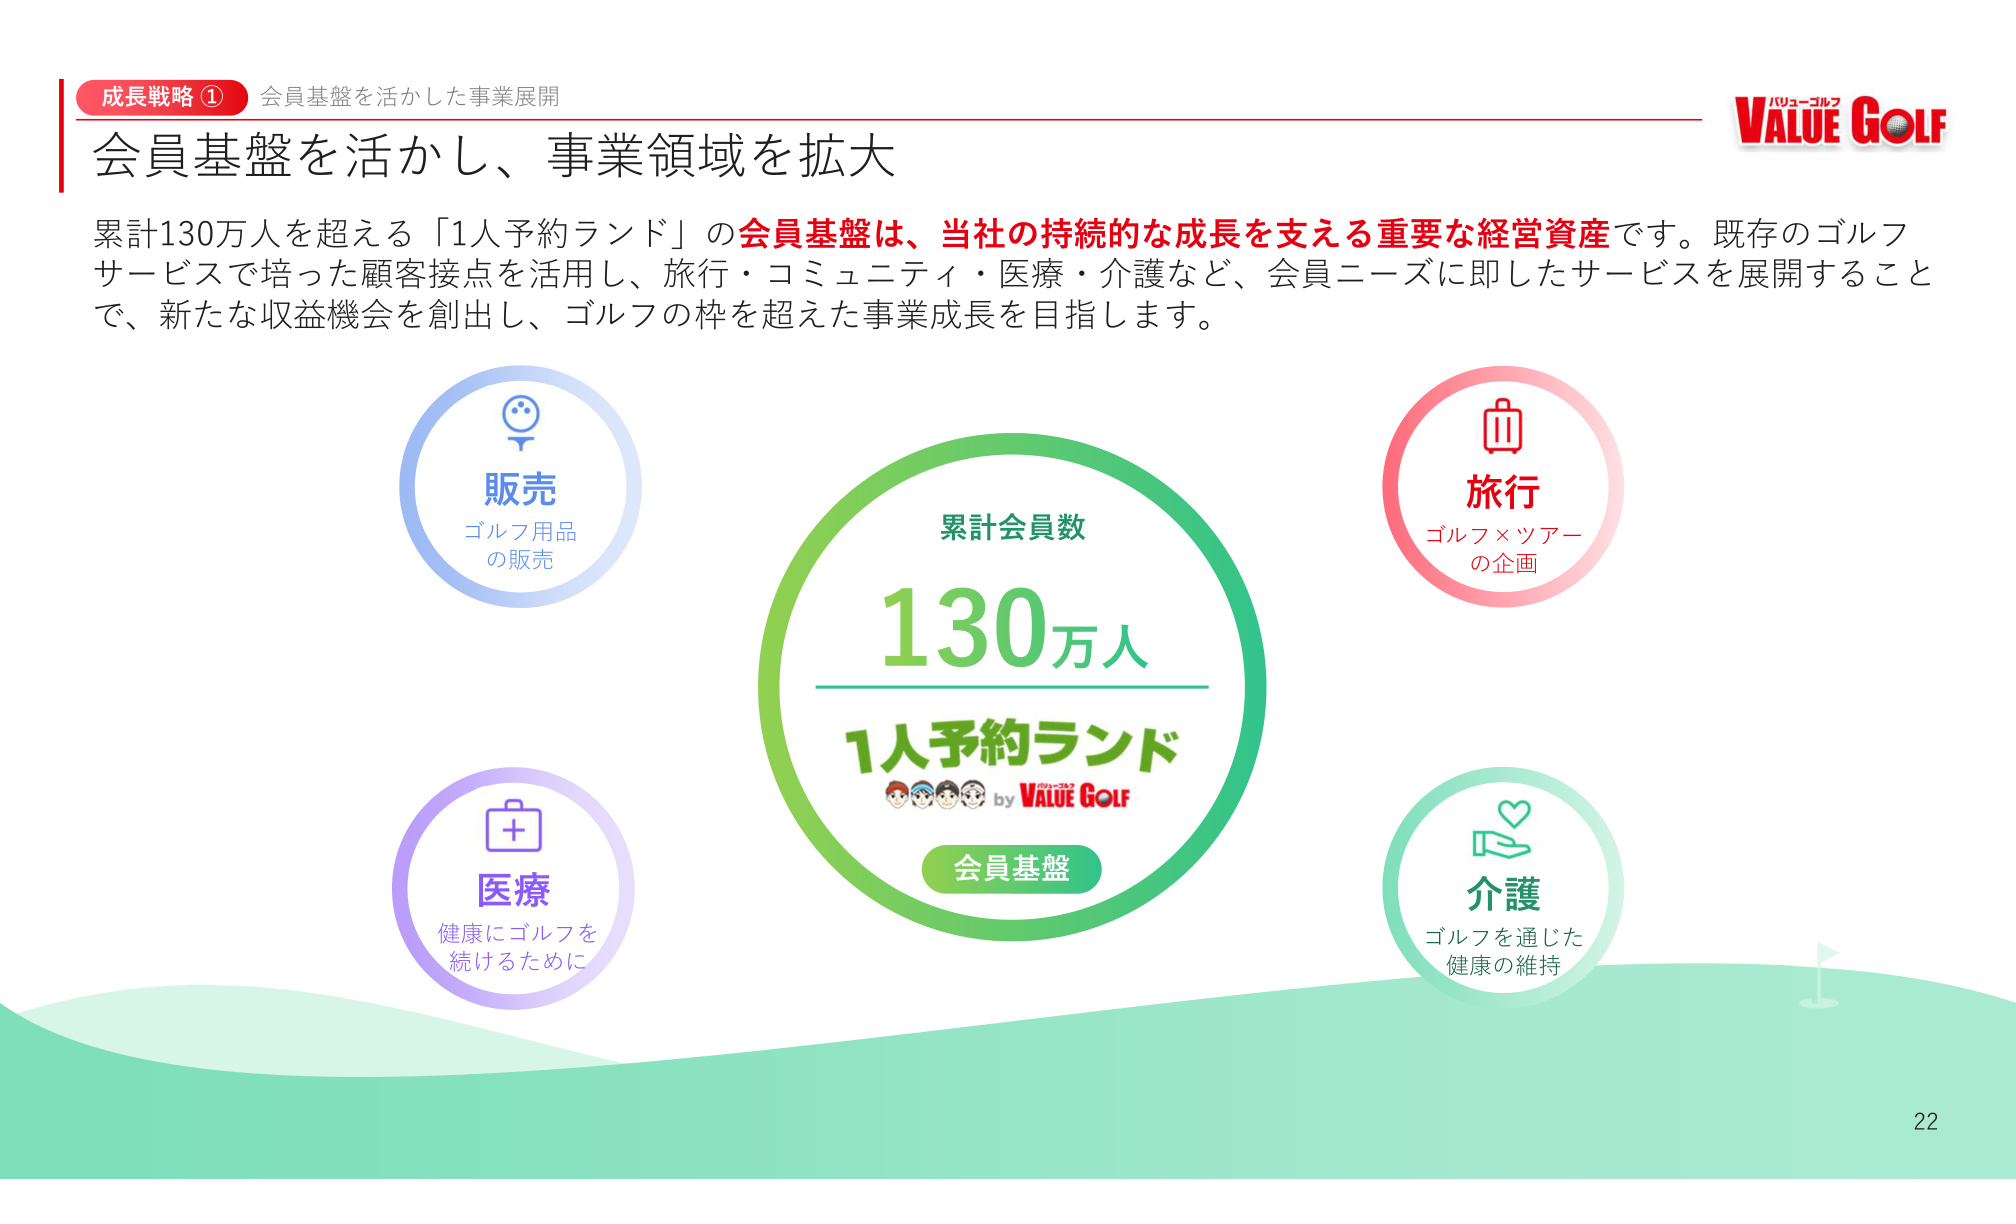
- "1-Person Reservation Land" Membership : The core asset reached 1.29 million members, a 7.5% YoY increase (approx. 90,000 increase) , and surpassed 1.3 million as of September 2026. The company continues to see a steady net increase of about 100,000 members per year.
- Number of Contracted Courses : The network continues to expand, reaching 1,280 courses . The company aims to maximize referral fee revenue by increasing the availability of high-demand "golden slots" (weekends and holidays).
- Golf Equipment Retail "Jeepers" : Operating four physical stores in the Tokyo metropolitan area and an e-commerce site, the company is expanding private brand (PB) products and direct-import models to boost gross margins.
② Travel Business (Sales: 227 million yen, Operating Profit: 18 million yen)
Despite a cautious stance on overseas tour demand due to the historic weak yen, the company successfully captured demand for domestic golf trips to prestigious courses. This segment is seasonally weighted toward the first half due to high-ticket "Masters Viewing Tours" held in Q1.
③ Other Businesses (Sales: 80 million yen, Operating Profit: 0 million yen)
In addition to advertising media production (bolstered by the M&A of Noah Co., Ltd.), the company is engaged in real estate development targeting the utilization of idle golf course land. Following Q1, monetization from real estate sales is planned for the second half.
5. Growth Strategy: "Customer Base × Golf Course Network × AI"
To achieve sustainable growth, Value Golf is deploying a strategy that integrates its long-cultivated "strong customer base" and "industry-leading golf course network" with "AI technology."
■ toC Strategy: Maximizing LTV of the 1.3 Million Member Base
The active golfer base of over 1.3 million is the company's greatest competitive advantage. Active users book an average of four times per month, and 81% of users are avid golfers with scores between 90 and 100.
- Activating Light Users (86.3%) : The company aims to increase booking frequency among the low-frequency segment by using AI recommendations and attractive plan proposals.
- Expansion of PB and Partner Products : Increasing the ratio of high-margin original golf equipment (balls, gloves, shoes, etc.) and developing high-performance golf apparel in collaboration with "Relive Co., Ltd.," which has a track record of over 5 million units sold.
- Launch of AI Golf Support App "MySwing" : An app providing swing diagnostics based on skeletal structure and flexibility, an AI caddie, and condition management is scheduled for release soon, supporting golfers' health and promoting lifetime customer value.
6. toB Strategy: "Ripi-Zo-Kun DX" – Driving Golf Course Digital Transformation
Value Golf has business connections with approximately 1,700 courses, representing about 70% of all golf courses in Japan. Leveraging this, the company is expanding into total DX support for golf course operations.
{{PAGE_30}}
■ Digitalizing the Experience with "Ripi-Zo-Kun DX"
The company is evolving its existing web booking engine, "Ripi-Zo-Kun," into "Ripi-Zo-Kun DX," a one-stop digital solution covering everything from check-in to payment and repeat-visit promotion.
- Attraction/Booking : Optimization of proprietary web booking systems and email marketing management.
- Arrival/Reception : Introduction of self-check-in using app membership cards to reduce front-desk congestion.
- Play/Dining : Mobile ordering systems and GPS cart navigation integration.
- Settlement/Accounting : Fully cashless self-payment to improve operational efficiency and address labor shortages.
- Repeat Promotion : Automated notifications of coupons and exclusive plans based on accumulated play data.
The company aims to expand adoption as a solution that simultaneously reduces labor and increases average spend per customer in an industry facing severe labor shortages.
7. Conclusion and Future Outlook
The Q2 FY2027 results represent more than just current sales and profit figures; they mark a critical foundation for a transition toward a high-profit structure in the medium to long term.
Key points to monitor moving forward include:
- Second-Half Recovery : Progress toward the 220 million yen operating profit target, contingent on the closing of real estate sales.
- Profitability of Equipment Retail : The rise in the PB product ratio at Jeepers and sales trends of collaborative products.
- Launch of New AI/DX Services : User acquisition for the "MySwing" app and the number of courses adopting "Ripi-Zo-Kun DX."
- Standard Market Reclassification Review : Progress in meeting criteria, particularly the market capitalization of tradable shares, and the status of formal approval.
個別の投資に関する推奨やアドバイスを提供することを意図しておりません。ここで述べられている意見や見解は、あくまでも各記事の個人的見解です。